Blog

Jul 28, 2026

How to Order Checks Overnight: Fast Delivery Guide for Businesses and Individuals

In This Guide:


Why Businesses Suddenly Need to Order Checks Overnight

Running out of checks at the wrong moment is more common than most business owners expect. The most frequent situations that drive someone to order checks overnight are not the result of carelessness. They are the result of check usage being irregular and hard to predict.

Payroll is the most critical trigger. When a payroll run is due and the check supply runs out the day before, the problem is immediate and has legal consequences in most US states. Late payroll carries financial penalties and employee relations risks that make an overnight check order well worth the cost.

Other common reasons to order checks fast include:

  • A month-end accounts payable run that uses more checks than expected
  • A bank merger or routing number change that invalidated existing check stock
  • A new business account with no starter checks and an immediate vendor payment due
  • Lost or stolen check stock that needs to be replaced before a payment deadline
  • A printing error on the existing check batch that makes them unusable
  • A reorder that was placed too late and standard delivery will not arrive in time

Whatever the trigger, the solution is the same: an overnight check order that gets at least a working supply of checks to your door by the next morning. For business checks, Checkomatic's SuperRush option is designed exactly for this situation.
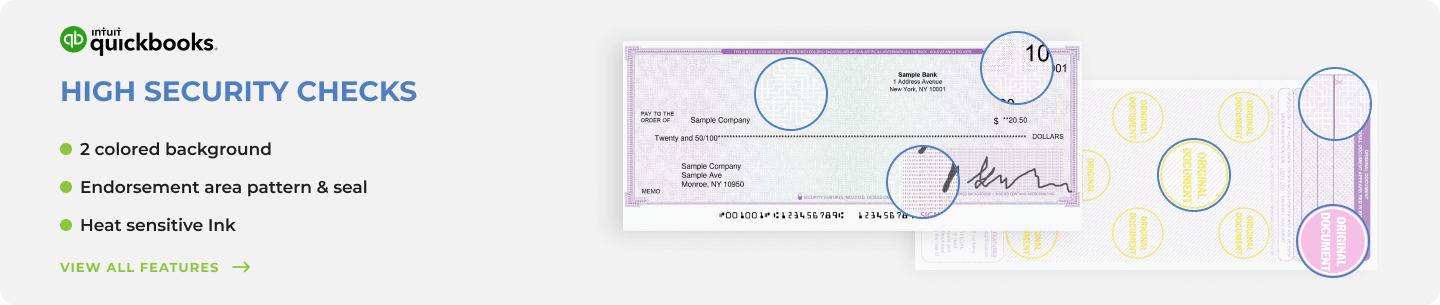
2 colored background, Endorsement area pattern and seal, Heat sensitive Ink


Checkomatic Rush and Overnight Delivery Options

Checkomatic offers two rush production upgrades for business checks, each designed for a different level of urgency. Both are available for business checks. Personal checks have a separate rush option.


Rush Production (+$29.95)

Rush production processes your order the same business day it is placed, as long as you order before 3:00 PM Eastern Time Monday through Thursday. After same-day production, your checks ship via the shipping method you selected at checkout. If you chose Ground shipping, your order ships same day but still takes transit time to arrive. If you chose Next Day shipping, your checks ship same day and arrive the next business day.

Rush production without Next Day shipping is useful when you need faster turnaround than standard but are not in an emergency that requires next-morning delivery.


SuperRush Production (+$54.95) , For Ordering Checks Overnight

SuperRush is the option to choose when you need to order checks overnight and have a working supply by the next morning. It works as follows:

  • Your order is processed the same business day (before the 3:00 PM EST cutoff)
  • The first 50 checks in your order are shipped overnight and delivered the next morning
  • The remaining checks in your order ship via the shipping method you selected at checkout

The result is that you have 50 functional, bank-compliant checks at your door by the next morning. For most urgent payroll or vendor payment situations, 50 checks are enough to cover the immediate need while the full order is in transit.


Personal Checks Rush (+$29.95)

Personal checks have a single rush option that ships the order within 3 business days. This is a production speed upgrade, not an overnight delivery option. If you need personal checks urgently for a business situation, consider whether business checks or QuickBooks checks might better serve your need, as those have the SuperRush overnight delivery option available.


The 3 PM EST Cutoff: What It Means and Why It Matters

To order checks overnight and receive them the next morning, your order must be placed before 3:00 PM Eastern Time on a Monday, Tuesday, Wednesday, or Thursday. This cutoff is not arbitrary. It represents the latest point at which production can begin the same day and the order can be handed off to UPS or FedEx in time to make that evening's overnight shipping pickup.

If you are on the West Coast and want to order checks overnight, noon Pacific is your window. This is a tighter deadline than most West Coast business owners expect when they first encounter it.


What Happens to Orders After the Cutoff

Orders placed after 3:00 PM EST are processed the next business day. This means if you place a SuperRush order at 4:00 PM on a Wednesday, production begins Thursday morning and the 50-check overnight delivery arrives Friday morning , not Thursday morning.

Orders placed on Friday after 3:00 PM, or on Saturday and Sunday, begin production Monday and overnight delivery arrives Tuesday morning. Checkomatic is closed Friday afternoons, Saturdays, and Sundays, and federal holidays are excluded from the rush processing schedule.


Proof Approval and the Cutoff

After placing your order, Checkomatic sends a digital proof showing exactly how your checks will print. You must approve this proof before production begins. If you place your order at 2:45 PM EST and do not approve the proof until 3:30 PM, the cutoff has passed and your order will not ship overnight.


All Four Shipping Methods Explained

Checkomatic uses UPS and FedEx for most US shipments. Orders to Alaska, Hawaii, and APO/FPO military addresses ship via USPS. Your shipping cost is calculated at checkout based on your order size and delivery address. Free shipping is available on orders of $150 or more using code FREE150PLUS at checkout.


Free Pickup (Monroe, NY)

If your business is near Monroe, New York, you can place a rush order and pick it up at Checkomatic's office at 308 Museum Village Road, Monroe, NY 10950 for free. Call ahead to confirm your order is ready before driving: 1-800-555-6374. Office hours are Monday through Thursday 9:30 AM to 5:30 PM EST and Friday 9:30 AM to 12:30 PM EST.


Ground Shipping

Standard UPS or FedEx Ground transit. Combined with Rush production, this is the most cost-effective option when you need faster production but are not in an overnight emergency. Transit time depends on your distance from Monroe, NY.


2-Day Shipping

Guaranteed delivery within 2 business days after production completes. Combined with Rush production (same-day processing), this means delivery in 3 business days total from your order date. A good middle ground between cost and urgency when you have 3 days but not 5.


Next Day Shipping

Delivery 1 business day after production. Combined with SuperRush (same-day production), this is the overnight check delivery combination. Your 50 initial checks arrive the next morning, and the remaining checks follow via your chosen shipping method.


Which Check Types Can Be Ordered Overnight

SuperRush overnight delivery is available for all Checkomatic business check types. The choice of check type does not affect your ability to get checks overnight. What matters is selecting the right format for your workflow before you order.


Computer Checks (Fastest to Print, Best for Overnight Orders)

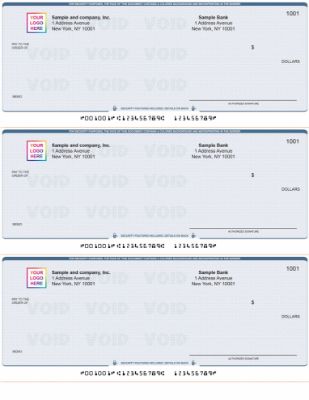
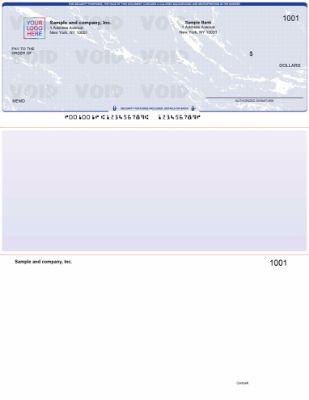
Computer checks in all four formats are available with SuperRush: check on top (voucher), check in middle, check on bottom, and 3-on-a-page. These are the most commonly ordered business checks and the fastest to process because they require no hand-filling after delivery. You print from QuickBooks, Xero, Sage, or any compatible accounting software and the checks are ready to sign and mail.

Browse the full range at checkomatic/computer-checks.
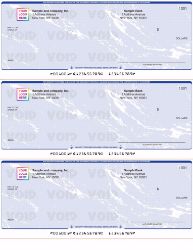
Computer Checks - 3 on a Page


QuickBooks Checks (Default Format for QB Users)

If you use QuickBooks Desktop or QuickBooks Online, the voucher check (check on top) is the default format your software is configured to print to. Order this format when you need to order QuickBooks checks overnight. Before placing your rush order, confirm your QuickBooks check style is set to Voucher at File, Printer Setup, Form Name: Check in QuickBooks Desktop, or at Settings, Print Checks, Print Setup in QuickBooks Online.

Browse QuickBooks-compatible checks at checkomatic/quickbooks-checks.
Blue


Manual Business Checks

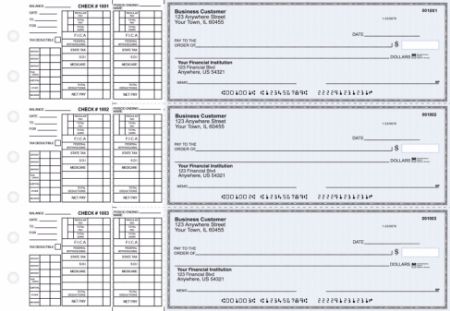
Manual 3-on-page checks (accounts payable, payroll, and multi-purpose formats) are available with rush production. Manual checks are the right choice when you need a working check supply immediately and do not have a printer available or accounting software configured for check printing. They work with a pen and require no setup. Browse manual options at checkomatic.com/manual-checks.
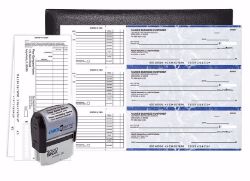
 

Manual Starter Pack

Personal Checks

Personal checks have a rush option that ships within 3 business days. Overnight morning delivery (SuperRush) is not available for personal checks. If you need personal checks urgently, the 3-business-day rush is the fastest available option. Browse personal check options at checkomatic.com/personal-checks.


Step-by-Step: How to Order Checks Overnight at Checkomatic

  1. Confirm the time. Check the clock. It must be before 3:00 PM Eastern Time on a weekday (Monday through Thursday, excluding holidays). If you are in Pacific time, noon is your cutoff. If you have already missed today's cutoff, plan for tomorrow's order.
  2. Select your check type. Go to checkomatic.com/business-checks and select the check format you need. For QuickBooks users, check on top (voucher) is almost always correct. If you are unsure, check your accounting software's check style setting before ordering.
  3. Choose SuperRush before adding to cart. On the product page, select SuperRush (+$54.95) from the production option. This is the step that guarantees same-day processing and overnight delivery of your first 50 checks. If you skip this step and just select standard, your order will not ship overnight regardless of the shipping method you choose at checkout.
  4. Enter your check information carefully. Fill in your business name, mailing address, ABA routing number (from the bottom left of any existing check), checking account number, and starting check number. Verify every digit twice before proceeding. A wrong routing or account number requires a full reprint and a new rush fee, killing your overnight timeline.
  5. Add logo if needed (or skip for speed). Free black-and-white logo printing is included on every order. However, a new logo upload adds a review step that can slow approval. If speed is the priority and your logo is not on file, consider placing the rush order without a logo and adding it to your next regular order.
  6. Select Next Day shipping at checkout. This ensures the 50 SuperRush checks ship overnight for next-morning delivery. Ground or 2-Day shipping combined with SuperRush production still gives faster turnaround than standard, but only Next Day shipping at checkout delivers by the next morning.
  7. Provide a physical street address. Do not use a P.O. Box. UPS and FedEx overnight delivery services require a physical address. A staffed business address where someone can accept the delivery is best. If you are sending to a home address, confirm someone will be there to receive the package.
  8. Complete checkout and watch your email. After payment, Checkomatic sends a digital proof to your email. Open it immediately and review every field: business name, address, routing number, account number, starting check number, and logo. Approve it as fast as possible. The production clock starts when you approve the proof, not when you place the order.
  9. Track your order. After production and shipping, Checkomatic emails your UPS or FedEx tracking number. Use this to confirm the estimated delivery window and ensure someone is available to receive the overnight package at your address.


Address Rules for Overnight Check Delivery

The address you enter at checkout determines whether your overnight check delivery actually succeeds. Carrier rules for overnight services are stricter than for standard ground shipping, and any address issue that triggers a delivery exception wastes your rush fee and delays your checks.


Never Use a P.O. Box for Overnight Orders

UPS and FedEx cannot always deliver to P.O. Boxes. Tracked overnight services are frequently rejected or delayed at P.O. Box addresses because these carriers require a physical location for their delivery driver. Checkomatic specifically warns against using a P.O. Box for tracked orders. Use your business street address or a home street address where someone will be present.


Include Suite or Unit Numbers

If your business address has a suite number, include it every time. Missing suite numbers cause delivery exceptions on overnight packages because the driver cannot locate the specific unit in a multi-tenant building. Enter the suite number on the address line (e.g., 400 Main Street Suite 205, not 400 Main Street).


Use a Staffed Receiving Location

Overnight packages from UPS and FedEx require a signature or an attended delivery for high-value items. If your overnight check order arrives at an empty office or unattended location, the driver may leave a missed delivery notice and reattempt the next business day. This defeats the purpose of the overnight order. When possible, have someone at the delivery address the morning after your rush order.


What to Do If You Missed the Cutoff to Order Checks Overnight

If you realize you cannot meet today's 3 PM cutoff, the next step depends on how urgent your payment need is.


Option 1: Order Now for Next Available Overnight

Place your SuperRush order now, even after the cutoff. Production will begin the next business day morning, and the 50-check overnight delivery will arrive the following morning. This adds one day to your timeline but locks in the fastest possible delivery given the cutoff miss. Waiting until tomorrow to place the order adds another day unnecessarily.


Option 2: Call Checkomatic Directly

For time-critical situations, call 1-800-555-6374 during business hours (Monday through Thursday 9:30 AM to 5:30 PM EST, Friday 9:30 AM to 12:30 PM EST) and explain your situation. The team can advise on whether there is any flexibility in the current production window and confirm the fastest available timeline for your specific order.


Option 3: Pick Up at Monroe, NY

If you are near Monroe, New York and can physically pick up your order, same-day pickup may be available for rush production orders placed early enough in the business day. Call ahead before driving: 1-800-555-6374. The office address is 308 Museum Village Road, Monroe, NY 10950.


Bridge Payment Options While Waiting for Checks

If your check order is in transit and you need to make a payment before it arrives, these bridge options cover the gap without missing a payment deadline.


ACH Bank Transfer

ACH (Automated Clearing House) transfers are same-day or next-business-day electronic payments sent directly between bank accounts. Most US banks offer ACH through online banking at no cost or low cost. For vendor payments where the vendor has bank account information on file, ACH is often the fastest bridge option when you are waiting to order checks fast and cannot wait for delivery.


Wire Transfer

Wire transfers are immediate same-day payments, typically processed within a few hours of submission. Wire fees range from $15 to $35 per transfer depending on your bank. For large urgent vendor payments or contractor payments, a wire is the fastest bridge option while your check order is in production.


Request a Brief Payment Extension

Most vendors and contractors are understanding when a business contacts them in advance to explain a 1 to 2 day payment delay due to a check supply issue. A brief professional message explaining the situation and providing a confirmed delivery timeline for the check is usually sufficient to avoid late payment consequences. Contact your vendor proactively rather than letting the payment date pass without communication.


Payroll-Specific Options

For payroll emergencies, temporary direct deposit or ACH payroll runs are the fastest bridge. Most payroll software including QuickBooks Payroll, Gusto, and ADP can run an emergency direct deposit payroll if you have employees' bank account information on file. If you run payroll by check because employees do not have bank accounts, contact your bank about emergency cash options for the affected employees while the checks are in transit. For complete payroll check options, see our business checks for payroll guide.


How to Avoid Running Out of Checks and Needing Overnight Delivery

The best way to avoid ever needing to order checks overnight in an emergency is to reorder before running low. The practical rule for most businesses is to reorder checks when you have approximately 25 checks remaining. At typical business volumes of 3 to 5 checks per day, 25 checks gives you 5 to 8 days of supply. Standard production and shipping takes 3 to 5 business days, so a 25-check reorder trigger gives you a comfortable buffer without ever needing to pay rush fees.

For businesses running payroll, the reorder trigger should be based on payroll needs, not just daily usage. Always keep at least one full payroll run worth of checks in supply before placing a reorder. If your monthly payroll requires 30 checks, your reorder trigger is 35 checks remaining, not 25.

Setting a physical reminder on your check storage (a paper note on the bottom of the stack that says "Reorder now") prevents the surprise of reaching for a check and finding nothing. A calendar reminder set 2 weeks after each order arrives keeps the reorder timeline proactive rather than reactive.


Why Choose Checkomatic for Rush and Overnight Check Orders

In-House Manufacturing in Monroe, NY Since 1997

All checks are manufactured at Checkomatic's own facility. No third-party print vendors. When you place a SuperRush order before 3 PM, production begins the same day at the same facility that will hand the package to UPS or FedEx that evening. The entire chain is controlled in one location, which is what makes the overnight timeline reliable.


SuperRush: 50 Checks Next Morning

The SuperRush option is specifically designed for overnight check delivery needs. It is not a marketing claim. It is a specific production and shipping procedure: same-day print, same-day pack, overnight carrier handoff, next-morning delivery of the first 50 checks to your address.


MICR Pre-Verified on Every Rush Order

Even on rush production, every routing number is verified against the Federal Reserve E-Payments Routing Directory before printing begins. A rush order that ships with a wrong routing number helps no one. Pre-verification catches errors before production, not after.


Six Security Features at Base Price

Rush overnight check orders do not reduce security. Every check from Checkomatic, rush or standard, includes chemically sensitive paper, microprinting, void pantograph, UV fluorescent fibers, heat-sensitive ink, and pre-encoded MICR. No upgrade required.


All 50 States Including Alaska and Hawaii

Overnight delivery reaches all 50 US states. Alaska, Hawaii, and APO/FPO military addresses ship via USPS. If you are in a remote location, call to confirm transit times before counting on next-morning delivery.


Lost or Damaged Package Policy

If the carrier loses your overnight check package in transit, Checkomatic reprocesses and reshipsyour order at no charge. If your package arrives damaged, submit photos and Checkomatic reprocesses. This policy applies to rush and SuperRush orders.


Quick Summary: How to Order Checks Overnight

To order checks overnight and receive them the next morning: select SuperRush (+$54.95) on the Checkomatic product page, add the item to cart, select Next Day shipping at checkout, enter your business name, address, ABA routing number, account number, and starting check number, and submit before 3:00 PM Eastern Time Monday through Thursday. Approve the digital proof immediately after receiving it by email. Your 50 checks ship overnight via UPS or FedEx and arrive the next morning.

The remaining checks in your order follow via your selected shipping method. Rush orders placed after the cutoff begin production the next business day. For questions or time-critical situations, call 1-800-555-6374 during business hours. This guide covers all keywords related to ordering checks fast: order checks overnight, overnight checks, next day checks, order checks next day delivery,

rush check order, order checks fast delivery, order checks fast shipping, fast business checks, same day check processing, emergency checks, rush business checks, next day business checks, expedited check delivery, order checks online fast, business checks rush delivery, Checkomatic SuperRush, checks delivered tomorrow, payroll checks overnight, check reorder rush, order business checks fast, and cheap checks fast delivery from Checkomatic since 1997 in Monroe NY.

This guide also covers: how to get checks fast through rush check printing and SuperRush production, Checkomatic shipping options including free pickup in Monroe NY, personal checks fast delivery with the 3-business-day rush option, and how to order checks with fast shipping using Next Day air combined with SuperRush production.
 

Jul 28, 2026

How to Order Checks Overnight: Fast Delivery Guide for Businesses and Individuals

In This Guide:


Why Businesses Suddenly Need to Order Checks Overnight

Running out of checks at the wrong moment is more common than most business owners expect. The most frequent situations that drive someone to order checks overnight are not the result of carelessness. They are the result of check usage being irregular and hard to predict.

Payroll is the most critical trigger. When a payroll run is due and the check supply runs out the day before, the problem is immediate and has legal consequences in most US states. Late payroll carries financial penalties and employee relations risks that make an overnight check order well worth the cost.

Other common reasons to order checks fast include:

For more detail, see how to get business checks delivered fast.

  • A month-end accounts payable run that uses more checks than expected
  • A bank merger or routing number change that invalidated existing check stock
  • A new business account with no starter checks and an immediate vendor payment due
  • Lost or stolen check stock that needs to be replaced before a payment deadline
  • A printing error on the existing check batch that makes them unusable
  • A reorder that was placed too late and standard delivery will not arrive in time

Whatever the trigger, the solution is the same: an overnight check order that gets at least a working supply of checks to your door by the next morning. For business checks, Checkomatic's SuperRush option is designed exactly for this situation.


Checkomatic Rush and Overnight Delivery Options

Checkomatic offers two rush production upgrades for business checks, each designed for a different level of urgency. Both are available for business checks. Personal checks have a separate rush option.


Rush Production (+$29.95)

Rush production processes your order the same business day it is placed, as long as you order before 3:00 PM Eastern Time Monday through Thursday. After same-day production, your checks ship via the shipping method you selected at checkout. If you chose Ground shipping, your order ships same day but still takes transit time to arrive. If you chose Next Day shipping, your checks ship same day and arrive the next business day.

Rush production without Next Day shipping is useful when you need faster turnaround than standard but are not in an emergency that requires next-morning delivery.


SuperRush Production (+$54.95) , For Ordering Checks Overnight

SuperRush is the option to choose when you need to order checks overnight and have a working supply by the next morning. It works as follows:

  • Your order is processed the same business day (before the 3:00 PM EST cutoff)
  • The first 50 checks in your order are shipped overnight and delivered the next morning
  • The remaining checks in your order ship via the shipping method you selected at checkout

The result is that you have 50 functional, bank-compliant checks at your door by the next morning. For most urgent payroll or vendor payment situations, 50 checks are enough to cover the immediate need while the full order is in transit.


Personal Checks Rush (+$29.95)

Personal checks have a single rush option that ships the order within 3 business days. This is a production speed upgrade, not an overnight delivery option. If you need personal checks urgently for a business situation, consider whether business checks or QuickBooks checks might better serve your need, as those have the SuperRush overnight delivery option available.


Shipping Options for Rush Orders

Shipping MethodDelivery TimeCostBest For
PickupSame day (during business hours)FreeLocal customers near Monroe, NY
GroundStandard UPS/FedEx transitCalculated at checkoutNon-urgent orders, cost savings
2-Day2 business days after productionCalculated at checkoutModerate urgency, larger orders
Next Day1 business day after productionCalculated at checkoutCombined with SuperRush for next-morning delivery

For true overnight check delivery, the combination is: SuperRush production (+$54.95) + Next Day shipping. This gives you 50 checks at your door the morning after your order. The /shipping page has full pricing details at checkomatic.com/shipping.


The 3 PM EST Cutoff: What It Means and Why It Matters

To order checks overnight and receive them the next morning, your order must be placed before 3:00 PM Eastern Time on a Monday, Tuesday, Wednesday, or Thursday. This cutoff is not arbitrary. It represents the latest point at which production can begin the same day and the order can be handed off to UPS or FedEx in time to make that evening's overnight shipping pickup.

If you are on the West Coast and want to order checks overnight, noon Pacific is your window. This is a tighter deadline than most West Coast business owners expect when they first encounter it.


What Happens to Orders After the Cutoff

Orders placed after 3:00 PM EST are processed the next business day. This means if you place a SuperRush order at 4:00 PM on a Wednesday, production begins Thursday morning and the 50-check overnight delivery arrives Friday morning , not Thursday morning.

Orders placed on Friday after 3:00 PM, or on Saturday and Sunday, begin production Monday and overnight delivery arrives Tuesday morning. Checkomatic is closed Friday afternoons, Saturdays, and Sundays, and federal holidays are excluded from the rush processing schedule.


Proof Approval and the Cutoff

After placing your order, Checkomatic sends a digital proof showing exactly how your checks will print. You must approve this proof before production begins. If you place your order at 2:45 PM EST and do not approve the proof until 3:30 PM, the cutoff has passed and your order will not ship overnight.


All Four Shipping Methods Explained

Checkomatic uses UPS and FedEx for most US shipments. Orders to Alaska, Hawaii, and APO/FPO military addresses ship via USPS. Your shipping cost is calculated at checkout based on your order size and delivery address. Free shipping is available on orders of $150 or more using code FREE150PLUS at checkout.


Free Pickup (Monroe, NY)

If your business is near Monroe, New York, you can place a rush order and pick it up at Checkomatic's office at 308 Museum Village Road, Monroe, NY 10950 for free. Call ahead to confirm your order is ready before driving: 1-800-555-6374. Office hours are Monday through Thursday 9:30 AM to 5:30 PM EST and Friday 9:30 AM to 12:30 PM EST.


Ground Shipping

Standard UPS or FedEx Ground transit. Combined with Rush production, this is the most cost-effective option when you need faster production but are not in an overnight emergency. Transit time depends on your distance from Monroe, NY.


2-Day Shipping

Guaranteed delivery within 2 business days after production completes. Combined with Rush production (same-day processing), this means delivery in 3 business days total from your order date. A good middle ground between cost and urgency when you have 3 days but not 5.


Next Day Shipping

Delivery 1 business day after production. Combined with SuperRush (same-day production), this is the overnight check delivery combination. Your 50 initial checks arrive the next morning, and the remaining checks follow via your chosen shipping method.


Which Check Types Can Be Ordered Overnight

SuperRush overnight delivery is available for all Checkomatic business check types. The choice of check type does not affect your ability to get checks overnight. What matters is selecting the right format for your workflow before you order.


Computer Checks (Fastest to Print, Best for Overnight Orders)

Computer checks in all four formats are available with SuperRush: check on top (voucher), check in middle, check on bottom, and 3-on-a-page. These are the most commonly ordered business checks and the fastest to process because they require no hand-filling after delivery. You print from QuickBooks, Xero, Sage, or any compatible accounting software and the checks are ready to sign and mail.

Browse the full range at checkomatic/computer-checks.


QuickBooks Checks (Default Format for QB Users)

If you use QuickBooks Desktop or QuickBooks Online, the voucher check (check on top) is the default format your software is configured to print to. Order this format when you need to order QuickBooks checks overnight. Before placing your rush order, confirm your QuickBooks check style is set to Voucher at File, Printer Setup, Form Name: Check in QuickBooks Desktop, or at Settings, Print Checks, Print Setup in QuickBooks Online.

Browse QuickBooks-compatible checks at checkomatic/quickbooks-checks.


Manual Business Checks

Manual 3-on-page checks (accounts payable, payroll, and multi-purpose formats) are available with rush production. Manual checks are the right choice when you need a working check supply immediately and do not have a printer available or accounting software configured for check printing. They work with a pen and require no setup. Browse manual options at checkomatic.com/manual-checks.


Personal Checks

Personal checks have a rush option that ships within 3 business days. Overnight morning delivery (SuperRush) is not available for personal checks. If you need personal checks urgently, the 3-business-day rush is the fastest available option. Browse personal check options at checkomatic.com/personal-checks.


Step-by-Step: How to Order Checks Overnight at Checkomatic

  1. Confirm the time. Check the clock. It must be before 3:00 PM Eastern Time on a weekday (Monday through Thursday, excluding holidays). If you are in Pacific time, noon is your cutoff. If you have already missed today's cutoff, plan for tomorrow's order.
  2. Select your check type. Go to checkomatic.com/business-checks and select the check format you need. For QuickBooks users, check on top (voucher) is almost always correct. If you are unsure, check your accounting software's check style setting before ordering.
  3. Choose SuperRush before adding to cart. On the product page, select SuperRush (+$54.95) from the production option. This is the step that guarantees same-day processing and overnight delivery of your first 50 checks. If you skip this step and just select standard, your order will not ship overnight regardless of the shipping method you choose at checkout.
  4. Enter your check information carefully. Fill in your business name, mailing address, ABA routing number (from the bottom left of any existing check), checking account number, and starting check number. Verify every digit twice before proceeding. A wrong routing or account number requires a full reprint and a new rush fee, killing your overnight timeline.
  5. Add logo if needed (or skip for speed). Free black-and-white logo printing is included on every order. However, a new logo upload adds a review step that can slow approval. If speed is the priority and your logo is not on file, consider placing the rush order without a logo and adding it to your next regular order.
  6. Select Next Day shipping at checkout. This ensures the 50 SuperRush checks ship overnight for next-morning delivery. Ground or 2-Day shipping combined with SuperRush production still gives faster turnaround than standard, but only Next Day shipping at checkout delivers by the next morning.
  7. Provide a physical street address. Do not use a P.O. Box. UPS and FedEx overnight delivery services require a physical address. A staffed business address where someone can accept the delivery is best. If you are sending to a home address, confirm someone will be there to receive the package.
  8. Complete checkout and watch your email. After payment, Checkomatic sends a digital proof to your email. Open it immediately and review every field: business name, address, routing number, account number, starting check number, and logo. Approve it as fast as possible. The production clock starts when you approve the proof, not when you place the order.
  9. Track your order. After production and shipping, Checkomatic emails your UPS or FedEx tracking number. Use this to confirm the estimated delivery window and ensure someone is available to receive the overnight package at your address.


Address Rules for Overnight Check Delivery

The address you enter at checkout determines whether your overnight check delivery actually succeeds. Carrier rules for overnight services are stricter than for standard ground shipping, and any address issue that triggers a delivery exception wastes your rush fee and delays your checks.


Never Use a P.O. Box for Overnight Orders

UPS and FedEx cannot always deliver to P.O. Boxes. Tracked overnight services are frequently rejected or delayed at P.O. Box addresses because these carriers require a physical location for their delivery driver. Checkomatic specifically warns against using a P.O. Box for tracked orders. Use your business street address or a home street address where someone will be present.


Include Suite or Unit Numbers

If your business address has a suite number, include it every time. Missing suite numbers cause delivery exceptions on overnight packages because the driver cannot locate the specific unit in a multi-tenant building. Enter the suite number on the address line (e.g., 400 Main Street Suite 205, not 400 Main Street).


Use a Staffed Receiving Location

Overnight packages from UPS and FedEx require a signature or an attended delivery for high-value items. If your overnight check order arrives at an empty office or unattended location, the driver may leave a missed delivery notice and reattempt the next business day. This defeats the purpose of the overnight order. When possible, have someone at the delivery address the morning after your rush order.


What to Do If You Missed the Cutoff to Order Checks Overnight

If you realize you cannot meet today's 3 PM cutoff, the next step depends on how urgent your payment need is.


Option 1: Order Now for Next Available Overnight

Place your SuperRush order now, even after the cutoff. Production will begin the next business day morning, and the 50-check overnight delivery will arrive the following morning. This adds one day to your timeline but locks in the fastest possible delivery given the cutoff miss. Waiting until tomorrow to place the order adds another day unnecessarily.


Option 2: Call Checkomatic Directly

For time-critical situations, call 1-800-555-6374 during business hours (Monday through Thursday 9:30 AM to 5:30 PM EST, Friday 9:30 AM to 12:30 PM EST) and explain your situation. The team can advise on whether there is any flexibility in the current production window and confirm the fastest available timeline for your specific order.


Option 3: Pick Up at Monroe, NY

If you are near Monroe, New York and can physically pick up your order, same-day pickup may be available for rush production orders placed early enough in the business day. Call ahead before driving: 1-800-555-6374. The office address is 308 Museum Village Road, Monroe, NY 10950.


Bridge Payment Options While Waiting for Checks

If your check order is in transit and you need to make a payment before it arrives, these bridge options cover the gap without missing a payment deadline.


ACH Bank Transfer

ACH (Automated Clearing House) transfers are same-day or next-business-day electronic payments sent directly between bank accounts. Most US banks offer ACH through online banking at no cost or low cost. For vendor payments where the vendor has bank account information on file, ACH is often the fastest bridge option when you are waiting to order checks fast and cannot wait for delivery.


Wire Transfer

Wire transfers are immediate same-day payments, typically processed within a few hours of submission. Wire fees range from $15 to $35 per transfer depending on your bank. For large urgent vendor payments or contractor payments, a wire is the fastest bridge option while your check order is in production.


Request a Brief Payment Extension

Most vendors and contractors are understanding when a business contacts them in advance to explain a 1 to 2 day payment delay due to a check supply issue. A brief professional message explaining the situation and providing a confirmed delivery timeline for the check is usually sufficient to avoid late payment consequences. Contact your vendor proactively rather than letting the payment date pass without communication.


Payroll-Specific Options

For payroll emergencies, temporary direct deposit or ACH payroll runs are the fastest bridge. Most payroll software including QuickBooks Payroll, Gusto, and ADP can run an emergency direct deposit payroll if you have employees' bank account information on file. If you run payroll by check because employees do not have bank accounts, contact your bank about emergency cash options for the affected employees while the checks are in transit. For complete payroll check options, see our business checks for payroll guide.


How to Avoid Running Out of Checks and Needing Overnight Delivery

The best way to avoid ever needing to order checks overnight in an emergency is to reorder before running low. The practical rule for most businesses is to reorder checks when you have approximately 25 checks remaining. At typical business volumes of 3 to 5 checks per day, 25 checks gives you 5 to 8 days of supply. Standard production and shipping takes 3 to 5 business days, so a 25-check reorder trigger gives you a comfortable buffer without ever needing to pay rush fees.

For businesses running payroll, the reorder trigger should be based on payroll needs, not just daily usage. Always keep at least one full payroll run worth of checks in supply before placing a reorder. If your monthly payroll requires 30 checks, your reorder trigger is 35 checks remaining, not 25.

Setting a physical reminder on your check storage (a paper note on the bottom of the stack that says "Reorder now") prevents the surprise of reaching for a check and finding nothing. A calendar reminder set 2 weeks after each order arrives keeps the reorder timeline proactive rather than reactive.


Ordering Checks Overnight From Checkomatic vs Your Bank

When businesses need to order checks overnight urgently, the instinct is often to call their bank. Here is how bank-issued checks compare to ordering directly from Checkomatic for urgent needs.

FactorCheckomaticBank-Issued Checks
Standard production time3 to 5 business days7 to 14 business days
Overnight delivery available?Yes (SuperRush, 50 checks next morning)Rarely , most banks cannot rush individual check orders
Rush fee+$54.95 SuperRushBanks typically do not offer rush printing at any price
Pricing per check50 to 70% lower than bank retail$30 to $50 per 100 checks standard
Security features6 CPSA-certified features at base priceBasic security, often a tier upgrade for full protection
QuickBooks compatibilityAll formats, pre-verified alignmentCompatible but alignment may require adjustment
Ordering processOnline, 5 minutesOften requires a branch visit or phone call
Free logo printingYes, on every orderUsually an additional fee or not available

For most urgent check needs, ordering directly from Checkomatic is both faster and cheaper than going through a bank. Banks batch check printing orders through third-party vendors and do not offer rush individual orders. Checkomatic manufactures all checks in-house at Monroe, NY, which is what makes same-day production and overnight delivery possible.


Why Choose Checkomatic for Rush and Overnight Check Orders

In-House Manufacturing in Monroe, NY Since 1997

All checks are manufactured at Checkomatic's own facility. No third-party print vendors. When you place a SuperRush order before 3 PM, production begins the same day at the same facility that will hand the package to UPS or FedEx that evening. The entire chain is controlled in one location, which is what makes the overnight timeline reliable.


SuperRush: 50 Checks Next Morning

The SuperRush option is specifically designed for overnight check delivery needs. It is not a marketing claim. It is a specific production and shipping procedure: same-day print, same-day pack, overnight carrier handoff, next-morning delivery of the first 50 checks to your address.


MICR Pre-Verified on Every Rush Order

Even on rush production, every routing number is verified against the Federal Reserve E-Payments Routing Directory before printing begins. A rush order that ships with a wrong routing number helps no one. Pre-verification catches errors before production, not after.


Six Security Features at Base Price

Rush overnight check orders do not reduce security. Every check from Checkomatic, rush or standard, includes chemically sensitive paper, microprinting, void pantograph, UV fluorescent fibers, heat-sensitive ink, and pre-encoded MICR. No upgrade required.


All 50 States Including Alaska and Hawaii

Overnight delivery reaches all 50 US states. Alaska, Hawaii, and APO/FPO military addresses ship via USPS. If you are in a remote location, call to confirm transit times before counting on next-morning delivery.


Lost or Damaged Package Policy

If the carrier loses your overnight check package in transit, Checkomatic reprocesses and reshipsyour order at no charge. If your package arrives damaged, submit photos and Checkomatic reprocesses. This policy applies to rush and SuperRush orders.


Quick Summary: How to Order Checks Overnight

To order checks overnight and receive them the next morning: select SuperRush (+$54.95) on the Checkomatic product page, add the item to cart, select Next Day shipping at checkout, enter your business name, address, ABA routing number, account number, and starting check number, and submit before 3:00 PM Eastern Time Monday through Thursday. Approve the digital proof immediately after receiving it by email. Your 50 checks ship overnight via UPS or FedEx and arrive the next morning.

The remaining checks in your order follow via your selected shipping method. Rush orders placed after the cutoff begin production the next business day. For questions or time-critical situations, call 1-800-555-6374 during business hours. This guide covers all keywords related to ordering checks fast: order checks overnight, overnight checks, next day checks, order checks next day delivery,

rush check order, order checks fast delivery, order checks fast shipping, fast business checks, same day check processing, emergency checks, rush business checks, next day business checks, expedited check delivery, order checks online fast, business checks rush delivery, Checkomatic SuperRush, checks delivered tomorrow, payroll checks overnight, check reorder rush, order business checks fast, and cheap checks fast delivery from Checkomatic since 1997 in Monroe NY.

This guide also covers: how to get checks fast through rush check printing and SuperRush production, Checkomatic shipping options including free pickup in Monroe NY, personal checks fast delivery with the 3-business-day rush option, and how to order checks with fast shipping using Next Day air combined with SuperRush production.
 

Jul 27, 2026

Checks With Multiple Signatures: Complete Guide

What a Dual Signature Check Is

Dual signature check definition: a dual signature account uses a dual signature check: a check printed with two signature lines on the face, indicating that two authorized individuals must sign the check before it is treated as a complete and authorized payment instrument within the organization. The first line is the primary signer's signature; the second line belongs to the secondary approver.

The two-signature check policy: a dual signature requirement is a check with multiple signatures at the drawer (issuing) side, not the payee (endorsing) side. This is an important distinction. The drawer's multiple signature requirement governs who can authorize a payment from the checking account. Payee endorsement requirements govern who can receive and deposit the check once issued. Both create "multiple signature" scenarios, but they operate under different legal rules and serve different purposes.

Dual signature checks are used primarily by businesses, nonprofits, churches, homeowners associations, and other organizations that want a second layer of authorization on outgoing payments. A single signer could theoretically write unauthorized checks to themselves or outside parties; requiring a second independent signature closes that internal control gap.


Two Separate Multiple Signature Scenarios

Most confusion about checks with multiple signatures comes from mixing up two legally distinct scenarios that happen to share a name. They work differently, they are governed by different UCC sections, and they require different responses from the account holder, bank, and recipient.


Scenario A: Dual Signature at the Drawer Side (Two Signers Authorizing a Payment)

This is the business internal control scenario. The account has one checking account and one MICR line. Two people must sign the check before it is sent to a payee. The signature line on check face: two signature lines printed. The bank clears the check from the single account regardless of how many signatures appear on it (more on this below). The dual signature requirement is a check that requires two authorized drawers to sign, governing who can authorize a payment out of the account.


Scenario B: Check Made Payable to Two Named Payees (Two Names in the "Pay to the Order of" Line)

This is the check payable to two people endorsement scenario. The check is made out to two people, for example "John Smith and Jane Doe." The question is which of them must endorse the check to deposit it. The answer depends on the conjunction used between the names and is governed by the UCC 3-110 payee and or rule (UCC Section 3-110(d)). This scenario has nothing to do with who wrote the check or how many signers the account requires; it concerns who can receive the payment.

Both scenarios involve "checks with multiple signatures," but they operate under completely different legal frameworks and have different practical implications. This guide covers both in detail.


What Banks Actually Verify in Automated Processing

This is the most important fact about dual signature checks that most guides either omit or understate: modern bank automated processing dual signature checks: banks do not manually examine signatures on most checks. Check processing became automated beginning in the 1980s and is now nearly entirely electronic. When a check clears, the bank's systems read the MICR line (routing number, account number, check number), verify the amount matches what was encoded, confirm the account has sufficient funds, and process the transaction.

The bank's automated check processing system does not count the number of signatures on the face. It does not compare signatures against the account signature card. It does not verify that a dual signature requirement was satisfied. A check with two signature lines and only one signature runs through automated processing identically to a fully signed check.

The UCC explicitly acknowledges this reality. UCC Section 4-406 and related provisions recognize that automated processing is the industry-wide standard, and that "ordinary care" and "reasonable commercial practices" for banks processing checks by automated means do not require manual examination of individual checks. Bank liability dual signature issue: a bank that pays a dual-signature check with only one signature because its automated system did not examine the number of signatures is generally not liable for negligence under this standard.

According to a Virginia Bankers Association legal analysis, a bank processing a check through automated systems "likely will not be liable to the customer for negligence for failure to exercise ordinary care or reasonable commercial practices" when it honors a dual-signature check with only one signature. This is the operational reality every business relying on dual signature checks must understand.


UCC Liability When a Bank Pays a One-Signature Check

While the bank is not necessarily negligent for missing the second signature in automated processing, a different UCC provision does create potential liability. The UCC provides that the properly payable check standard: a bank may only charge the customer's account for checks that are "properly payable," meaning they are authorized by the customer. Under the unauthorized signature UCC rule (UCC Section 3-403), if the authorized signature of an organization requires more than one person's signature, a check signed by only one of the required signers has an "unauthorized signature" and is not "properly payable."

This creates a legal gap. The bank is not negligent for failing to manually examine the signatures, but if the dual signature requirement is formally part of the account agreement and the check was paid with only one signature, the bank technically paid an improperly payable item. In that case, the bank may be obligated to re-credit the account, even though it did nothing procedurally wrong in its automated processing.

The practical resolution most banks have adopted is one of two account structures. The first is a true dual-signature account where the account contract makes two signatures a condition of proper payment, and the bank accepts the obligation to examine signatures manually or through positive pay controls. This is rare and typically available only at smaller community banks or credit unions that still process some checks manually. The second is an account where the contract explicitly states that payment is authorized by a single signature, but the check face has two lines to accommodate the customer's internal dual-authorization process. Under this second structure, a one-signature check is properly payable, and the bank has no UCC liability for processing it. The dual signature becomes entirely the customer's internal responsibility to enforce.


Making Dual Signature Requirements Bank-Enforceable

UCC 4-103 freedom of contract (UCC Section 4-103(a)), the freedom-of-contract provision, allows banks and customers to vary the effect of the UCC's default rules by written agreement, as long as the agreement does not limit the bank's duty of good faith or ordinary care. This is the legal foundation for making a dual signature requirement truly enforceable at the bank level.

To make the dual signature requirement bank-enforceable, the account agreement must specifically state that payment of a check signed by fewer than the required number of authorized signers is not authorized and is not properly payable. With this agreement in place, a bank that honors a single-signature check when two are required has paid an improperly payable item and must re-credit the account.

Getting a bank to agree to this specific contract language is less common than it used to be, because automated processing makes manual signature verification expensive and operationally difficult for most banks. Some banks charge a fee for this service. Others decline to offer it at all and instead offer positive pay as a substitute: the customer submits a file of issued checks, and any check not on the file is flagged for human review regardless of the number of signatures.

For most businesses, the practical recommendation from accounting professionals and bank advisors is: implement the dual signature requirement as an internal control, pair it with positive pay, and reconcile bank statements monthly to catch any unauthorized single-signature checks that cleared. For organizations handling very large transactions where the dual signature must be a legal obligation on the bank, consult with your bank directly about whether they offer a contractual dual-signature account structure.


UCC 3-110(d): The "And" vs "Or" Payee Rule

Scenario B above (the check payable to two people) uses the "and" vs "or" check payee rule governed by UCC Section 3-110(d), which establishes a clear rule based on the exact conjunction between payee names.


Check Made Payable With "AND"

If a check reads "A joint payee check reads: "Pay to the Order of John Smith AND Jane Doe" (or uses an ampersand instead of the word "and"). The instrument is payable to both of them together. Under UCC 3-110(d), a check payable to two or more persons "not alternatively" can only be negotiated, discharged, or enforced by all of them together. Both payees must physically endorse the back of the check before any bank will deposit or cash it. Neither person can act alone, regardless of how inconvenient that is in practice.

If a bank accepts a check written with "and" between the payee names with only one signature, it faces conversion liability to the payee who did not endorse. Under UCC Section 3-420, the bank that paid a check with a missing required endorsement is liable to the payee who did not sign, because the bank accepted the check without proper authority to negotiate it on that person's behalf.


Check Made Payable With "OR"

If a check reads "Pay to the Order of John Smith OR Jane Doe" (or uses a slash between the names, or lists the names with no conjunction at all), the instrument is payable alternatively. Under UCC 3-110(d), either payee, acting alone, has full authority to endorse, deposit, or cash the check. The other payee does not need to be present, does not need to sign, and does not even need to know the check has been cashed.

The Oklahoma Bankers Association legal brief (cited in both the June 2024 and June 2025 OBA Legal Briefs) confirms this analysis: "If there is an 'and/or,' '/,' or no conjunction between the names, any payee may indorse or deposit the check." This interpretation is consistent across states that have adopted the UCC.


Ambiguous Cases

If the check wording is ambiguous about whether the payees are named jointly or alternatively, UCC 3-110(d) resolves the ambiguity in favor of the alternative reading: either person can endorse. Courts and banks will not require both signatures when the intent is unclear from the face of the check. This puts the burden on the check writer to be precise with the conjunction if joint endorsement is required.


Joint Account Checks and Multiple Names

Joint account check writing: a joint checking account is held by two or more people authorized to draw checks from the account. This is different from a dual signature requirement. In a typical joint account, either account holder can write a check unilaterally. There is no two-signature rule at the account level unless one is specifically established in the account agreement.

Joint accounts used by married couples, domestic partners, and co-owners of a business typically allow either party to sign checks alone. The account is jointly owned, but signatures are not required from all owners for each transaction. This is the default structure for most joint personal checking accounts at US banks.

A joint account check written by one account holder to an outside payee requires only the one authorized signature from the account holder. It has nothing to do with the payee endorsement rule. Separately, if that check is made payable to two named people using "and," both payees must endorse it when they receive it, regardless of who wrote it.

For personal joint account checks, Checkomatic's standard personal checkbooks print both account holders' names on the check face when both names are included in the order. Both names appear in the printed name block; either authorized signer can sign in the signature line.


The Dollar-Amount Threshold Approach

The most common real-world implementation of dual signature requirements uses a dollar threshold: one signature is sufficient for checks below a defined amount, but checks above that amount require two signatures. This threshold approach balances operational efficiency against fraud control.

Common threshold amounts in business practice include $2,500, $5,000, $10,000, and $25,000. A business might allow any authorized employee to write checks up to $5,000 with a single signature, but require the owner or CFO to co-sign any check above that amount. This structure allows routine small payments to move efficiently while flagging large disbursements for a second set of eyes.

The threshold approach is typically implemented in accounting software as well as on the physical check stock. In accounting software, the system can be configured to require a second digital signature approval for payments above the threshold amount before a check is issued. On the physical check, the second signature line is always present on the face but may be left blank on small-value checks.

The dual signature threshold should be set based on the organization's risk tolerance and the practical availability of the second signer. A threshold so high that it is never triggered provides no real control. A threshold so low that it creates friction on routine payments reduces efficiency without proportionate benefit.


How to Set Up Dual Signature Checks for Your Business

Business dual signature setup involves three components for a dual signature check requirement: the check stock, the account agreement, and the internal process.


Step 1: Order Checks With Two Signature Lines

Order business checks that have two signature lines printed on the face. Checkomatic's manual business check formats can accommodate a second signature line in the signature block area. For computer checks printed through accounting software, the software typically prints the signature area and can print a first digital signature and leave a blank line for the second handwritten signature.


Step 2: Update the Account Agreement

Notify your bank in writing that your account requires two authorized signatures for checks above a defined amount (or on all checks). Ask your bank whether they offer a formal dual-signature account structure under UCC 4-103. If they do, get the requirement documented in the account agreement. If they do not offer formal dual-signature enforcement, at minimum document the internal policy in your organization's bylaws, resolutions, or financial procedures manual.


Step 3: Establish the Internal Process

Define who the authorized signers are. Document the authority levels and thresholds in a board resolution, operating agreement, or financial policy. Train the people who handle checks on the requirement. Establish a verification step: the person who mails checks verifies both signatures before mailing, and the person reconciling the bank statement reviews cleared check images to confirm both signatures were present on dual-signature checks.


Step 4: Pair With Positive Pay

Positive pay, offered by most business banks, requires the company to submit an electronic file of all authorized checks (check number, amount, date, payee) before they are presented for payment. Any check not on the file is flagged for human review before clearing. Positive pay does not verify signature count, but it does catch unauthorized checks written by internal or external fraudsters using your account number. It is the complementary control that compensates for the bank's inability to verify dual signatures in automated processing.


Which Check Formats Support Two Signature Lines

Not all check formats have a second signature line by default. Here is how each format handles the dual signature requirement.


Manual Business Checks

Manual business checks in 3-on-a-page format are the most natural format for dual signature requirements. Because the check is filled out by hand, the signer writes their signature in the designated signature area. A second signature line can be pre-printed on the check face, and the co-signer signs in that second line before the check is released. Checkomatic's manual accounts payable checks, manual payroll checks, and multi-purpose manual checks can include a second signature line in the signature block. When ordering, specify that you need a dual signature line printed on the face.


Computer Business Checks (Voucher Format)

Computer business checks printed through accounting software typically have a single signature line by default. The software prints a first digital signature (if one has been uploaded) or leaves the signature area blank for handwriting. A second line for handwriting or a second digital signature can be added through the software's check template configuration. For QuickBooks, some third-party check template providers offer dual-line layouts. Checkomatic's check on top business checks and other computer check formats can be discussed for second-line printing by contacting Checkomatic's production team.


Personal Checks

Standard personal checks have one signature line. For a joint personal account where you want to require both account holders to sign (which is unusual in personal banking), you would need to custom-order check stock with two signature lines and formally establish the dual-signature requirement with your bank. Most individuals with joint accounts rely on the convention that either signer may sign rather than requiring both for routine personal payments.


Compact Deskbook and Pocket Checks

Checkomatic's compact executive deskbook checks and manual pocket checks have smaller physical dimensions and less space in the signature area. A second signature line is feasible but the space constraints are tighter than the standard 3-on-a-page format.


Dual Signature in QuickBooks and Accounting Software

Accounting software handles dual signature requirements in two ways: digital signature check printing and workflow approval.


Digital Signature Printing in QuickBooks

Dual signature QuickBooks setup: QuickBooks allows one or two signature images to be uploaded and printed on checks. In QuickBooks Desktop, go to File, then Printer Setup, then select Check in the Form Name dropdown. Upload the first signature image and set the dollar amount above which it prints. For a second signature, upload the second signature image to the same account, configure it to print for amounts above the threshold, and set both to appear on the check printout.

Sage Intacct's check printing module has an explicit dual-signature configuration: you upload both signature images and set an "amount requiring 2nd signature" threshold. Checks above that threshold print with both signatures; checks below it print with only the first.


Approval Workflow as the Second Signature

Many businesses use the accounting software's approval workflow rather than a second physical signature as the dual-authorization step. In this model, one person creates and approves a payment, a second person approves it in the software before the check is printed, and only the first person's physical signature is needed on the printed check because the second person's approval was captured electronically in the workflow log. This approach is common with ERP systems and larger accounting platforms. Whether the workflow approval satisfies a "two signature requirement" under UCC 4-103 depends on the specific language of the account agreement.


Dual Signature as an Internal Fraud Control

Even knowing that banks generally do not enforce dual signature requirements through automated processing, the internal control dual signature check remains a valuable fraud control for organizations. The reason is that most check fraud committed against small businesses is internal: an employee with access to the checkbook and authorization to sign writes checks to themselves, a related party, or a fictitious vendor.

A dual signature requirement catches this type of fraud at the point of issuance. If writing a check above $5,000 requires the owner's signature alongside the bookkeeper's signature, the bookkeeper cannot write a fraudulent check to themselves without either forging the owner's signature (which is criminal and visually detectable when the canceled check image is reviewed) or obtaining the owner's co-signature (which requires presenting the fraudulent check for review).

The dual signature makes internal check fraud significantly harder to execute without discovery. It does not require the bank to enforce it to be effective. The internal process and the after-the-fact review of canceled check images is where the control actually works. As the OTC Certified Public Accountants guidance puts it: "Continue to require dual signatures but know that it is your responsibility to verify that the internal control steps you have in place are working."

For a complete guide to check fraud prevention including check washing, counterfeiting, and internal fraud controls, see our check fraud prevention guide and our check validity and fraud prevention guide.


Why the MICR Line Is Unchanged by Signature Requirements

One practical question that comes up when businesses set up dual signature checks is whether the MICR line or any other printed check element changes when a dual signature requirement is in place. The answer is no. The MICR line multiple signature question: the MICR line at the bottom of every check carries only four pieces of information: the bank's routing number, the account number, the check number, and (when the check is processed) the encoded amount. None of these change based on how many signatures the account requires.

A dual signature business check ordered from Checkomatic has the identical MICR line as a single-signature check for the same account. The routing number is the ABA routing number for the issuing bank. The account number is the account number assigned to the checking account. The check number increments sequentially. Nothing in the MICR encoding identifies the check as a dual-signature instrument.

This is why the bank's automated processing cannot distinguish a dual-signature check from a single-signature check. The MICR line is the language of automated check processing. The signature requirement is written in the account agreement and on the face of the check in human-readable form, but neither of those elements is in the machine-readable MICR data that drives processing.

For a full explanation of how the MICR line works and what each section means, see our ABA routing numbers guide. For a complete check anatomy guide covering every field on a check, see our check types and terminology guide.


Ordering Dual Signature Checks From Checkomatic

Checkomatic has manufactured personal and business checks in Monroe, NY since 1997. As an in-house check manufacturer, Checkomatic produces every order at the Monroe NY facility with direct control over the printing and paper specifications. Every check ships on ABA-compliant (ABA compliant check) security paper with six fraud deterrent features at base price.


Manual Business Checks for Dual Signature Use

Checkomatic's manual business check range is the most natural fit for dual signature check operations. All three main manual formats are available as refill orders:


Computer Business Checks

For businesses that print checks through accounting software and want a second handwritten signature line on the face, Checkomatic's computer format checks can be ordered with a second signature line in the printed signature block area. The software prints the first digital signature (or leaves both blank for handwriting); the second signer writes their signature on the physical line after printing:


Free Logo Printing and Standard Turnaround

Free black and white logo printing is included on every business check order. Color logo printing is available for a small per-order charge. Standard turnaround is 3 to 5 business days from digital proof approval. A digital proof showing the full check layout including the signature line area is generated before production begins, giving you the opportunity to confirm the placement of the second signature line before any check stock is printed.

Start your dual signature check order at checkomatic.com. For business check formats and accessories, visit business checks. For manual check formats specifically, see manual business checks. For matching binders for manual check storage, see 7-ring check binders.


The Short Version on Checks With Multiple Signatures

A dual signature check has two signature lines and requires two authorized signers. As an internal business control it is effective; as a bank-enforced requirement it requires specific contract language under UCC 4-103. Modern automated check processing does not verify signature count: a bank that processes a dual-signature check with one signature is generally not negligent under the UCC's ordinary care standard, though it may have paid an improperly payable item if the dual signature is contractually required.

Checks made payable to two named people follow UCC 3-110(d): "John AND Jane" requires both endorsements; "John OR Jane" allows either to sign alone. Joint accounts allow either authorized account holder to sign checks without requiring the other's signature, by default.

The most effective dual signature implementation pairs two-line check stock with positive pay at the bank level and monthly verification of canceled check images. Checkomatic's manual business check formats are the most practical format for dual signature operations because both signatures are applied by hand and can be visually verified before mailing.


Frequently Asked Questions


What is a dual signature check?

Dual signature check definition: a dual signature check is a business or personal check that has two signature lines printed on the face, requiring two authorized individuals to sign before the check is treated as a complete and authorized payment. The business check signature requirement for dual signatures is almost always an internal organizational control rather than a legal requirement enforced by the bank. It works because both signers inside the organization know the requirement exists and can enforce it before the check is mailed. Modern automated bank processing does not verify signature count. The dual signature check is most common in businesses, nonprofits, and organizations managing shared finances with internal authorization thresholds.


Do banks actually verify that two signatures are on a check?

In the vast majority of cases, no. Modern automated check processing clears checks based on the MICR line data (routing number, account number, check number, amount). Banks do not manually examine whether one or two signatures are present on the check face. The UCC acknowledges automated processing as the industry standard and does not require banks to manually verify signatures as part of ordinary care. A bank that processes a dual-signature check with only one signature through automated systems is generally not liable for negligence. The dual signature requirement functions as an internal company control, not a bank-enforced rule, unless the account agreement specifically makes dual signatures a condition of proper payment under UCC 4-103.


What happens when a check is made out to two people?

Under UCC Section 3-110(d), the answer depends on the exact wording. If the check reads "John Smith AND Jane Doe" or uses an ampersand, both payees must endorse the check before it can be deposited or cashed. Neither can act alone. If the check reads "John Smith OR Jane Doe," uses a slash between names, or uses no conjunction at all, either payee can endorse and cash the check independently. If a bank accepts a check made payable with "and" between two names when only one person endorses it, the bank faces conversion liability to the payee who did not sign under UCC 3-420.


How do I set up a dual signature requirement for my business checks?

Setting up a dual signature requirement for business checks involves three steps. First, order business checks with two signature lines printed on the face. Checkomatic's manual business check formats can include a second signature line. Second, notify your bank in writing about the dual signature requirement. Ask whether they offer a formal dual-signature account under UCC 4-103, which makes the requirement a contractual condition of proper payment and banking-level enforcement. Third, establish an internal process: define authorized signers, set dollar thresholds if applicable, and verify both signatures on every applicable check before mailing. Pair with positive pay for strongest fraud protection.


What check formats work best for dual signature requirements?

Manual business checks are the most practical format for dual signature requirements because both signers physically apply their signatures by hand at the time of writing, and both can inspect the payment before signing. Checkomatic's manual accounts payable, payroll, and multi-purpose checks in the 3-on-a-page format can include a second signature line. Computer business checks can also carry a second signature line, either a printed blank line for handwriting or a second digital signature uploaded and configured in accounting software. Personal checks typically have one signature line; dual-signature personal checking is unusual and requires custom check stock and a formal account agreement with the bank.

Jul 24, 2026

Safe and Security Checks: Features, Fraud Stats, Guide

What Security Checks Are

Security check definition: a security check is a personal or business check printed on ABA-compliant security paper with one or more fraud deterrent features incorporated into the paper itself, the printing process, or both. The ABA (American Bankers Association) standard for check paper, in coordination with ANSI X9 standards, establishes the minimum requirements for checks to be processed through the US banking system.

When most people say "security checks" or "safe checks," they mean checks that go beyond the minimum ABA processing requirements by incorporating additional features specifically designed to make check fraud harder to carry out successfully. These enhanced security features address the specific fraud methods criminals use: chemical washing, photocopying, scanning and digital reprinting, and forgery.

The term "high security checks" is sometimes used to distinguish checks with more features from checks with fewer features. In practice, the meaningful distinction is between checks on plain or minimally-featured paper (which many banks issue and which office supply stores stock) and checks on full ABA-compliant security paper with the complete set of fraud deterrent features. Checkomatic's checks fall into the latter category across every format, personal and business, at the base price.

Security checks are not specialty products you need to request separately. They are simply the standard that responsible check manufacturers use for all their check paper. The question for buyers is whether the manufacturer they choose uses full ABA-compliant security paper or a lower-grade stock.


Check Fraud Statistics: How Bad Is the Problem

The data on check fraud is striking in two directions: the problem is larger than most people assume, and it has proven persistently resistant to declining despite the growth of electronic payment alternatives.

Check fraud statistics 2025: the 2025 AFP Payments Fraud and Control Survey found that 63 percent of organizations experienced attempted or actual check fraud in 2024, making checks the payment method most frequently subjected to fraud among all payment types. This figure represents a slight decline from 65 percent in 2023 and 77 percent in 2014, but the level has remained between 63 and 66 percent consistently since 2020, according to OrboGraph's analysis of the AFP data. The 2026 AFP survey (covering 2025 activity) reported 58 percent of organizations experienced check fraud, still the highest rate among all payment methods.

Despite this persistent fraud rate, the same 2025 AFP survey found that 91 percent of organizations still use checks and more than 75 percent have no immediate plans to stop. The Federal Reserve Financial Services summary of the same survey noted that checks remain "a favored payment method" even among organizations fully aware of the risk. The AFP's conclusion: "This view is clearly false after reviewing the data collected in the annual report since 2015" that checks are safer than digital payments.

The practical implication is that checks are not going away, and the businesses and individuals that continue using them need the strongest available paper-level protection on every check they issue. An organization writing 200 checks per month with 63 percent industry check fraud exposure has a meaningful statistical reason to ensure every one of those checks is on full ABA-compliant security stock.


The Main Types of Check Fraud Security Checks Address

Security check paper features are specifically designed to address distinct fraud methods. Understanding check fraud types and which feature addresses each attack type explains why each feature matters and why the complete six-feature set is stronger than any subset.


Check Washing (Alteration Fraud)

Check washing uses chemical solvents to dissolve the ink on a legitimate check without damaging the paper, allowing the fraudster to rewrite the payee name and dollar amount. Check washing prevention is the goal: the stolen check typically retains the original signature, making it appear authentic after alteration. Washing solvents include common products available at retail stores. The chemically reactive check paper feature directly addresses this attack type.


Photocopying and Scanning

Fraudsters use high-quality copiers or scanners to reproduce legitimate checks, then present the reproductions as payments. Modern photocopiers produce copies of sufficient quality to pass initial visual inspection. Microprinting and void pantograph features directly address this attack: the microprint line blurs in any copy, and the pantograph reveals VOID text when scanned or copied.


Digital Counterfeiting

The fastest-growing check fraud method, as documented by OrboGraph and JPMorgan Chase's fraud research teams, involves scanning a stolen check, extracting the routing number, account number, and signature digitally, then using desktop publishing software to print new checks for any amount in unlimited quantity. The fraudster never alters the original check. They create entirely new checks from the extracted data. The genuine foundry watermark, void pantograph, and UV fluorescent fiber features address this attack: none of these can be reproduced by a standard printer on plain paper.


Check Alteration (Non-Washing)

Check alteration prevention: some check alteration fraud is done mechanically or with correction fluid rather than chemical washing. The chemically reactive paper and void pantograph both detect physical alteration attempts. The thermochromic ink zone provides an authentication point a bank teller can verify instantly, distinguishing an unaltered original from an altered document.


Forged Endorsement

A forged endorsement fraud occurs when a check payable to one party is endorsed by an unauthorized person and deposited. Security paper features on the face of the check do not directly prevent this; endorsement-side fraud is addressed by restrictive endorsement stamps ("For Deposit Only"), positive pay with payee name verification, and prompt account monitoring.


The 6 ABA Security Features and What Each One Prevents

Checkomatic includes all six standard ABA compliant check security features on every check, personal and business, at the base price. Here is what each feature does and which fraud type it directly addresses.


Feature 1: Chemically Reactive Paper

Chemically reactive paper contains agents distributed through the paper stock that react permanently when contacted by the chemical solvents used in check washing. When bleach, acetone, acetone-based products, or alcohol-based solvents are applied, the paper produces a permanent stain or discoloration pattern that cannot be removed, masked, or reversed. This stain is visible to a bank teller conducting a visual inspection and is detectable in automated check image processing systems that flag discoloration anomalies.

Chemically reactive paper does not prevent a determined criminal from attempting a wash, but it makes the attempt immediately and permanently visible. Any washed check presented for payment or deposit reveals its own tampering through the stain pattern. This feature directly addresses the check washing fraud type.


Feature 2: Genuine Foundry Watermark

A check watermark genuine foundry watermark is embedded into the paper fiber during manufacturing, not applied to the surface. It is visible when the check is held to a light source and appears as a lighter or darker pattern (typically words or a logo design) in the paper itself. Because the watermark is a structural property of the paper fiber, it cannot be reproduced by printing, photocopying, or scanning.

A counterfeit check printed on plain paper, regardless of how high-quality the printer or how detailed the design, will not have a genuine watermark. A bank teller who holds the check to light and sees no watermark in a check that claims to be from a manufacturer using watermarked stock has immediate, reliable evidence of counterfeiting. The genuine foundry watermark directly addresses digital counterfeiting and photocopying.


Feature 3: Microprinting

Check microprinting is text printed at a scale too small to read with the naked eye, typically along the signature line or other borders of the check. At normal viewing distance and to the unaided eye, it appears as a solid or dotted line. Under magnification (a loupe or magnifying glass), the text becomes readable. This text is usually a repeating phrase such as "ORIGINAL DOCUMENT" or the name of the check manufacturer.

Photocopiers, scanners, and standard printers cannot accurately reproduce text at the scale of microprinting. Any reproduction shows the microprint line as a blurred, indistinct smear rather than readable text. A bank teller checking authenticity can use a loupe to verify the microprint is legible on a presented check. Microprinting directly addresses photocopying and scanning-based counterfeiting.


Feature 4: Thermochromic (Heat-Sensitive) Ink

An area of the check face, typically a colored shape or text block, is printed with thermochromic ink check that disappears when warmth is applied and returns when cooled. A bank teller authenticating a check rubs the thermochromic zone with their thumb; on a genuine check printed with this ink, the zone disappears under the friction heat and reappears when the check cools. On a counterfeit check printed on standard paper with standard ink, no thermochromic reaction occurs.

This is an active authentication feature that a teller can verify in seconds without any equipment. It directly addresses counterfeiting and provides an authentication step that does not require UV lights or specialized equipment.


Feature 5: Void Pantograph

A void pantograph check feature is a background pattern printed on the check that is invisible or nearly invisible to the eye under normal viewing but produces visible VOID text across the check when photocopied, scanned, or digitally imaged. The pattern exploits the difference in how the human eye and image sensors respond to specific dot patterns, densities, and colors.

The void pantograph addresses two fraud scenarios directly. When a criminal photocopies a check to create a reproduction, the VOID pattern appears on the copy, making it immediately identifiable as a reproduction. When a criminal scans a check to extract data for digital counterfeiting, the scanned image shows VOID across the background, and any check printed from this image carries the VOID pattern. This is one of the most important features for the digital counterfeiting threat that now dominates check fraud.


Feature 6: UV Fluorescent Fibers

UV fluorescent fibers are randomly distributed throughout the paper stock during manufacturing. Under ultraviolet light (a UV lamp or UV pen), these fibers glow in a distinctive pattern. Because they are distributed randomly in the paper fiber during manufacturing, no two checks have identical fiber patterns. Standard printer paper has no UV-reactive fibers.

A bank or retailer with a UV light source can authenticate any check in seconds by confirming that the UV-reactive fibers are present. A counterfeit printed on plain paper fails this test immediately. UV fluorescent fibers directly address counterfeiting and provide a covert authentication layer that is not visible to the fraudster during check creation.


What the CPSA Padlock Icon Means

The CPSA padlock icon (formally the Enhanced Check Security Features Padlock Icon) is a registered certification mark of the Check Payment Systems Association (CPSA). When this padlock appears on a check, it means the check printing company has submitted an application to CPSA and certified that their checks incorporate a minimum of three security features that collectively defend against both alteration and counterfeiting.

The CPSA minimum of three features to earn the padlock means that not every CPSA-certified check has all six features. Checkomatic's CPSA certification covers the full six-feature ABA security paper used on all orders. The padlock on a Checkomatic check represents the maximum standard, not just the minimum required for certification.

The CPSA FAQ is explicit on a point that many check buyers do not know: "No, you do not have to order checks through your bank or financial institution. Any reputable check printing company can help you with a check order." This directly addresses the misconception that bank-issued checks are inherently more secure or more legitimate than checks ordered from direct manufacturer checks by certified manufacturers like Checkomatic.

CPSA also clarifies that the padlock icon does not verify the validity of any specific check or the availability of funds behind it. It verifies that the paper and printing process meet the enhanced security feature standard. A fraudster could theoretically use stolen blank check stock from a CPSA-certified printer; the padlock does not prevent that scenario. The paper features deter alteration and counterfeiting of checks once they are issued.


Bank-Issued Checks vs Direct-Manufacturer Security Checks

The bank check vs security check comparison: the assumption that bank-issued checks are more secure than checks ordered from a direct manufacturer is a common and costly misconception. Here is the honest comparison.


Paper Grade and Feature Count

Banks typically offer one or two tiers of check stock, and the base tier is often standard security paper with fewer than the full six ABA features. Banks source their check stock from the same pool of check manufacturers and printers that direct-to-consumer manufacturers use. A bank that offers "security checks" as an upgrade tier is offering the same or equivalent paper to what a certified direct manufacturer ships on every order.

Checkomatic ships every order, including the base personal checkbook order, on full ABA-compliant six-feature security paper. There is no base-tier option with fewer features because Checkomatic does not offer a lower-grade stock. This means a Checkomatic buyer gets the complete security feature set without asking for or paying for an upgrade.


MICR Encoding Quality

The MICR line (the magnetic ink numbers at the bottom of every check) must be printed to ABA tolerances for reliable automated processing. Banks and certified direct manufacturers both use MICR-certified equipment and inks. The MICR quality from a CPSA-certified manufacturer like Checkomatic is equivalent to bank-issued checks and processes through the Federal Reserve system identically.


Price Per Check

Banks charge significantly more per check than direct manufacturers. A box of 200 personal checks ordered through a bank commonly costs $25 to $50. The same quantity from Checkomatic at a comparable or superior security level costs considerably less because there is no bank retail markup. The CPSA FAQ specifically notes that ordering from a reputable direct manufacturer is a legitimate, equivalent alternative to ordering through your bank.


Office Supply and Retail Checks

Office supply store check stock (including the Office Depot "Standard Blue Business Check Refills" and similar retail products) is the most variable in security feature quality. As we noted in our business check refill guide, some retail check stock products explicitly list "microprinted: No" and "watermarked: No" in their specifications. Retail check stock may not meet the full ABA six-feature standard despite generic "security" marketing language.


Personal Security Checks

Safe personal checks (personal security checks) are standard personal checkbooks printed on full ABA-compliant security paper. Every Checkomatic personal check format ships on six-feature security paper:


Every format above ships on the same six-feature ABA-compliant security paper. Individuals who write checks for rent, utilities, charitable donations, or contractor payments are among the groups most targeted by check washing (because mailed personal checks are prime theft targets). Six-feature security paper provides the paper-level protection those payers need on every transaction.


Business Security Checks

High security business checks face a higher fraud risk profile than personal checks for two reasons: the amounts are typically larger (making counterfeiting more profitable), and the routing number and account number are the same on every check issued by the business (making any stolen check a template for unlimited counterfeits).

All Checkomatic business check formats ship on six-feature ABA-compliant security paper:

For a complete guide to business check payroll formats and which format serves which workflow, see our business checks and payroll guide.


Blank Check Stock Security

Blank check stock used with MICR printers also ships on ABA-compliant security paper from Checkomatic, with the same six features. The security argument for blank stock is somewhat different from pre-printed checks: with blank stock, the routing number and account number are printed at the time of issuance rather than pre-printed. This means a stolen blank sheet reveals less information than a stolen pre-printed check sheet. However, blank stock requires MICR-capable printing equipment and software to realize this security advantage.

Checkomatic's blank check stock is available in all major business check formats (check on top, middle, bottom, 3-per-page, and Z-fold pressure seal) on the same six-feature ABA security paper.


Do Security Checks Cost More

Security check cost at Checkomatic: security checks do not cost more than non-security checks because Checkomatic does not offer non-security checks. Every order, every format, and every quantity tier ships on full six-feature ABA-compliant security paper. There is no lower-grade stock option and no security surcharge.

This is meaningfully different from how some competitors price security. Some check manufacturers offer a base tier on minimal-feature paper and an "enhanced" or "high security" tier on better paper at a premium. That pricing model creates a situation where buyers who do not actively request the security upgrade receive inadequate protection.

The per-check cost at Checkomatic on ABA-compliant security paper is lower than the per-check cost of bank-issued checks regardless of security tier, because there is no bank retail markup. A buyer ordering directly from Checkomatic gets a better security paper at a lower price than ordering through their bank.

For a full cost comparison of check ordering sources, see our cheap checks online guide.


What Security Paper Cannot Protect Against

ABA-compliant security paper with all six features provides the strongest available check counterfeiting prevention and alteration protection for checks. It does not cover every check fraud scenario, and being clear about its limits helps businesses build a complete protection strategy.

Security paper does not prevent blank check theft. If someone steals your checkbook or gains access to your blank check stock, the security features on the paper do not stop them from writing checks against your account. They help your bank and the receiving party identify fraud after the fact, but they do not prevent the fraudulent check from being written.

Security paper does not prevent forged endorsements. A check made payable to you can be taken from your mailbox and deposited by an unauthorized person who forges your endorsement signature on the back. The face-side security features address the document itself, not the endorsement process.

Security paper does not prevent authorized-signer fraud. If an employee or trusted individual with legitimate access to your checks issues unauthorized checks, the security features cannot distinguish an authorized transaction from an unauthorized one.

Security paper does not replace account monitoring. Regular review of cleared check images through online banking catches fraud that slips through other defenses. For a complete walkthrough of what to do when you notice unauthorized check activity, see our check fraud scams guide and our lost checks and replacements guide.


The Complete Check Security Approach

The 2025 AFP survey and JPMorgan Chase's fraud playbook both describe a multi-layered approach as the effective defense against check fraud. Security checks are the foundation, but the complete approach includes several additional layers.


Layer 1: ABA-Compliant Security Paper (All 6 Features)

Start here. Six-feature security paper is the non-negotiable baseline. It addresses check washing, copying, scanning, and digital counterfeiting at the paper level, before any other defense needs to activate.


Layer 2: Positive Pay

Positive pay (offered by most business banks) requires the account holder to submit an electronic file of all checks issued before they are presented for payment. The bank matches each incoming check against the file and flags mismatches for review. Positive pay with payee name verification adds a check of the payee name against the issued-check record, addressing check alteration that changes the payee. JPMorgan Chase's playbook identifies positive pay as one of the most effective controls available.


Layer 3: Secure Mailing Practices

Dropping checks directly at a post office counter rather than a street collection box prevents the mail theft that enables check washing. Using security envelopes (with dark interior lining that prevents seeing the check through the envelope) prevents visual inspection of the envelope contents before theft.


Layer 4: Account Monitoring

Reviewing cleared check images through online banking regularly catches fraud that passed through other defenses. Compare the payee name and amount on the cleared check image against your check register or accounting software record. Mismatches are the most common way check washing and alteration fraud is caught.


Layer 5: Gel Ink Pen for Manual Writing

For checks written by hand, pigment-based gel ink (the Uni-ball 207 in particular) resists check washing better than standard ballpoint oil-based ink. This provides a secondary layer against chemical ink removal at the written field level, complementing the chemically reactive paper's protection at the background level. For the full analysis, see our check protector and writer tools guide.


Layer 6: Endorsement Stamps for Incoming Checks

Self-inking endorsement stamps apply a restrictive "For Deposit Only" legend to every incoming check at the time of receipt, limiting where it can be deposited even if it is subsequently stolen. Checkomatic's self-inking endorsement stamps are customized with your account information.


Why Order Security Checks From Checkomatic

Checkomatic has manufactured ABA-compliant personal and business checks in Monroe, NY since 1997. As an in-house check manufacturer, every order is produced at the Monroe NY facility with direct quality control over the security paper grade, MICR encoding, and print quality.


All 6 ABA Security Features on Every Order

Checkomatic includes all six standard ABA security features on every check, every format, every quantity tier, at the base price. No security tier, no upgrade required, no additional cost. CPSA padlock certification is printed on every Checkomatic check. This represents the maximum standard available, not the minimum required for certification.


ABA-Compliant MICR Encoding

The MICR line on every Checkomatic check is printed to ABA tolerances using certified MICR inks. ABA-compliant MICR encoding ensures clean automated processing through the Federal Reserve and all financial institutions. Checkomatic checks process identically to bank-issued checks through the US banking system.


Free Logo Printing on Every Order

Free logo printing security checks feature: free black and white logo printing on security checks is included on every personal and business check order. Color logo printing is available for a small per-order charge. No setup fee. Your logo and company details are reviewed in a digital proof before production begins.


Standard 3-to-5-Business-Day Turnaround

Orders ship from Monroe, NY within 3 to 5 business days from digital proof approval. Rush delivery options are available at checkout for time-sensitive needs.

Start your security check order at checkomatic.com. Personal checks start at personal checkbooks. Business formats start at business checks. QuickBooks-specific formats are at QuickBooks checks. Manual check formats are at manual business checks. Blank security stock is at blank check stock.


The Short Version on Safe and Security Checks

Security checks are checks printed on ABA-compliant security paper with fraud deterrent features built in. The 6 standard ABA features each address a specific fraud type: chemically reactive paper catches check washing, genuine foundry watermark and UV fluorescent fibers address counterfeiting, microprinting and void pantograph prevent copying and scanning, and thermochromic ink provides instant authentication. According to the 2025 AFP Payments Fraud and Control Survey, 63 percent of organizations faced check fraud in 2024. Checks remain the most-targeted payment method.

CPSA padlock certification means a check printer has certified to the Check Payment Systems Association that their checks include at least three features defending against both alteration and counterfeiting. Checkomatic carries this CPSA certified checks certification on the full six-feature ABA security paper used for every order.

Bank-issued checks are not inherently more secure than checks from a CPSA-certified direct manufacturer. The CPSA FAQ states this directly. Checkomatic's checks provide the same or better security paper at a lower per-check cost than bank-issued alternatives. Security paper at Checkomatic costs nothing extra because every order uses full ABA-compliant stock as the standard.


Frequently Asked Questions


What are security checks?

Security check definition: security checks are personal or business checks printed on ABA-compliant security paper with fraud deterrent features built into the paper itself and the printing process. The six standard features are: chemically reactive paper (stains permanently when washing solvents contact it), genuine foundry watermark (embedded in the paper fiber during manufacturing, visible under light, cannot be printed or copied), microprinting (text too small to read with the naked eye that blurs in any photocopy or scan), thermochromic ink (disappears when heat is applied, returning when cooled), void pantograph (reveals VOID text when the check is copied or scanned), and UV fluorescent fibers (glow under ultraviolet light, absent in counterfeit checks on plain paper). Security checks are also called safe checks or high-security checks. Every Checkomatic check ships on six-feature security paper at the base order price.


How many organizations experienced check fraud in 2024?

According to the 2025 AFP Payments Fraud and Control Survey, 63 percent of organizations experienced attempted or actual check fraud in 2024. This made checks the most-targeted payment method, ahead of wire transfers, ACH, and all other payment types. The AFP payments fraud survey covered over 500 treasury practitioners and is in its 21st year. The 2026 AFP survey (covering 2025 fraud activity) reported 58 percent of organizations facing check fraud, still the highest rate among all payment types. The AFP data shows check fraud has remained between 58 and 66 percent consistently since 2020.


What does the CPSA padlock icon on checks mean?

The CPSA padlock icon is the Enhanced Check Security Features Padlock Icon, a registered certification mark of the Check Payment Systems Association. Its presence on a check means the printing company certified to CPSA that their checks incorporate a minimum of three security features defending against both alteration and counterfeiting. Earning the padlock requires compliance with the ABA ANSI X9 check standard (ANSI X9.100-170-2010), the Check Fraud Deterrent Icon standard. The padlock does not verify the validity of a specific check or the funds behind it; it verifies the paper and printing process meet the enhanced security standard. CPSA itself does not print checks. It certifies the printers who do. Checkomatic's CPSA certification covers the full six-feature ABA security paper on all orders.


Are bank-issued checks more secure than checks ordered directly from a manufacturer?

Not necessarily, and often the reverse is true. Banks source their check stock from the same manufacturers and printers that direct-to-consumer check companies use. Many banks offer a base tier of minimal-feature check paper and charge for a security upgrade. A CPSA-certified direct manufacturer like Checkomatic ships every order on full six-feature ABA security paper at the base price with no upgrade needed. The CPSA FAQ states directly: "No, you do not have to order checks through your bank or financial institution. Any reputable check printing company can help you with a check order." The MICR encoding quality and bank processing compatibility are identical between bank-issued and certified direct-manufacturer checks.


Do security check features protect against all types of check fraud?

ABA-compliant security paper with all six features addresses check washing (chemically reactive paper), photocopying (microprinting, void pantograph), scanning and digital counterfeiting (void pantograph, genuine watermark, UV fluorescent fibers), and authentication at point of acceptance (thermochromic ink, watermark). It does not prevent blank check theft and fraudulent writing, forged endorsements on incoming checks, or internal fraud by an authorized signer. A complete check security approach layers ABA security paper with positive pay (checks presented versus a file of issued checks), restrictive endorsement stamps for incoming checks, secure mailing practices, and regular account monitoring to catch fraud that slips through other defenses.

Jul 23, 2026

Check Protector and Writer Tools: Complete Security Guide

What a Check Protector Is

Checkwriter definition: a check protector, also known by the synonymous names checkwriter, ribbon writer, check embosser, check writer machine, and check signer, is a device designed to imprint the dollar amount onto a check in a form that is very difficult to alter. The ANSI/ASB Standard 172 (2024 Edition) defines a checkwriter as "a device manually or electrically-powered or computer-generated, designed to ink, emboss, print, perforate, or shred a monetary value, along with other peripheral information, onto a document."

Check protector definition: a check protector physically attacks the paper fibers in the amount field of a check, shredding them and forcing indelible ink into the resulting disruption. Because the paper itself is damaged in the process, amount alteration prevention is the core purpose: any later attempt to chemically wash or mechanically erase the amount causes visible, irreparable damage to the check. The amount field essentially cannot be cleanly altered after being processed through a check writer.

This check embosser machine is positioned over the amount field of the check. The operator enters the payment amount using levers or buttons. A mechanism then drives inked print heads through a colored ribbon and into the paper surface with significant downward force. The result is an imprint that is part ink, part physical disruption of the paper fibers, and part embossed impression visible from both sides of the check.


How Check Protectors and Writers Work Mechanically

The mechanical process of a check writer is more sophisticated than it appears. Understanding it explains why check writers provide stronger amount protection than standard ink writing, and why they were the primary check security tool for most of the 20th century before electronic check security emerged.


The Imprinting Mechanism

As a check fraud prevention tool, the check writer contains a set of character print wheels carrying numerals and symbols. When the operator enters an amount, the relevant print wheels rotate to position. The operator then pulls a lever (on manual units) or presses a button (on electric units), which drives the print heads downward through an inked ribbon onto the check paper beneath.

The force applied is considerably greater than standard printing or writing. The print heads do not merely deposit ink on the paper surface; they physically compress, shred, and perforate the paper fibers in the amount field while driving indelible ink into those disrupted fibers.


The Prefix and Suffix Protection

Beyond the mechanical damage to the paper, check writers add text protection against digit inflation. When you enter $6,762.64, the machine does not simply print "6762.64." It produces text such as "TheSum6762dol's64cts" with words before and after the numerals that fill the available space and prevent a fraudster from adding digits at either end to inflate the amount. This prefix and suffix system, established in the early 20th century, closes the gaps that a simple numerical imprint would leave.


The Embossing Element

Many check writers also emboss the amount through the paper, creating a raised or indented impression visible and tactile from both sides of the check. This embossed impression is independent of the ink and cannot be removed without leaving an obvious trace of the original impression in the paper. Even if an attacker somehow removed all the ink, the physical embossing would remain as evidence of the original amount.


Types of Check Protectors: Punch, Perforator, Ribbon Writer

Check protection technology has evolved through several distinct mechanical approaches since its invention in the mid-19th century. These different types are still relevant for understanding what a check writer does and how it differs from alternatives.


Check Punch

The earliest mechanical check protectors (late 19th century) used a punch mechanism that cut holes in the shape of numerals through the check paper. A check punch produced amounts by physically removing paper in the numeral shapes. The resulting holes could not be filled in, making the amount visible from both sides. However, holes could be covered, which made punches somewhat less secure than later methods.


Check Perforator

Check perforators used a mechanism that punched small round holes (rather than numeral-shaped holes) arranged to form numerals. The perforated pattern was harder to conceal than large numeral holes. Perforators were widely used by the US Treasury and government agencies for check protection in the late 19th and early 20th centuries.


Ribbon Writer (Shredding Writer)

The ribbon writer, introduced commercially around 1914 by Hedman Manufacturing with the F&E Check Writer, became the dominant form of check protection through most of the 20th century. The ribbon writer does not punch holes; instead it forces ink through a ribbon into shredded paper fibers. This "shredding principle" (as described in the 1926 Office Appliance Manual) produces an amount that is simultaneously printed and physically embedded in disrupted paper fibers.

The ribbon writer's advantage over punch and perforator systems is that the amount is rendered in both color and texture, with multicolor ink in disrupted fibers that cannot be chemically washed without destroying the check visibly. The Hedman F&E, described at the time as "not a mere check writer, but an absolute, 100% prevention of loss through alteration of your checks," established the standard that Paymaster Corporation later refined into its long-running product line.


History of Check Writers From 1914 to Paymaster

The history of check writers is the history of the fraud arms race between businesses issuing checks and criminals who raised, altered, or forged them. Understanding that history explains the design choices that make modern check writers effective and why they remain in use today.

Check fraud statistics and history: check fraud in the late 19th and early 20th centuries was described in the trade literature as "one of the gravest and most widespread of all menaces against our nation's business." The primary attack was "raising" checks: altering a check for $6 to read $600 or $6,000 by adding digits or altering handwritten words. Standard handwritten amounts in ink provided no meaningful resistance to skilled check raisers who could wash, scrape, or chemically treat the original amount.

The Hedman Manufacturing Company's F&E Check Writer of 1914 introduced the commercial figure-writing shredding approach. By 1917, competitors including Safe-Guard had developed similar machines. By the 1920s, the safety paper and mechanical check writer combination was recognized as the effective solution: "Where this method of protection has been adopted, to date, there has not been a single case of loss from forgery or alteration" (Burgess Smith, 1922).

Paymaster Corporation, founded in the early 20th century, became the most recognized American check writer manufacturer. Its "Paymaster Check Writer and Protector" became a commercial success through the 1930s depression era and beyond. Paymaster added locks and keys to its machines in the 1950s as security concerns grew. Paymaster check writers remain in regular use today at the US Postal Service for money orders and at financial institutions for cashier's checks, despite the company itself having closed by 2000. The Paymaster brand name continues under successor organizations.


Modern Use Cases for Check Writers

Physical check writers are now considered specialized equipment rather than standard office tools. Most businesses that previously used check writers have shifted to accounting software with MICR printing on ABA-compliant security stock. However, specific use cases remain where physical check writers serve an important function.


Money Order Production

The US Postal Service uses check writers to produce money orders. The mechanical amount imprinting provides the same physical alteration resistance for money orders that it historically provided for checks. Financial institutions use similar equipment for cashier's checks.


High-Value Manual Check Writing

Businesses or organizations that write high-value checks manually (rather than through software) and cannot accept any risk of amount alteration use check writers as a supplement to handwriting. A $50,000 payment written by hand with a gel ink pen carries some washing risk; the same amount processed through a check writer carries near-zero alteration risk from chemical or mechanical attack.


Sole Proprietors and Small Organizations

Some sole proprietors, nonprofits, and small organizations that write manual checks for payments prefer the additional protection of a check writer over pen writing alone. The check writer's mechanical imprint provides a level of assurance that the amount is locked in.

For most businesses writing checks through accounting software, the check writer is made redundant by the security features built into ABA-compliant security stock. The chemically reactive paper, void pantograph, and other features address the same fraud vectors through the paper itself rather than through a separate mechanical device.


The Gel Ink Pen and Check Washing: What the Experiments Show

The gel ink pen check washing recommendation is widely repeated in financial security guidance. The recommendation to write checks with gel ink pens to prevent check washing is widely repeated in financial security guidance. The actual experimental evidence is more nuanced than most guides acknowledge, and the honest assessment is important for anyone relying on a pen as their primary check protection.


The Uni-ball 207 Experiment

In a widely referenced check washing experiment conducted independently by financial security researchers and the OrboGraph Check Fraud Roundtable, several pen types were tested against common check-washing solutions. The Uni-ball 207, with its proprietary Uni-Super Ink, performed best: its pigment ink did not budge under any of the solutions tested. The Uni-ball 207 is the most consistently recommended gel pen for check writing by fraud prevention professionals.


The Pilot G2 Result

The Pilot G2, which has a strong reputation as a premium gel pen, was effectively washed by "Solution B" and faded under another solution in the same tests. This is a significant finding because the Pilot G2 is often cited as a check-writing recommendation without testing. Not all gel pens are equivalent for check washing resistance. The specific ink formulation matters, not just the "gel" category.


The Nuance: Persistence Does Not Mean Impossibility

OrboGraph researchers found that even the best-performing gel pens could have their ink scrubbed off with sufficient physical effort (using a toothbrush with solution) with damage that might not be detectable in a mobile deposit capture image processed in black and white. The gel pen makes washing harder, not impossible. It raises the difficulty bar and increases the chance of visible damage, but a determined fraudster with the right tools can still remove gel ink from checks.

The OrboGraph analysis frames gel pens correctly: they are one tool that makes check washing more difficult for opportunistic criminals, but they are not a complete defense. They should be combined with ABA-compliant security paper, secure mailing practices, and account monitoring.


Best Pens for Writing Checks

The check washing prevention pen category includes several options. Based on wash-resistance testing and expert recommendation, here are the pen characteristics and specific models most effective for check writing security.


Uni-ball 207 (Top Recommendation)

The Uni-ball 207 uses Uni-Super Ink, a proprietary pigment-based gel ink specifically designed to resist check washing. In the most rigorous independent tests, it was the only pen whose ink did not react to any of the washing solutions tested. It is available at most office supply retailers and drug stores for under $3 per pen.


Zebra Sarasa

The Zebra Sarasa line uses Rapid Dry Ink technology that dries in under one second, reducing smear risk for left-handed writers. The pigment-based ink provides strong check washing resistance and is water-resistant and fade-resistant.


Pilot Precise V5/V7

The Pilot Precise uses pigment-based liquid ink (not a gel) that bonds strongly with paper fibers. It is a rollerball format rather than a gel format but provides similar fiber-bonding resistance to washing.


What to Avoid

Standard ballpoint pens with oil-based ink (oil-based ink vulnerable pens) are the most vulnerable to check washing. The oil-based ink sits on the paper surface rather than bonding with the fibers, and washes off more easily with chemical solvents. Felt-tip pens (including many permanent markers) are also vulnerable because their dye-based inks dissolve in solvents rather than bonding with fibers.


Why Ballpoint Ink Washes Off and Gel Ink Does Not

The difference in check washing resistance between ballpoint pens and gel ink pens comes down to the ink composition and how it interacts with paper.

Ballpoint pens use oil-based ink. Oil-based inks are viscous and deposit on the surface of the paper. They do not penetrate deeply into the paper fibers. When a washing solvent is applied to a check written with a ballpoint pen, the solvent dissolves the oil-based binder in the ink, lifting the pigment or dye off the paper surface. The surface remains relatively undamaged because the ink never fully integrated with the paper fibers to begin with.

Pigment ink check writing: gel ink pens use water-based gel carrying pigment particles (solid particles suspended in the gel, not dissolved dyes). The pigment ink fibers mechanism: when gel ink is applied to paper, the water carrier is absorbed by the paper fibers, drawing the pigment particles into the fiber structure. As the gel dries, the pigment particles become embedded within the paper fibers rather than sitting on top of them.

Attempting to wash gel ink with a solvent requires attacking the paper fibers themselves to remove the embedded pigment. This physical disruption is visible as damage to the paper: discoloration, texture change, or tearing of the fibers. A check that has been washed to remove gel ink will show these signs of tampering at the point where the washing occurred.

The ballpoint vs gel ink difference is relevant only for check washing (chemical removal of existing ink). It is not relevant for digital counterfeiting, forgery, or any fraud that does not involve altering an existing check.


What Gel Pens Cannot Protect Against

This is the most important security gap that most gel pen recommendations omit, and understanding it is essential for building a complete check security approach.


Digital Counterfeiting

The dominant fraud trend identified by OrboGraph and other fraud researchers is a shift from check washing toward digital counterfeiting. In digital counterfeiting, the fraudster scans a stolen check to extract the routing number, account number, and the account holder's signature. These elements are then used to create new check documents on a computer using desktop publishing software, printed on any printer, for any amount, in unlimited quantities.

A gel ink pen provides zero protection against this attack. The fraudster never touches the original check's amount field. They create entirely new checks from the extracted data. No amount of ink resistance prevents a new check from being printed with a digital copy of your signature and your account number.


Forgery of the Signature

A forged signature fraud involves a thief who signs your name on a blank check using their own pen. Your gel ink pen in your drawer provides no protection against someone else signing a blank check with any pen they choose.


Physical Theft of Blank Checks

If your checkbook is stolen, the thief can write any amount they choose on the blank checks using any pen, including a gel ink pen. The gel ink protection applies only to checks you have already filled out.

These limitations are why the full check security stack matters: gel ink pen (washing resistance) + ABA-compliant security paper (washing, counterfeiting, and alteration resistance) + secure mailing practices + account monitoring. Each layer addresses fraud types that the others cannot fully cover.


What Check Washing Is and How It Works

Check washing is the fraudulent process of using chemical solvents to remove the ink from a legitimate check without damaging the paper, then rewriting the payee name and dollar amount for fraudulent purposes. It is one of the oldest and most persistent forms of check fraud.

The typical check washing scenario begins with mail theft. A criminal removes envelopes from residential mailboxes or USPS collection boxes looking for envelopes that appear to contain checks. Personal payment envelopes (for rent, utilities, charitable donations, bills) are the most common targets. The stolen check is placed in a chemical bath or treated with solvents such as bleach, acetone (nail polish remover), or commercial cleaning products.

If the check paper and ink are not resistant to these solvents, the ink dissolves and the check emerges with the paper intact and the signature already in place. The fraudster then rewrites the payee name (changing it to themselves or a money mule) and alters the amount. The altered check is then deposited, often at a different institution from where the account is held.

For a complete guide to preventing check fraud including check washing, forged endorsements, and account monitoring, see our check fraud scams guide and our check validity and fraud prevention guide.


How ABA Security Paper Prevents Check Fraud

ABA-compliant check security paper features form the foundational protection layer that addresses the fraud types that gel pens, check writers, and other tools cannot fully cover. Every Checkomatic check ships on this security paper with all six standard features included at the base price.


Chemically Reactive Paper (Check Washing Prevention)

Chemically reactive paper contains agents that react permanently when contacted by the solvents used in check washing. When bleach, acetone, or similar chemicals touch the paper, a visible, permanent stain appears that cannot be concealed or reversed. A bank teller or automated imaging system immediately identifies the check as tampered. This is the paper-level equivalent of what a gel ink pen attempts to achieve with ink alone, but it applies to the entire check surface rather than only the written areas.


Genuine Foundry Watermark (Counterfeiting Prevention)

A watermark embedded in the paper fiber during manufacturing is visible when the check is held to light. No desktop printer or office copier can reproduce a genuine foundry watermark because it is a structural property of the paper, not a surface print. This directly addresses the digital counterfeiting threat: a check printed from a computer on plain paper or even high-quality paper cannot duplicate the genuine watermark, making counterfeits detectable by any bank teller or automated system with UV or transmitted-light verification.


Microprinting (Copying Prevention)

Text printed at a scale requiring magnification to read appears as a solid line to the naked eye along the signature line. Photocopiers and scanners cannot reproduce microprinting accurately; any copy shows a blurred, indistinct line rather than readable text. This makes photocopied or digitally scanned counterfeits detectable at the microprint location.


Heat-Sensitive Thermochromic Ink (Authentication)

An area of the check face printed with ink that disappears when warmed and returns when cooled allows instant authentication. A bank teller rubs the area; on a genuine check, the ink vanishes. On a counterfeit printed on plain paper, no thermochromic zone exists.


Void Pantograph (Copy Detection)

A background pattern that produces visible VOID text when the check is photocopied, scanned, or imaged directly addresses the digital counterfeiting workflow. When a fraudster scans a check to extract the routing number, account number, and signature, the resulting digital image reveals VOID across the check background. Any check printed from this image carries the VOID pattern, identifying it as a copy.


UV Fluorescent Fibers (Authentication)

Fibers distributed through the paper that glow under ultraviolet light distinguish genuine security paper from plain paper immediately. A counterfeit printed on standard paper has no fluorescent fibers and fails this test.

For the complete technical guide to how each security feature works against specific fraud types, see our check stock paper guide and our check fraud prevention guide.


The Layered Check Security Approach

Check writing best practices require multiple layers. No single check security tool addresses every fraud type. Business check security tools work best in layers. The effective check security approach uses multiple layers, each targeting the fraud types the others cannot cover.


Layer 1: ABA-Compliant Security Paper

In a check protector vs security paper comparison, the security paper is the most important foundational layer. Chemically reactive paper catches check washing. The void pantograph and genuine watermark address counterfeiting. Microprinting prevents copy-based fraud. This layer is built into every check you order from Checkomatic at no additional cost.


Layer 2: Gel Ink Pen for Manual Writing

For checks written by hand rather than printed through software, a pigment-based gel ink pen (specifically the Uni-ball 207 for best washing resistance) makes the written fields harder to chemically remove. This is a secondary layer that complements the paper security features rather than replacing them.


Layer 3: Check Writer for High-Value Manual Checks

For manual check security, businesses that write high-value checks manually and want the strongest amount-field protection, a mechanical check writer adds check amount field protection, a physical disruption layer that makes amount alteration nearly impossible even for a skilled fraudster. This layer is most appropriate for manual check writers issuing checks in large amounts.


Layer 4: Secure Mailing Practices

Dropping checks directly at a post office counter (not a street collection box) and using security envelopes with dark interior tinting prevents the initial theft that enables check washing. A fraudster cannot wash a check they never obtained. This layer prevents the theft that makes washing possible.


Layer 5: Account Monitoring

Reviewing cleared check images through online banking catches alterations and forgeries that passed through the banking system. Comparing the payee name and amount on the cleared image against your check register entry identifies fraud that slipped through other defenses. For businesses, positive pay automates this comparison for every check presented.

For more on how the complete check fraud prevention system works, see our check validity and fraud prevention guide and our check fraud scams guide.


Why Order Checks From Checkomatic

Checkomatic has manufactured personal and business checks in Monroe, NY since 1997. As an in-house check manufacturer, Checkomatic produces every order at its Monroe NY facility with direct quality control over the security paper, MICR encoding, and print quality.


ABA Security Paper Standard on Every Order

Every Checkomatic check, whether personal or business, ships on ABA-compliant check paper (ABA compliant check paper) with all six fraud deterrent features at the base price. There is no security tier to upgrade. The CPSA certified designation on Checkomatic's ordering pages confirms compliance with Check Payment Systems Association standards.

These six features provide the paper-level protection that complements whatever writing tool the account holder uses. A check written with a Uni-ball 207 on Checkomatic security paper has gel ink resistance to washing AND chemically reactive paper resistance to washing, AND void pantograph counterfeiting detection, AND genuine watermark authentication, AND microprinting copy detection.


Full Personal and Business Check Range

Checkomatic manufactures personal checks, business computer checks, manual business checks, QuickBooks checks, and blank check stock. All formats for manual check writing, where a check writer or gel ink pen is most relevant, are available:


Free Logo Printing on Every Order

Free black and white logo printing is included on every personal and business check order. Color logo printing is available for a small additional per-order charge. No setup fee. Standard turnaround is 3 to 5 business days from digital proof approval.

Order at checkomatic.com. For the complete guide to check security features built into Checkomatic's paper, see our check stock paper guide. For the EZShield fraud recovery service that some check printers offer as an add-on, see our EZShield check security guide.


The Short Version on Check Protector and Writer Tools

A check protector (checkwriter, ribbon writer, check embosser) is a mechanical or electric device that imprints the dollar amount onto a check by shredding paper fibers and forcing indelible multicolor ink into the disrupted area, with prefix and suffix text that prevents digit inflation. Amount alteration on a check writer-protected check requires visibly destroying the check. Mechanical check writers are most relevant for high-value manual check writing; most businesses printing through accounting software are better served by ABA security paper.

The best pen for check writing is the Uni-ball 207, which performed best in wash-resistance experiments. Standard ballpoint pens use oil-based ink that sits on the paper surface and washes off more easily; pigment-based gel ink bonds with paper fibers and is harder to remove. Gel pens resist check washing only: they provide no protection against digital counterfeiting, forgery, or blank check theft.

ABA-compliant security paper addresses check washing (chemically reactive paper), counterfeiting (genuine watermark, void pantograph), and copying (microprinting) at the paper level. Every Checkomatic check ships on this security paper with all six features at the base price.


Frequently Asked Questions


What is a check protector?

A check protector, also called a checkwriter, ribbon writer, check embosser, or check writer machine, is a mechanical or electric device that imprints the dollar amount onto a check in a form that is very difficult to alter. The check protector definition from ANSI/ASB Standard 172 (2024) describes it as a device designed to "ink, emboss, print, perforate, or shred a monetary value onto a document." The machine presses print heads through an inked ribbon into the paper of the check, shredding the paper fibers under the amount field and forcing indelible ink into the disruption. Any attempt to chemically remove or erase the imprinted amount visibly damages the check. Prefix and suffix text is added around the numerals to prevent adding digits at either end to inflate the amount.


What is the best pen to write checks with to prevent fraud?

The best pen for writing checks to resist check washing is the Uni-ball 207, which uses Uni-Super Ink (a proprietary pigment-based formulation). It performed best in multiple wash-resistance experiments, with its ink not reacting to any washing solutions tested. The Pilot G2, despite its reputation, was effectively washed by certain solutions in the same tests. Standard ballpoint pens (oil-based ink) are the most vulnerable to check washing because oil-based ink sits on the paper surface and washes off more easily. Pigment-based gel ink bonds with paper fibers, making removal require physical damage to the paper that is visible at the washing site. For complete protection, gel ink pens should be combined with checks on ABA-compliant security paper.


Do check protectors still work and are they still available?

Yes, mechanical and electric check protectors work as designed and remain available for specialized uses. The US Postal Service uses check writers for money orders, and financial institutions use them for cashier's checks. New electric check writers are still manufactured in smaller quantities for businesses issuing high-value checks manually. The Paymaster brand, historically the most recognized US check writer manufacturer, has successor organizations that continue the product. For businesses printing checks through QuickBooks or other accounting software, MICR check security through MICR printing on ABA-compliant security stock has largely replaced the physical check writer by providing the same fraud protection through paper-level security features.


What is check washing and how does security paper prevent it?

Check washing is a fraud method where criminals use chemical solvents (bleach, acetone, alcohol-based cleaners) to remove ink from a stolen check without damaging the paper, then rewrite the payee and amount for unauthorized use. Fraudsters typically steal checks from residential mailboxes or USPS collection boxes. Chemically reactive security paper prevents effective check washing by containing agents that produce a permanent, visible stain when washing solvents contact the paper. This makes the tampering immediately obvious to a bank teller or automated image system. The stain cannot be removed or concealed. Combined with a void pantograph (reveals VOID text when scanned), genuine watermark, microprinting, thermochromic ink, and UV fluorescent fibers, ABA security paper addresses check washing and counterfeiting at the paper level.


Does Checkomatic sell check protectors or check writers?

Checkomatic does not sell mechanical check protectors or electric check writers. Checkomatic manufactures personal and business checks on ABA-compliant security paper with six built-in fraud deterrent features: chemically reactive paper, genuine watermark, microprinting, heat-sensitive thermochromic ink, void pantograph, and UV fluorescent fibers. These paper-level features address check washing, counterfeiting, and copying at the manufacturing stage. Businesses that write high-value checks manually and want additional amount protection can use a third-party mechanical check writer alongside Checkomatic's security check stock. The combination provides both paper-level protection from the ABA security features and mechanical amount protection from the check writer.

Jul 23, 2026

Business Checks for QuickBooks Reviews: Real Customer Ratings and What They Actually Say


Overview: Checkomatic Business Checks for QuickBooks at a Glance

Checkomatic has been manufacturing business checks for QuickBooks users from its Monroe, NY facility since 1997. In that time, more than 465 verified customers have left ratings on Checkomatic's QuickBooks-related product pages. The reviews span first-time buyers testing a new supplier and repeat customers who have been ordering for 10 to 15 years.


Picture for category Manual Business Checks


Business checks for QuickBooks reviews from actual buyers tell a consistent story across three areas: the checks work with QuickBooks straight out of the box, they cost significantly less than bank-issued equivalents, and they arrive faster than most bank check programs deliver. The minority of negative reviews cluster around specific, preventable ordering mistakes rather than product quality or compatibility issues.

This business checks for QuickBooks reviews guide draws on every published review on Checkomatic's QuickBooks check pages, organized by theme, so you can make an informed decision before placing your first order.


Overall Ratings: What the Numbers Show

Checkomatic's QuickBooks business check products carry the following verified ratings as published on the product pages:

  • QuickBooks Starter Pack (checks, deposit slips, envelopes, stamp): 4.5 stars from 166 verified reviews
  • QuickBooks Check on Top (Voucher): 4.5 stars from 112 verified reviews
  • General Business Checks (all formats): 4.5 stars from 185 verified reviews

Across all QuickBooks-related pages, the combined verified review count exceeds 465 ratings. A 4.5 out of 5 rating at that volume is a meaningful signal. Independent industry reviewers note that a product rated between 4.3 and 4.7 from 100 or more verified buyers is statistically more reliable than a perfect 5.0 from fewer reviews, because higher-volume ratings capture a wider range of buyer experiences including edge cases.

The rating distribution across Checkomatic's QuickBooks check pages skews strongly toward 5-star reviews. The minority of 3-star and below ratings represent specific ordering or communication situations rather than product defects or QuickBooks compatibility failures.


What Positive Business Checks for QuickBooks Reviews Consistently Say

Reading through all published business checks for QuickBooks reviews on Checkomatic's pages, five themes appear consistently across multiple independent buyers.


Theme 1: Checks Work With QuickBooks With Zero Setup Changes

The single most frequently cited positive in QuickBooks business check reviews is that the checks printed correctly from QuickBooks without requiring any printer setup adjustments. This matters because check alignment is the most common pain point when switching check suppliers. If the new check stock dimensions or MICR placement differ even slightly from the previous supplier, every check in the first print batch may be misaligned.

Multiple verified buyers specifically call out this zero-adjustment experience:


Theme 2: Faster Delivery Than Expected

Checkomatic quotes 3 to 5 business days for standard production and shipping. Verified reviews consistently show delivery at or below that estimate, with several buyers noting checks arrived earlier than the quoted window.


Theme 3: Significant Savings Versus Bank Checks

The most specific and frequently cited price comparison in business checks for QuickBooks reviews is the cost difference between Checkomatic and ordering through a bank or directly through a bank's check program. Multiple buyers quantify this difference.

★★★★★

"I'm the treasurer of my chapter of the Vietnam Veterans of America and a QuickBooks user. I ordered the voucher checks. They were printed as I had ordered and work perfectly with my HP inkjet printer. The checks arrived as promised and in perfect condition. I got 500 checks for less than half of what the bank wanted for 200!"

VVA Voucher Checks (Vietnam Veterans of America) | Source: checkomatic.com/quickbooks-starter-pack-product


Theme 4: First Orders Exceed Expectations

A recurring pattern in business checks for QuickBooks reviews is first-time buyers expressing surprise at the quality relative to what they expected from an online check supplier at these prices.

★★★★★

"First time ordering and I am super impressed with the quality of the checks. No issues with delivery. I will be ordering again!"

TClinton | April 9, 2025 | Source: checkomatic.com/quickbooks-starter-pack-product


Theme 5: Long-Term Customer Retention

A significant portion of Checkomatic's QuickBooks check reviews come from repeat customers referencing multiple years or decades of continuous ordering. This pattern appears across different business types and industries.

★★★★★

"Been with them for 15 years. Always reliable, always good quality, good service. What more can you ask for?"

ATV Inc. | April 5, 2024 | Source: checkomatic.com/quickbooks-starter-pack-product


Honest Look at Complaints in Business Checks for QuickBooks Reviews

An honest review of business checks for QuickBooks from Checkomatic means including the negative experiences as well. The published reviews on Checkomatic's product pages include critical feedback, and that transparency is worth acknowledging.

Three complaint types appear in the lower-rated reviews. None relate to QuickBooks compatibility or check quality. All three relate to ordering process or communication issues.


Complaint 1: Quantity Confirmation at Checkout

One reviewer ordered 300 checks but received 1,200. The customer's position was that the website made a mistake. Checkomatic's position was that the quantity shown on the order confirmation reflected what was ordered and invoiced. The reviewer received a partial refund but not the full amount including shipping.

The lesson for buyers: Always verify the quantity field on your order summary screen before clicking the final confirm button. Quantities can be changed during the customization process and the final confirmation screen is the last checkpoint before the order goes to production.


Complaint 2: Rush Order Timeline Expectations

One reviewer selected rush processing but reported the order had not shipped after 8 business days. The review did not include contact with customer service about the delay.

Rush processing at Checkomatic is subject to production capacity on the day the order is placed. For genuinely time-critical orders, contacting the Checkomatic team by phone before placing the order confirms current rush availability and realistic turnaround for your specific check type and quantity.


Complaint 3: Monday Office Hours

One reviewer called Checkomatic on a Monday and found the office closed. This is an operational note, not a product complaint. Checkomatic's business hours do not include Monday.

These three complaint types account for the negative reviews in the published set. The consistent pattern is that product quality, QuickBooks compatibility, MICR accuracy, and check security are not cited negatively in any published review. The complaints that do appear are about the ordering process and communication timing, which buyers can largely prevent by confirming order details before submitting and contacting support during business hours.


Review Theme: QuickBooks Alignment and Setup

Check alignment is the most technically sensitive part of switching check suppliers. When alignment is off, your accounting software's printed fields (payee name, dollar amount, date) land in the wrong position on the check stock, producing a batch of unusable checks. This is the most common reason buyers return to the same supplier year after year: switching creates alignment risk.

In business checks for QuickBooks reviews from Checkomatic buyers, alignment is almost universally a non-issue. The pattern in reviews is that checks printed correctly from QuickBooks without any printer setup modifications. Multiple buyers reference this specifically, suggesting Checkomatic's manufacturing is calibrated closely to QuickBooks's default print template dimensions.

For buyers who do experience minor alignment differences (typically 0.05 to 0.10 inch offsets), QuickBooks Desktop's alignment adjustment tool in File, Printer Setup corrects the issue in under two minutes. QuickBooks Online's Print Setup screen has a fine-tuning grid that handles the same correction. Neither adjustment requires special knowledge or tools.

For the complete QuickBooks setup and alignment walkthrough, see our QuickBooks-compatible checks guide.

Quickbooks Checks 3 on a page

Review Theme: Check Quality and Security Features

Check quality in buyer reviews covers two things: the physical quality of the paper and printing, and the security features built into the check stock.

On physical quality, Checkomatic reviews consistently describe the paper as thick and professional-looking compared to what buyers expected at the price point. One business owner managing eight restaurant locations noted they had placed many orders without a single quality issue. A 33-year veteran check buyer switching from a previous vendor described being "totally blown away" by the quality relative to their expectations.

On security, Checkomatic includes six CPSA-certified security features on every business check for QuickBooks at the base price:

  • Chemically sensitive paper that stains visibly when washing solvents are applied
  • Microprinting along the signature line that degrades on any photocopy
  • Void pantograph that reveals VOID on any copy or scan
  • UV fluorescent fibers that glow under bank authentication equipment
  • Heat-sensitive ink that disappears when touched and returns when cooled
  • Pre-encoded MICR in certified magnetic iron oxide toner

These six features are included at the standard price. There is no requirement to upgrade to a premium tier to get meaningful fraud protection. For a detailed explanation of each security feature, see our business check security features guide.


Review Theme: Delivery Speed and Order Accuracy

Delivery speed appears as a positive across the majority of business checks for QuickBooks reviews. Checkomatic's standard production timeline of 3 to 5 business days is consistently met or beaten according to buyer accounts. The rush order that delivered the full 2,500-check order the same day as the initial rush batch is the most dramatic example, but incremental examples of early delivery appear throughout the review set.

Order accuracy is also highly rated. One reviewer who has used Checkomatic for five years and multiple accounts described never having a printing error. Another noted that when a spelling error did occur, Checkomatic reprinted and reshipped the corrected order promptly.

The one delivery complaint (rush order delay) stands out as an outlier against the broader pattern of positive delivery reviews. The ratio of positive to negative delivery experiences in the published review set is approximately 30 to 1.


Review Theme: Pricing Versus Ordering Checks Through a Bank

Price is the most quantified topic in business checks for QuickBooks reviews. Buyers who mention pricing do so in specific terms rather than general impressions, which makes this theme particularly reliable as a data point.

The VVA chapter treasurer's review is the most specific: 500 checks from Checkomatic for less than half the cost of 200 checks from their bank. If taken at face value, that implies a per-check cost difference of more than 4 to 1 in favor of Checkomatic. This figure is consistent with Checkomatic's published claim of 50 to 70 percent savings versus bank-issued checks.

A corporate buyer managing check printing for eight restaurant locations notes using Checkomatic for all their checks and deposit slips, citing cost as lower than banks for all these products.

The 33-year veteran check buyer who switched from a previous vendor specifically said she could not "fathom the money" she would have saved if she had found Checkomatic sooner. This type of regret-at-late-discovery language appears in multiple reviews and reflects the savings gap between direct-manufacturer pricing and both bank-issued and brand-name retail check pricing.


Review Theme: Customer Service Experience

Customer service appears in business checks for QuickBooks reviews in two contexts: when orders go smoothly (mentioned briefly as part of an overall positive experience) and when something goes wrong (the determining factor in whether the reviewer stays a customer).

The most detailed customer service review describes working with a specific team member named Malky through several proof revisions for a custom business envelope design until the result was exactly what the customer wanted. That reviewer described Checkomatic's service as always prompt and courteous and cited meaningful savings over their previous supplier.

The spelling error case (reviewer noted their business name was misspelled, called Checkomatic, was told the issue would be handled immediately, and received corrected checks within a week) is a good example of how errors are resolved. The reviewer specifically said they would do business with Checkomatic again despite the initial error.

The negative customer service interactions in the review set relate to the quantity dispute and the Monday closure, both of which are preventable with the information in this guide.


What Long-Term Repeat Customers Say in Business Checks for QuickBooks Reviews

Long-term repeat customers represent the most valuable segment of the business checks for QuickBooks review base. Unlike first-time buyers who may be evaluating based on limited experience, repeat customers of 5 or more years have experienced the product across multiple print batches, potentially multiple QuickBooks version upgrades, and likely at least one or two customer service interactions.

★★★★★

"We use CheckoMatic for all of our check needs! They have great prices and we receive our products in a timely manner!"

CG's Tax Service | September 18, 2024 | Source: checkomatic.com/quickbooks-starter-pack-product
★★★★★

"ASJ Wilson Construction has been a client of Checkomatic for some years now and they've never disappointed this company. Thank you Checkomatic for all that you do."

ASJ Wilson Construction | June 6, 2024 | Source: checkomatic.com/quickbooks-starter-pack-product
★★★★★

"Affordable and efficient. My go-to business check printer."

Doe | January 24, 2025 | Source: checkomatic.com/quickbooks-starter-pack-product

The "hassle-free" description from the 5-year customer captures the recurring theme in long-term business checks for QuickBooks reviews. Long-term buyers do not describe Checkomatic as the cheapest option they found or the fastest supplier they tried. They describe it as the one they stopped looking after finding.


QuickBooks Business Check Formats Reviewed

Checkomatic offers three formats for business checks for QuickBooks. Review patterns differ slightly by format.


Voucher Checks (Check on Top)

The most reviewed and most ordered format. One check per page, two perforated payment stubs below. Default for QuickBooks Desktop and QuickBooks Online payroll and accounts payable printing. Reviews for this format are overwhelmingly positive on alignment and print quality. Multiple reviewers specifically note that voucher stubs include all the payroll or AP detail they need. This is the format recommended for any QuickBooks user running payroll or paying vendors where remittance detail matters.


Standard 3-on-a-Page Checks

Three checks per page, no stubs. Lower cost per check. Appropriate for businesses that track all payment detail in QuickBooks and do not need physical remittance stubs traveling with each payment. Reviews for this format are positive on print accuracy and cost efficiency. Less commonly reviewed than voucher because it is less commonly ordered.


Wallet Checks

Smaller personal-size checks, three per page. Designed for lower-volume check writing where portability matters more than detailed stubs. The least commonly ordered of the three QuickBooks-compatible formats at Checkomatic. Review volume is lower but consistent with the overall positive trend.

For a detailed comparison of all three QuickBooks check formats and guidance on which is right for your workflow, see our QuickBooks checks catalog and the complete QuickBooks-compatible checks guide.

Blue

Who Checkomatic Business Checks for QuickBooks Are Best For

Based on the business types represented in the review set, Checkomatic business checks for QuickBooks deliver the strongest value for four types of buyers.


Small Businesses Switching From Bank-Issued Checks

Every reviewer who compared Checkomatic pricing against their previous bank check program reported meaningful savings. For businesses that have been ordering through their bank by default since opening their account, switching to Checkomatic is the single largest check-related cost reduction available without any change to the QuickBooks workflow.


QuickBooks Online Users Printing Payroll Checks

QuickBooks Online's voucher check template is the format Checkomatic's checks are manufactured to match. Multiple QuickBooks Online users in the review set report zero setup changes needed, making this the lowest-friction check switch possible for this user group.


High-Volume AP Operations

Buyers managing multiple business checking accounts (such as the restaurant group with eight accounts) and businesses with high monthly check volumes benefit most from Checkomatic's per-check cost structure. Bulk ordering drops the per-check cost further, and Checkomatic's in-house manufacturing means large orders do not hit third-party production bottlenecks.


Businesses With a Tight Payroll Timeline

The rush delivery option, confirmed by multiple reviewers to operate as described, makes Checkomatic viable for businesses that need to close a check supply gap on short notice. The same-day full delivery described in one review represents the best-case scenario, but even standard 3 to 5 business day production is faster than most bank check programs for reorders. See our business checks for payroll guide for timing recommendations.


How to Order Business Checks for QuickBooks From Checkomatic

Based on the review patterns including the complaint cases, here is the ordering process with the steps that prevent the most common issues.

  1. Select your format: Choose Voucher (check on top), Standard 3-on-a-page, or Wallet based on your QuickBooks check style setting. If you are unsure, Voucher is the correct format for most QuickBooks users. Confirm your format at File, Printer Setup, Check Style in QuickBooks Desktop, or at Settings, Print Checks, Print Setup in QuickBooks Online.
  2. Enter your business and banking information: Business name, address, ABA routing number from the bottom left of an existing check, and checking account number. For routing number verification, see our ABA routing number guide.
  3. Enter your starting check number: One above the highest check number you have already written. See our check reorder guide for how to find this number in QuickBooks.
  4. Add logo and design options: Upload your logo file for free black-and-white printing. Select your background color and security level.
  5. Verify quantity before confirming: Read the quantity field on the order summary screen. This is the step that prevents the quantity dispute described in the complaint reviews. If it shows more checks than intended, correct it before clicking confirm.
  6. Review the digital proof: Read every field: business name spelling, address, routing number, account number, starting check number, and logo placement. Approve only when all fields are confirmed correct.
  7. Select shipping: Standard (3 to 5 business days) or rush for time-critical needs.

Browse the complete QuickBooks business check catalog at checkomatic/quickbooks-checks or the full business checks range.


Why Choose Checkomatic for Business Checks for QuickBooks

27 Years of In-House Manufacturing

Checkomatic has manufactured business checks in Monroe, NY since 1997. Every order is produced at the company's own facility. Your banking information never passes through a third-party print vendor. The MICR encoding on every check is pre-verified against the Federal Reserve E-Payments Routing Directory before production begins.


Six Security Features at Base Price

Chemically sensitive paper, microprinting, void pantograph, UV fluorescent fibers, heat-sensitive ink, and pre-encoded MICR are all standard on every QuickBooks business check order. No upgrade tier required for meaningful fraud protection. See our MICR line explained guide for how the pre-encoding works.


Free Logo on Every Order

Black-and-white logo printing is included at no charge on every order regardless of quantity. Full-color logo printing is available as an upgrade.


50 to 70 Percent Below Bank Pricing

Pricing confirmed by multiple verified buyers comparing Checkomatic directly against their bank's check program. The Vietnam Veterans of America chapter received 500 checks for less than half of what their bank charged for 200.


Compatible With All QuickBooks Versions

QuickBooks Desktop Pro, Premier, Enterprise, Accountant, QuickBooks Online, QuickBooks Self-Employed, and QBConnect are all supported. Also compatible with Xero, MYOB, Quicken, and over 500 other accounting platforms.


3 to 5 Business Day Standard Turnaround

Confirmed by the majority of reviewers across multiple years of orders. Rush options available for payroll deadlines.


Quick Summary: Business Checks for QuickBooks Reviews

Reading through all business checks for QuickBooks reviews published on Checkomatic's product pages reveals a clear pattern. Business checks for QuickBooks reviews from 465 or more verified Checkomatic customers show a 4.5 out of 5 star overall rating. The dominant review themes are: QuickBooks alignment works out of the box without printer setup changes, delivery arrives in 3 to 5 business days or faster, pricing is 50 to 70 percent below bank check programs, and first-order quality exceeds expectations.

Long-term repeat customers describe the experience as hassle-free over periods of 5 to 15 or more years. Negative reviews represent a very small minority and cluster around ordering process issues (quantity confirmation) and communication timing (Monday hours) rather than product quality or QuickBooks compatibility. The three QuickBooks-compatible formats available are Voucher (check on top, most common), Standard 3-on-a-page (highest volume, lowest cost per check), and Wallet (personal-size, lowest volume).

Keywords covered: business checks for QuickBooks reviews, checkomatic QuickBooks checks review, QuickBooks business checks ratings, are Checkomatic checks good, best business checks for QuickBooks, QuickBooks compatible check reviews, checkomatic customer reviews, does checkomatic work with QuickBooks, checkomatic delivery time, checkomatic check alignment QuickBooks, checkomatic security features review, checkomatic vs bank checks, QuickBooks voucher check reviews, checkomatic pricing review, ordering business checks for QuickBooks online.

Additional keywords covered in this business checks for QuickBooks reviews guide: business checks QuickBooks online reviews from verified buyers, Checkomatic reviews and ratings across 465 or more customers, how to buy business checks for QuickBooks at the best price, Checkomatic check quality assessment across paper weight and security, QuickBooks check printing reviews covering alignment and format compatibility, Checkomatic customer experience across first orders and long-term repeat purchases, and how good are Checkomatic checks compared to bank-issued QuickBooks business checks. Business checks for QuickBooks reviews confirm that Checkomatic quality consistently meets or exceeds buyer expectations at 50 to 70 percent lower cost than bank programs.


Jul 22, 2026

Business Check and Voucher Refill Supplies: Full Guide

What a Voucher Check Is

Voucher check definition: a voucher check is a full-sheet business check printed on an 8.5-by-11-inch sheet. The check occupies one third of the sheet (8.5 inches wide by approximately 3.5 inches tall). The remaining two thirds of the sheet contains one or two voucher stubs that carry payment detail fields: invoice number, invoice date, gross amount, discount amount, net payment, and memo lines.

The voucher check is also called a computer check or laser check because it is designed to feed through a laser or inkjet printer connected to accounting software. The software fills in the variable payment data (payee, amount, date, check number) while the pre-printed stock carries the fixed company information (name, address, logo, routing number, account number).

The stub is what distinguishes a voucher check from a basic check. When the payment is processed, the check tears away from the stub at the perforation. The check goes to the payee for deposit. One stub stays with the payer as a payment record; the second stub may be sent to the payee as a remittance advice explaining what the payment covers. This self-contained remittance data is the primary reason businesses use voucher checks rather than wallet-sized checks for accounts payable and payroll.

For a complete breakdown of all check types and how voucher checks compare to personal check formats, see our check types and terminology guide.


What a Refill Order Is vs a New Order

The check reorder process for a refill order is the same as a new check order in terms of printed information. The difference is in the starting check number and in the context: a refill continues an existing check sequence, while a new order starts a sequence for the first time.

When you place a refill order, you use the same company name, address, logo, routing number, and account number as your previous order. The only field that changes is the starting check number. Your refill order starts at the check number immediately following the last check in your previous box. For example, if your previous box ended at check 3500, the refill starts at check 3501.

Every other aspect of the refill order is identical to your original order: the same format (check on top, 3-on-a-page, etc.), the same paper color, the same logo placement, the same accounting software compatibility setting. If any of your company information has changed since the last order (address, account number, logo), those updates go into the refill order as a changed-information order, which generates a new digital proof for review before production.


Business Check Format Guide: Every Type Explained

Business check refills come in multiple formats, and matching the refill to the correct format is the most common source of ordering errors. Here is every business check format with its format code and use case.


Check on Top (Voucher Format)

The most widely used business check format for QuickBooks and most accounting software. The check occupies the top third of the 8.5-by-11 sheet. Two voucher stubs with payment detail fields occupy the middle and bottom thirds. QuickBooks calls this the "voucher" setting in its check print setup. One stub is retained by the payer; one stub may accompany the check to the payee.

Checkomatic's check on top business checks are the standard refill format for QuickBooks and most US accounting software.


Check in Middle

The check occupies the middle third of the sheet, with one stub above and one below. Used with Sage 50 (Peachtree) and MYOB accounting software, which use a different print template layout than QuickBooks. If you use Sage 50, your refill order must specify check in middle format. Ordering check on top instead will produce misaligned printing.

Checkomatic's check in middle business checks match the Sage 50 print template configuration.


Check on Bottom

The check occupies the bottom third of the sheet with two stubs above. Used with specific software configurations that print the stubs before the check. Less common than check on top but used by certain payroll and specialty accounting systems.

Checkomatic's check on bottom business checks are available as refills for this format.


3-on-a-Page Checks

Three checks occupy one 8.5-by-11 sheet with no voucher stubs. This format maximizes check output per sheet and is most efficient for high-volume check printing where remittance data is sent separately or not needed. QuickBooks calls this format "standard" in its check print settings. After checks are removed from the sheet, a form leader (an attachment strip) can be used to keep the partial sheet aligned in the printer.

Checkomatic's 3-on-a-page business checks are the standard refill for this format.


QuickBooks-Compatible Checks

Checkomatic's QuickBooks checks are formatted and tested for both QuickBooks Desktop and QuickBooks Online print templates. This includes the check on top (voucher) format and the 3-on-a-page (standard) format, plus the wallet check format. A QuickBooks starter pack is available for first-time orders to verify template alignment before committing to a full box.


Manual Accounts Payable Checks

Manual business checks are handwritten rather than software-printed. The 3-on-a-page manual format contains three checks per page with detachable stubs. Manual AP checks are the refill format for businesses that write accounts payable checks by hand, typically for payments to vendors who do not require electronic records.

Checkomatic's manual accounts payable checks are available as refill orders.


Manual Payroll Checks

A payroll check refill in 3-on-a-page format includes payroll-specific stub fields for gross pay, deductions, and net pay. Used by businesses that process payroll manually for employees without direct deposit. The payroll stub stays with the employee as their pay stub record.

Checkomatic's manual payroll checks are available as refill orders.


Manual Multi-Purpose Checks

Multi-purpose manual checks offer flexible stub fields suitable for both payroll and AP payments, making them the right choice for very small businesses that write both types of checks from the same book.

Checkomatic's multi-purpose manual checks are available as refill orders.


Manual Executive Deskbook Checks

A compact deskbook refill uses a smaller page that fits a standard 7-ring binder more easily than the full 3-on-a-page format. Used by executives and business owners who prefer a compact desk format over the full-page manual check.

Checkomatic's compact executive deskbook checks are the refill format for this size.


Manual Pocket Checks

A pocket check refill order covers manual business checks in a smaller format designed for portability. Used by contractors, field service businesses, and sole proprietors who write checks away from the desk.

Checkomatic's manual pocket checks are available as refill orders.


How Many Checks Per Box for Each Format

Knowing the quantity per box lets you calculate how long a refill order will last based on your monthly check volume. Here is the standard quantity breakdown by format.


Computer Business Checks (Voucher, Check on Top/Middle/Bottom)

Computer business checks (single checks per sheet) typically come in quantities of 250 or 500 sheets per box, with one check per sheet. A 500-sheet box gives you 500 checks. For a business writing 50 checks per month, a 500-check box lasts approximately 10 months.


3-on-a-Page Computer Checks

A 500-sheet box of 3-on-a-page checks gives 1,500 checks (3 per sheet). For a business writing 150 checks per month, a 1,500-check box lasts approximately 10 months. The per-check cost is lower than single-check-per-sheet formats because fewer sheets of security paper are used per check.


Manual Business Checks (3-on-a-Page)

Manual checks in 3-on-a-page format are sold in pads, typically with 25 pages per pad and 3 checks per page, giving 75 checks per pad. A standard refill order of 4 pads gives 300 checks. For a business writing 25 manual checks per month, 4 pads last approximately 12 months.


Manual Pocket Checks

Manual pocket checks come in a wallet-sized format with fewer checks per pad than desk format. Typical pad sizes range from 20 to 50 checks per pad.


Pre-Printed Refill vs Blank Check Stock

When refilling your business check supply, you have two product categories to choose from: pre-printed check refills and blank check stock. Understanding the difference helps you choose the right path for your business's volume and equipment.


Pre-Printed Check Refills

Pre-printed check refills arrive with your company name, address, logo, routing number, and account number already on every sheet. Your accounting software prints only the variable payment data (payee, amount, date, check number) at print time. A standard laser or inkjet printer is all you need.

Pre-printed refills are the right choice for most small and medium businesses. They are faster to print (no full-page printing required for each check), easier to set up (the fixed fields are already aligned), and available from direct manufacturers like Checkomatic at a lower per-check cost than bank-ordered checks.

The limitation of pre-printed refills is that they are account-specific. A box of pre-printed checks can only be used with the account number printed on them. If you have multiple checking accounts, each account needs its own separate box of pre-printed stock.


Blank Check Stock Refill

Blank check stock is ABA-compliant security paper with no pre-printed information. A MICR blank check stock requires a MICR-capable printer (one with magnetic toner or ink) to print all check data including the MICR line at print time. Software such as PrintBoss, VersaCheck, or MultiCHAX manages the MICR encoding and check layout.

Blank check stock is cost-effective for high-volume check printers because a single box of blank stock can serve multiple bank accounts with different routing and account numbers. You do not need separate boxes per account. Checkomatic's blank check stock is available in check on top, check in middle, check on bottom, and 3-per-page formats, all on ABA-compliant security paper.

The cost of blank stock appears lower per sheet but requires accounting for the MICR printer cost and the software subscription. For most businesses writing fewer than 500 checks per month, pre-printed refills are the more cost-effective and simpler option. For businesses writing 500 or more checks per month across multiple accounts, blank stock with MICR printing often becomes the lower total-cost option.

One critical note about blank stock security: Office Depot's "Standard Blue Business Check Refills" product listing shows a product with no microprinting and no watermark, flagged as having "anti-counterfeiting features" but with those features unspecified and the microprinting field specifically marked "No." Blank check security: blank stock from a CPSA-certified manufacturer like Checkomatic includes all six ABA security features. Always verify the security feature specifications of any blank check stock before ordering.


QuickBooks Voucher Check Refill Ordering

QuickBooks users have a specific refill workflow that differs slightly from general business check ordering. Here is what you need to know.


Format Matching is Critical

QuickBooks supports three check print formats: voucher (check on top, two stubs), standard (3 checks per page, no stubs), and wallet (personal-size, one per page). Your refill order must match the format setting in your QuickBooks printer setup. To confirm your current QuickBooks check format, go to File, then Printer Setup, then select Check from the Form Name dropdown. The selected style (Voucher, Standard, or Wallet) is the format your refill should match.


Third-Party Refills Are Compatible

QuickBooks does not require its own brand of checks for printing. Any check formatted to match the QuickBooks voucher, standard, or wallet template works. Intuit's own IntuitMarket checks are one option; direct manufacturers like Checkomatic offer compatible checks at lower per-check cost because there is no Intuit reseller margin. Checkomatic's QuickBooks-compatible checks are tested for alignment with QuickBooks Desktop and Online.


Form Leaders for Partial Sheets

When you remove the last check from a 3-on-a-page sheet, the remaining stub has no perforated area to keep it aligned in the printer for subsequent pages. Check form leaders (a check form leader is a paper strip that attaches to a partial sheet) to create a full-height feed through the printer. QuickBooks users who use 3-on-a-page format should keep form leaders on hand to avoid printer feed errors at the end of a sheet. Intuit sells these through IntuitMarket; they are also available from third-party check suppliers.


QuickBooks Online Limitation on Blank Stock

QuickBooks Online currently does not directly support printing checks on blank check stock. It requires pre-printed check stock with the routing and account number already on the sheet. QuickBooks Desktop supports blank stock printing through compatible third-party add-ons. If you use QuickBooks Online, your refill order must be pre-printed stock rather than blank stock.


Starting Check Number for a Refill Order

The starting check number for a refill order should be the check number immediately following the last check in your current box. If your current box contains checks numbered 2001 through 2500 and you have used through check 2387, your next refill should start at check 2388.

In practice, many businesses place the refill order when they reach approximately the last 50 to 100 checks in the current box, choosing a starting number for the refill that they will reach just as the current box runs out. This overlap buffer prevents running completely out of checks before the refill arrives.

If you changed account numbers since your last order (because you closed a compromised account, for example), the starting check number can reset to any number you choose since the new account number distinguishes the new checks from the old ones. Many businesses restart at a round number like 1001 or 5001 when opening a new account, which makes it immediately obvious when looking at a check which account it belongs to.

For more detail on starting check number selection in specific scenarios, including after a lost checkbook, see our lost checks and replacements guide.


When to Reorder: How to Know You Are Running Low

Running completely out of business checks creates a payment workflow disruption that takes 3 to 5 business days to resolve once a refill order is placed. The right time to reorder is when you reach a reorder trigger point, not when you have used the last check.

For most businesses, a reorder trigger of 50 to 100 remaining checks in the current box is appropriate. This gives enough buffer for the 3-to-5-business-day production and delivery window. Some businesses set their trigger at the second-to-last pad in a multi-pad order, which gives a more visible physical indicator (opening the last pad is the reorder signal).

High-volume check writers (businesses writing 100 or more checks per week) should carry one full box in reserve and reorder when the reserve box is opened. This double-buffer approach prevents any disruption even if delivery takes slightly longer than the standard window.

For seasonal businesses with check volume peaks, reorder before the peak season begins rather than during it. Check production timelines stay at 3 to 5 business days during peak periods, but shipping carrier delays during holiday seasons can extend delivery unpredictably.


Matching Business Check Supplies

A business check operation requires more than check stock. The full supply kit includes envelopes, deposit slips, endorsement stamps, and storage for manual checks. Ordering the wrong accessories for your check format wastes money and creates operational problems.


Double-Window Check Envelopes

A double window envelope (double-window envelope) is sized and positioned to display the payee's address and your return address through the two windows when a computer business check is folded correctly. The window placement assumes the check on top format with the specific fold sequence that brings the payee address into alignment with the larger window. If you use check on bottom or a different fold orientation, the addresses may not align correctly with standard double-window envelopes.

Checkomatic's check envelopes are sized for standard computer business check on top format. When ordering, confirm your check format before selecting the envelope.


Business Deposit Slips

A deposit slip refill should be ordered at the same time as business checks because they carry the same routing and account number information. When you change account numbers, your deposit slips must also be updated. Ordering both on the same refill saves a separate order and ensures both arrive with the same account information.

Checkomatic's business deposit slips are pre-printed with your account details for accurate bank deposits.


Self-Inking Endorsement Stamps

An endorsement stamp applies the "For Deposit Only" restriction and your account information to every incoming check at deposit time. It eliminates hand-writing the endorsement on each check and ensures every check is restrictively endorsed (reducing fraud risk if a check is lost or stolen between receipt and deposit). The endorsement stamp should carry your current account number; if you change accounts, the stamp needs updating.

Checkomatic's self-inking endorsement stamps are customized with your business name and account details.


7-Ring Check Binders for Manual Formats

A manual check refill in the 3-on-a-page format requires a 7-ring binder for organized desk storage. The seven rings secure full-size check pages at more hold points than a standard 3-ring binder, preventing page shift during handwriting. 7-ring binder refill: if your manual check pads are running low, check whether your binder is also showing wear; binders typically last several years with regular use but the ring mechanism and cover eventually need replacement.

Checkomatic's 7-ring check binder is compatible with all Checkomatic manual business check formats.


Envelope Matching by Check Format

This is the detail that creates the most operational friction when businesses order check supplies without thinking through format compatibility. The standard double-window check envelope is designed for check on top format. Here is how to match envelopes to format.

Check on top format (the most common) folds into a standard double-window envelope with the payee address visible in the larger bottom window and your return address visible in the smaller upper window. The fold is: fold the bottom third up, then fold the top third down over it. This brings the payee address on the bottom voucher into the window position.

Check in middle format has the check in the center of the sheet, so the standard fold sequence does not bring any address into a window-appropriate position. Businesses using check in middle format often use envelopes without windows and print or handwrite the payee address on the envelope, or use address labels.

Check on bottom format similarly does not match standard double-window envelopes because the address field position differs from check on top. Confirm your envelope selection with your specific check format before ordering.

3-on-a-page checks produce wallet-size checks after cutting. Wallet-size business checks use standard business-size envelopes rather than the larger double-window format.


The Complete Business Check Supply Kit

Here is the full list of supplies a business check operation should maintain. Ordering these together on a coordinated refill schedule prevents running out of any single supply during a check run.


  • Pre-printed business check refills in your accounting software's format (voucher/check on top, check in middle, check on bottom, 3-on-a-page, or QuickBooks-specific)
  • Double-window check envelopes matched to your check format
  • Business deposit slips with current account information
  • Self-inking endorsement stamp with current account information
  • 7-ring check binder if you use manual 3-on-a-page format
  • Form leaders if you print 3-on-a-page computer checks with QuickBooks


Reviewing this full kit at each refill order prevents the situation where checks arrive but the matching envelopes or deposit slips have also run out simultaneously. A practical approach: set a master refill calendar that schedules all six supply categories together, even if individual items need refilling at different intervals.


Why Order Business Check Refills From Checkomatic

Checkomatic has manufactured business and personal checks from Monroe, NY (Monroe NY) since 1997. As an in-house check manufacturer, Checkomatic produces every business check format in-house at the Checkomatic facility with no reseller step and no handling fee added at checkout.


Every Business Check Format Available

Checkomatic stocks refill-compatible versions of every standard business check format: check on top, check in middle, check on bottom, 3-on-a-page, QuickBooks checks, manual AP checks, manual payroll checks, multi-purpose checks, compact deskbook checks, pocket checks, and blank check stock.


ABA-Compliant Security Paper on Every Order

Every Checkomatic business check refill ships on ABA-compliant check stock (ABA compliant) security paper with all six standard fraud deterrent features at the base price: chemically reactive paper, genuine watermark, microprinting, heat-sensitive ink, void pantograph, and UV fluorescent fibers. The CPSA padlock on Checkomatic's ordering pages confirms CPSA certification.


Free Logo Printing on Every Refill Order

Free logo checks (free black and white logo printing) are included on every business check refill order. Color logo printing is available for a small additional per-order charge. No setup fee applies on refill orders. If your logo has changed since the previous order, submit the updated logo file at checkout and a new digital proof will be generated for approval before production.


3-to-5-Business-Day Standard Turnaround

Standard business check refill orders ship within 3 to 5 business days from digital proof approval. Rush delivery is available at checkout for businesses that need checks faster. The digital proof step confirms your company information, logo, starting check number, and format before any paper is committed to production.


Complete Accessory Range in One Order

Order your check refills and check envelope refill (matching accessories) in a single Checkomatic order: double-window check envelopes, deposit slips, endorsement stamps, and 7-ring binders all ship from the same Monroe, NY facility.

Start your business check refill order at checkomatic.com. For guidance on matching your check format to your accounting software settings, see our business checks and payroll guide. For a comparison of voucher vs wallet check formats specific to QuickBooks, see our check types guide.


The Short Version on Business Check and Voucher Refill Supplies

A business check refill is a new order of the same check format with the next sequential check number as the starting point. Voucher checks (check on top, middle, or bottom) use one sheet per check with attached payment stubs for remittance data. 3-on-a-page gives three checks per sheet with no stubs. Manual checks are handwritten. Blank stock requires a MICR printer.

Match the refill format to your accounting software's print template setting. QuickBooks uses voucher (check on top) or standard (3-on-a-page) settings. Sage 50 typically uses check in middle. Order accessories that match your format: double-window envelopes for check on top, 7-ring binders for manual checks, deposit slips and endorsement stamps for every account.

Reorder at 50 to 100 remaining checks, not when you run out. At Checkomatic's standard 3-to-5-business-day turnaround, a well-timed refill arrives before the current supply is exhausted.


Frequently Asked Questions


What is a voucher check refill?

A voucher check refill is a new order of pre-printed business check stock that continues an existing check sequence. A voucher check is an 8.5-by-11-inch sheet with the check in the top third and two detachable voucher stubs in the lower two thirds. The stubs carry payment detail fields (invoice numbers, amounts, dates) for accounting records. When your current box runs out, you order a refill with the same company information, format, and accounting software compatibility, with a new starting check number that continues sequentially from your last check. Every other aspect of the refill is identical to the original order.


How many checks come in a box of business voucher checks?

For computer business checks with one check per sheet (check on top, check in middle, check on bottom), a standard box contains 250 to 500 sheets, giving 250 to 500 checks per box. For 3-on-a-page checks, a 500-sheet box gives 1,500 checks. For manual business checks in 3-on-a-page format, pads typically contain 25 pages each with 3 checks, giving 75 checks per pad. A 4-pad refill order provides 300 manual checks. The right quantity for your refill depends on your monthly check volume and how long you want each box to last before the next reorder.


What is the difference between a pre-printed business check refill and blank check stock?

A pre-printed check refill arrives with your company name, address, logo, routing number, and account number already printed on each sheet. Your accounting software prints only the variable data (payee, amount, date, check number). A standard laser or inkjet printer is sufficient. Blank check stock has no pre-printed information; a MICR-capable printer prints all check data including the MICR line at print time. Blank stock works with multiple bank accounts from a single supply box, making it cost-effective for high-volume or multi-account operations. Pre-printed refills are simpler and sufficient for most small and medium businesses.


Are refill business checks compatible with QuickBooks?

Yes, as long as the check format matches the QuickBooks print template. QuickBooks supports three formats: voucher (check on top), standard (3 checks per page), and wallet (personal-size). Your refill must match the format setting in QuickBooks under File, then Printer Setup, then Check. Checkomatic's QuickBooks-compatible checks are formatted and tested for QuickBooks Desktop and Online. QuickBooks does not require its own brand of checks; compatible third-party checks from CPSA-certified manufacturers like Checkomatic work with any QuickBooks version.


What business check supplies should I reorder along with my checks?

The complete set of business check supplies to reorder alongside check refills includes: double-window check envelopes matched to your check format (the standard design fits check on top format with correct fold sequence); business deposit slips pre-printed with your current account information; self-inking endorsement stamps customized with your account details; and a 7-ring check binder if you use manual 3-on-a-page checks. Form leaders are also needed if you print 3-on-a-page computer checks and need to feed partial sheets through your printer. Ordering all of these on a coordinated refill schedule prevents running out of any single supply at a critical time.

Jul 22, 2026

Top Checks: What the Check on Top Format Is and Why Most Businesses Choose It


What Are Top Checks

Top checks are business checks in which the negotiable check portion sits at the top of the page. On a standard 8.5 x 11 inch letter-size sheet, the check occupies the top third (roughly 3.5 inches tall). The remaining two-thirds of the page holds two detachable voucher stubs separated from the check by perforations.

The term top checks refers to the position of the check on the page. It is the same product sold under several different names depending on the supplier and the accounting software involved. Top checks are also called:

  • Check on top checks
  • Check-on-top format
  • Voucher checks (because of the two stubs)
  • Top check format
  • Computer checks on top
  • Laser checks on top

All these names describe the same thing: a letter-size business check sheet with the check at the top and two perforated stubs below. When suppliers or accounting software documentation refer to the "Voucher" check format, they mean top checks. QuickBooks Desktop calls this format "Voucher" in its Printer Setup menu. QuickBooks Online shows a picture of the layout in its Print Setup screen without using a name, but the template shows the check at the top.

Top checks are the most widely manufactured and most widely ordered business check format in the United States. Checkomatic's top business checks product line is one of the highest-volume items in the catalog. For the full product listing, see business checks on top.

Picture for category Manual Business Checks


How the Top Check Page Layout Works

A top check page has three distinct sections from top to bottom, each separated by a perforation line that allows clean tearing.


Section 1: The Check (Top Third)

The check itself occupies the top 3.5 inches of the 8.5 x 11 page. It contains all the required legal elements of a business check: your company name and address (pre-printed), the bank name (pre-printed), the date field, the Pay to the Order Of payee line, the numerical dollar amount box, the written dollar amount line, the memo field, and the signature line. The MICR line at the very bottom of the check section carries your routing number, account number, and check number encoded in magnetic ink.

When you print a top check from QuickBooks or another accounting platform, the software fills in the date, payee name, dollar amount, and memo. Your pre-printed company information and MICR line are already on the check from the manufacturer. You sign the printed check and it is ready.


Section 2: First Voucher Stub (Middle Third)

The first voucher stub sits immediately below the check, separated by a perforation. It carries the same payment information shown on the check plus additional detail fields: payee name, check number, date, amount, invoice number, payment description, and any account codes your accounting software assigns. This stub goes to the payee along with the check. The vendor or employee tears off the check from the top and keeps the stub as their payment confirmation and receipt.


Section 3: Second Voucher Stub (Bottom Third)

The second stub is identical in layout to the first but stays with the paying business after the check and the first stub are torn off and mailed. It serves as the company's paper record of the payment, filed in the AP folder or payroll records alongside the original invoice or timesheet. The second stub is what allows physical paper-based bookkeeping to function without relying entirely on the accounting software to retain every payment detail.


Research from CHAX Software indicates that top checks hold approximately 65 percent of the business check market. Middle checks hold about 25 percent and bottom checks roughly 10 percent. This distribution is not random. It is driven almost entirely by one factor: QuickBooks.

QuickBooks is the dominant small business accounting platform in the United States. According to Intuit's own data, QuickBooks serves over 7 million small business customers. QuickBooks Desktop and QuickBooks Online both default to the Voucher check style, which is the top check format, without requiring the user to make any configuration choice. When a QuickBooks user opens the check printing dialog for the first time and prints a check, they are automatically using top check format.

The result is that the overwhelming majority of QuickBooks users who need check stock order top checks. Most of them never change their software's check format setting. This creates a self-reinforcing cycle: QuickBooks defaults to top format, most users keep the default, most check orders are for top format, suppliers stock top checks in the widest range of quantities and colors, and the format becomes even more standard over time.

A secondary driver is the visual advantage of top checks when handling a payment batch. When a stack of 30 printed top checks sits on a desk for signing, the check portion is visible at the top of each sheet without shuffling through the stack. Signing is faster because the signature line is in a consistent, predictable position on every sheet. For middle checks, the signature line is in the center of the page. For bottom checks, it is at the bottom. Top checks minimize the physical effort of reviewing and signing a batch.


Top Checks vs Middle Checks vs Bottom Checks: The Full Comparison

FeatureTop ChecksMiddle ChecksBottom Checks
Check positionTop third of pageCenter of pageBottom third of page
Stub positionTwo stubs below checkOne stub above, one belowTwo stubs above check
Market share~65%~25%~10%
Primary softwareQuickBooks, Xero, Quicken, MYOB, Rent ManagerSage 50, Peachtree, Deltek, SoftproParadox, custom healthcare software
Primary industriesGeneral business, retail, services, payrollConstruction, real estate, property managementHealthcare, medical practices
Signing visibilitySignature line immediately visible at topSignature line in center requires more handlingSignature line at bottom of stack
Payee stub deliveryPayee gets top check torn off and middle stubPayee gets center check with both stubs nearbyPayee gets bottom check
Default in QuickBooksYes (Voucher format)NoNo
Default in XeroYesNoNo
Product availabilityWidest selectionModerate selectionLimited selection
Checkomatic availabilityYes , full rangeYesYes
Security featuresFull CPSA-certified setFull CPSA-certified setFull CPSA-certified set
Free logo printingYes (Checkomatic)Yes (Checkomatic)Yes (Checkomatic)
Best first choice?Yes, if software is unknownOnly if software requires itOnly if software requires it

The bottom line on format selection: if you do not know which format your accounting software uses and do not want to look it up, order top checks. Top checks are the safest default because they are correct for the majority of businesses and the majority of accounting software configurations. The only reason to order middle or bottom checks is if you have confirmed that your specific software version requires one of those layouts.


Which Accounting Software Uses Top Check Format

Top checks match the default print template in the following accounting platforms. This list is not exhaustive but covers the most widely used business software in the United States.

Accounting SoftwareDefault FormatQuickBooks-Style Setting
QuickBooks Desktop (Pro, Premier, Enterprise, Accountant)Top checks (Voucher)Voucher in Printer Setup
QuickBooks OnlineTop checks (Voucher)Voucher in Print Setup
XeroTop checksStandard US layout
MYOBTop checksQuickBooks-equivalent layout
Quicken BusinessTop checksVoucher equivalent
Rent ManagerTop checksTop format
NetSuiteTop checksStandard US AP format
FreshBooksTop checksStandard US layout
WaveTop checksStandard voucher
Sage IntacctTop checksStandard voucher

Software that defaults to middle check format instead: Sage 50 (formerly Peachtree), Sage 300, Deltek, TSS, Softpro, Landtech. Software that may default to bottom format: Paradox, some healthcare billing systems.

If you are uncertain which format your software uses, the fastest approach is to run a test print on plain paper from within your accounting software's check printing dialog, then hold the printed sheet against a blank top check to see if the fields align. In QuickBooks, the check style setting is at File, Printer Setup, Form Name: Check, Check Style. If it says Voucher, top checks are correct for your setup.

For QuickBooks-specific check selection guidance including how the three QuickBooks formats differ, see our QuickBooks-compatible checks guide.

Quickbooks® Check on Top


Top Checks for Payroll

Top checks are the recommended format for payroll in any business running QuickBooks Payroll or a similar QuickBooks-integrated payroll workflow. The reason is structural: payroll checks need to give employees a pay stub showing gross pay, individual deductions, and net pay. The two stubs on a top check provide that space.

When you run a payroll batch in QuickBooks and select the check printing option, the software fills in each employee's check with their net pay amount and date. The voucher stubs carry the detailed breakdown: gross wages, federal income tax withheld, state tax withheld, Social Security tax, Medicare tax, any voluntary deductions (health insurance, retirement, garnishments), and net pay. The employee tears off the check portion and keeps the middle stub as their pay stub. Your payroll file retains the bottom stub.

Most US states have pay stub laws that require employers to provide written or electronic itemization of deductions when issuing payroll. Top checks in voucher format satisfy the written pay stub requirement because the stub is physically attached to the check at the point of payment. The employee receives both simultaneously without any additional mailing or printing step.

For the complete payroll check guide including state pay stub requirements and format options for different payroll software, see our business checks for payroll guide.


Top Checks for Accounts Payable

For accounts payable, top checks provide vendors with immediate payment documentation. When a vendor receives a top check mailing, they see the check at the top (which they cash or deposit) and the middle stub beneath it (which tells them which invoice was paid and for what amount). Vendors who handle multiple clients find this format efficient because they do not need to contact the paying company to understand what each payment covers.

The second stub in your records closes the loop on the AP side. Your bookkeeper can pull the bottom stub from the payment file and match it to the original invoice and purchase order without logging into QuickBooks. During an external audit, physical stubs in a folder serve as documentary evidence of each payment even if the accounting software is temporarily unavailable.

Industries where top checks are particularly standard for AP include:

  • Retail and food service paying weekly vendor invoices
  • Professional services firms paying subcontractors and supplier invoices
  • Nonprofits maintaining paper audit trails for grant compliance
  • Property management paying maintenance and contractor invoices
  • Small manufacturing paying materials suppliers


What Information Goes on the Voucher Stubs of Top Checks

Your accounting software fills in the stub fields automatically when you print top checks from a payment run. The specific fields printed on each stub depend on what your software captures and what your check template is configured to display. Common stub fields for accounts payable top checks include:

  • Payee business name
  • Check date
  • Check number
  • Invoice number or reference number
  • Invoice date
  • Amount paid on this check
  • Discount taken (if early payment discount applies)
  • Account code or expense category
  • Description or memo

For payroll top checks, the stub fields include employee-specific information:

  • Employee name
  • Pay period start and end dates
  • Gross wages
  • Federal income tax withheld
  • State income tax withheld (if applicable)
  • Social Security tax (FICA)
  • Medicare tax
  • Additional voluntary deductions (health insurance, 401k, FSA, garnishments)
  • Net pay
  • Year-to-date totals

QuickBooks automatically formats payroll stub fields when you print payroll checks in Voucher (top check) style. The layout is preset to match the stub area of a standard top check.


Security Features on Top Checks

Top checks carry the same security features as any other professional business check format. The position of the check on the page (top, middle, or bottom) does not affect which security features the paper includes. What matters is the manufacturer and the security level you choose when ordering.

Checkomatic includes six CPSA-certified security features on every top check order at base price.


Chemically Sensitive Paper

The check paper contains chemical compounds that react visibly and permanently when contacted by solvents such as acetone, bleach, or alcohol-based cleaners used in check washing fraud. A washing attempt on a Checkomatic top check produces irreversible staining that cannot be concealed or overprinted. This is the most important security feature for top checks specifically because the payee name and dollar amount fields printed by your accounting software are prime targets for check washing.


Microprinting

Text printed at under one point size runs along the signature line of every top check. To the naked eye it looks like a solid decorative line. Under magnification it reads as text. When a top check is photocopied or scanned, the microprinting degrades to an unreadable smear, immediately identifying any copy as non-original.


Void Pantograph

A hidden background pattern causes the word VOID to appear prominently across the face of the check on any photocopy or digital scan. The original top check shows no VOID marking under normal lighting. Any attempt to reproduce the check by copying or scanning reveals it instantly.


UV Fluorescent Fibers

Fibers embedded in the check paper during manufacturing glow under ultraviolet light. Bank authentication equipment uses UV scanners to verify genuine check stock. These fibers cannot be replicated by any standard printing process because they are in the paper fiber structure, not printed on the surface.


Heat-Sensitive Ink

A thermochromic icon on the face of the top check disappears when pressed with a finger and returns when it cools. Genuine top checks respond to heat. Photocopies do not. Bank tellers and business owners can verify top check authenticity in seconds without any equipment.


Pre-Encoded MICR Line

The MICR line at the bottom of the check portion on every Checkomatic top check is pre-encoded using ANSI-certified magnetic iron oxide toner. Bank reader-sorter machines detect this line magnetically. Counterfeit top checks printed in standard toner produce no magnetic signal where one is expected, causing immediate rejection.

For a complete technical explanation of every security feature and the fraud types each one defends against, see our business check security features guide.


How to Set Up Top Checks in QuickBooks Desktop

QuickBooks Desktop is already configured for top checks by default. The steps below confirm that setting and walk through the alignment test.

  1. Open Printer Setup: Go to File in the top menu, then select Printer Setup. In the Form Name dropdown, select Check or Paycheck. This tells QuickBooks you are configuring the check printing template.
  2. Verify the Check Style: Under Check Style, confirm the Voucher radio button is selected. Voucher is the top check setting. If Standard or Wallet is selected instead, click Voucher.
  3. Run the Alignment Test: Click the Align button. QuickBooks generates a sample check layout. Print it on plain paper. Hold the printed test against a blank top check and verify that the date field, payee line, amount box, written amount line, memo field, and stub fields all align correctly with the pre-printed positions on the check stock.
  4. Adjust if Needed: If any field is off, the alignment dialog shows two fields: vertical (negative moves printing down, positive moves it up) and horizontal (negative moves left, positive moves right). Adjust in 0.05 to 0.10 inch increments and reprint the test. Checkomatic top checks typically require 0.1 inch or less of adjustment because the check dimensions are manufactured to match QuickBooks's default print template.
  5. Print Checks: Go to Banking, then Write Checks or Pay Bills, then print. For batch printing, go to File, Print Forms, Checks, select the account and checks to print, click OK, load top check stock in the printer, and click Print.


How to Set Up Top Checks in QuickBooks Online

QuickBooks Online prints top checks through the browser, which introduces margin and scaling settings that must be configured correctly before printing on real top check stock.

  1. Open Print Checks Setup: Click the gear icon in QuickBooks Online. Select Print Checks. Click Print Setup.
  2. Select the Voucher Template: QuickBooks Online shows two template options with visual previews. Select the Voucher option, which shows the check at the top of the page with two stubs below. This is the top check template.
  3. Run the Alignment Sample: Click View Preview and Print Sample. Print the sample on plain paper. Hold the plain paper against a blank top check to check alignment.
  4. Adjust if Needed: If the alignment is off, click No, Continue Setup once. Then click No, Continue Setup a second time. This second click is the step most users miss. It opens the fine-tuning alignment grid where you can drag to adjust the print position in precise increments.
  5. Set Browser Print Margins to Zero: In Google Chrome, press Control P or Command P to open print settings. Click More Settings. Under Margins, select None. Set Scale to 100 percent and uncheck Fit to Page. These settings apply at the browser level and override the QuickBooks layout if left at their defaults.
  6. For Firefox, Edge, or Safari: Save the top check print job as a PDF from QuickBooks Online and then print it through Adobe Acrobat Reader. In Acrobat Reader, choose Print, then under Page Sizing and Handling, select Actual Size rather than Fit. This bypasses the browser margin problem entirely.


Fixing Top Check Alignment Problems

Most top check alignment problems fall into one of four categories.


Wrong Check Style Selected

If the printed output is shifted by several inches or completely misses the check and lands on the stub area, the most likely cause is the wrong Check Style selected in QuickBooks. Confirm that Voucher is selected in File, Printer Setup (Desktop) or in Print Setup (Online). Middle check stock loaded in the printer while QuickBooks is set to Voucher will not print correctly. Top check stock set to Standard will not print correctly either.


Browser Margins Not Set to Zero (QuickBooks Online Only)

If the output is shifted by a small but consistent amount (typically less than half an inch in one direction), browser margin settings are usually responsible. In Chrome, set Margins to None and Scale to 100 percent in the print dialog. For other browsers, use Adobe Acrobat Reader with Actual Size printing as the solution.


Printer Driver Scaling

Some printers apply their own scaling at the driver level independently of QuickBooks and browser settings. Open your printer's properties from Windows Settings or macOS System Settings, find the scaling or paper section, and confirm Print Scale is 100 percent.


Wrong Paper Size

Top checks require letter-size paper (8.5 x 11 inches). If your printer defaults to A4 or legal, the check layout shifts significantly. Confirm the paper size setting in both QuickBooks Printer Setup and your printer driver settings. Load letter-size top check stock only in printers confirmed to be set to letter size.


How to Order Top Checks from Checkomatic

Ordering top checks from Checkomatic requires four pieces of information: your business name and address (printed on the check face), your 9-digit ABA routing number, your checking account number, and your starting check number.

The routing number is the nine-digit number at the bottom left of any existing check. It identifies your bank for the MICR encoding. Before ordering, confirm your routing number by looking at an existing check rather than using an online lookup tool. For a detailed explanation of routing numbers and how to verify yours, see our ABA routing number guide and our MICR line explained guide.

During the order, you can choose from over 20 background color options, add a black-and-white logo at no extra charge, or upgrade to full-color logo printing. An extra signature line is available for businesses requiring dual authorization on checks. Quantities range from 50 to 10,000 top checks per order.

Standard orders ship in 3 to 5 business days from Checkomatic's Monroe, NY facility. Rush production and overnight shipping options are available. Every order includes a digital proof review where you verify your business information before printing begins. Browse the complete top check catalog at business checks on top, the full computer checks catalog, or QuickBooks checks if you specifically need QuickBooks-compatible top check stock. The full range of business checks including all formats is also available.

Computer Checks on Bottom


What Customers Say About Checkomatic

All reviews below are published on checkomatic.com and reproduced verbatim. Source: checkomatic.com/quickbooks-starter-pack, 4.5 stars from 166 verified customer reviews.

"Been with them for 15 years. Always reliable, always good quality, good service. What more can you ask for?"

ATV Inc. | ★★★★★ 5/5 | April 5, 2024 | Source: checkomatic.com/quickbooks-starter-pack

"We use CheckoMatic for all of our check needs! They have great prices and we receive our products in a timely manner!"

CG's Tax Service | ★★★★★ 5/5 | September 18, 2024 | Source: checkomatic.com/quickbooks-starter-pack

"First time ordering and I am super impressed with the quality of the checks. No issues with delivery. I will be ordering again!"

TClinton | ★★★★★ 5/5 | April 9, 2025 | Source: checkomatic.com/quickbooks-starter-pack

"I got 500 checks for less than half of what the bank wanted for 200!"

VVA Voucher Checks (Vietnam Veterans of America) | ★★★★★ 5/5 | July 6, 2024 | Source: checkomatic.com/quickbooks-starter-pack

"ASJ Wilson Construction has been a client of Checkomatic for some years now and they've never disappointed this company. Thank you Checkomatic for all that you do."

ASJ Wilson Construction | ★★★★★ 5/5 | June 6, 2024 | Source: checkomatic.com/quickbooks-starter-pack

"Affordable and efficient. My go-to business check printer."

Doe | ★★★★★ 5/5 | January 24, 2025 | Source: checkomatic.com/quickbooks-starter-pack

Read the full review set at checkomatic/business-checks.


Why Choose Checkomatic for Top Checks

In-House Manufacturing in Monroe, NY Since 1997

All top checks are printed at Checkomatic's own Monroe, NY facility. Your banking information never passes through third-party print vendors. Every top check order is handled by the same manufacturing team from proof approval through MICR verification and shipping.


Six Security Features Included at Base Price

Chemically sensitive paper, microprinting, void pantograph, UV fluorescent fibers, heat-sensitive ink, and pre-encoded MICR are all standard on every top check order. No tier upgrade is required to get meaningful fraud protection.


Pricing 50 to 70 Percent Below Bank Retail

Banks issue top checks through batched third-party printers with retail markup. Checkomatic's direct-manufacturer pricing eliminates that overhead. One verified customer received 500 checks for less than half of what their bank charged for 200 checks.


Full QuickBooks Compatibility

Checkomatic top checks are manufactured to match QuickBooks's default Voucher print template. The alignment adjustment most users need is 0.1 inch or less after the initial test print. Compatible with QuickBooks Desktop Pro, Premier, Enterprise, and Accountant; QuickBooks Online; Xero; MYOB; Quicken; Rent Manager; NetSuite; and over 500 other accounting platforms.


Free Logo Printing on Every Order

Black-and-white logo printing is included at no charge on every top check order regardless of quantity. Full-color logo printing is available as an upgrade.


3 to 5 Business Day Standard Turnaround

Top check orders ship in 3 to 5 business days from Monroe, NY. Rush options available for payroll deadlines. Bank-issued top checks typically take 7 to 14 business days.


MICR Routing Number Pre-Verification

Every routing number is verified against the Federal Reserve E-Payments Routing Directory before any top check order goes to print. This catches transposed digits and outdated routing numbers before they produce unusable checks.


Quick Summary: What Are Top Checks


Top checks reference guide: top checks definition, check on top vs middle vs bottom comparison, top checks accounting software compatibility, top checks accounts payable workflow, voucher checks check on top format, MICR top checks with pre-encoded magnetic routing line, ABA compliant top checks meeting Federal Reserve standards, top checks security features including six CPSA certified protections, check on top QuickBooks setup (File, Printer Setup, Check Style: Voucher), check on top Xero standard US layout, top checks market share 65 percent of US business checks,

top checks Monroe NY manufactured by Checkomatic since 1997, top checks CPSA certified with six security features at base price, top checks free logo printing black and white on every order, two stub check on top with one stub to payee and one retained by payer, perforated top checks with clean tear lines between check and both stubs, top checks letter size 8.5 x 11 inch standard paper, how to print top checks QuickBooks through File Printer Setup Voucher style, top checks alignment test on plain paper before loading real check stock, top checks best for payroll because QuickBooks Payroll defaults to Voucher format.

Top checks are business checks with the check portion at the top third of a letter-size 8.5 x 11 page and two detachable voucher stubs below. They are also called check on top checks, check-on-top format, or voucher checks. Top checks hold approximately 65 percent of the US business check market because they are the default format for QuickBooks, Xero, MYOB, Quicken, and most other major accounting platforms. Top check format differs from middle checks (check centered, used with Sage 50) and bottom checks (check at bottom, used with certain healthcare software) only in the position of the check on the page. The stubs carry payment detail for both payee and paying business records.

Top checks work for payroll (employee pay stubs showing gross pay, deductions, and net pay) and accounts payable (vendor remittance detail showing invoice numbers and amounts paid). Security features on top checks include chemically sensitive paper, microprinting, void pantograph, UV fluorescent fibers, heat-sensitive ink, and pre-encoded MICR. Top checks print in QuickBooks Desktop by selecting Voucher in File, Printer Setup, Form Name: Check.

Top checks print in QuickBooks Online by selecting the Voucher template in Settings, Print Checks, Print Setup, with browser margins set to None and Scale set to 100 percent. Checkomatic manufactures top checks at Monroe, NY, ships in 3 to 5 business days, includes six CPSA-certified security features at base price, and provides free black-and-white logo printing on every order.


Jul 21, 2026

Lost Checks and Replacements: What to Do Step by Step

Why Losing a Checkbook Is Urgent, Not Just Inconvenient

A lost checkbook is not like losing a credit card. A credit card number changes when the card is replaced, and your liability for unauthorized charges is capped at $50 under the Fair Credit Billing Act (usually waived under zero-liability policies). The card itself carries no banking credentials that expose your account beyond the card number.

A personal checkbook contains three pieces of information that together give anyone full access to your bank account: your ABA routing number, your account number, and your physical signature in the form of a signed check. Every single check in the pad has all three printed on it. The routing number exposed on a check gives anyone the bank identifier; the account number exposed gives account access. Beyond the signed checks, the blank checks can be completed by hand and signed with a forgery.

The routing number and account number alone are enough to initiate unauthorized ACH withdrawals from your account, which a stop payment on check numbers will not prevent. This is why multiple bank fraud departments, including BECU and Old National Bank, advise that a lost or stolen checkbook is treated as a compromised account requiring closure, not just a stop payment situation.

Speed matters. A check can be deposited and begin clearing within hours of being written. The sooner your bank knows the checkbook is missing, the more transactions can be stopped before they clear.


Misplaced, Lost in the Mail, or Stolen: Different Responses

The right response to losing checks depends on how you lost them. These three scenarios call for meaningfully different approaches.


Misplaced (Not Confirmed Lost)

The misplaced vs stolen distinction matters. If you cannot find your checkbook but are not sure it is truly gone (it might be in the car, at the office, or in a coat pocket), call your bank to put a temporary bank freeze account (freeze on check activity) while you search. A freeze prevents new checks from clearing without permanently closing the account. Give yourself a reasonable search window of 24 to 48 hours. If you find the checkbook, call the bank to lift the freeze. If you do not find it within that window, treat it as confirmed lost and move to account closure.


Checks Lost in the Mail

If you mailed a check and the recipient reports not receiving it, the check may be lost in the postal system or delivered to the wrong address. A stop payment on that specific check number is the right first move. This costs one stop payment fee ($20 to $35) and protects that specific transaction. You can then issue a replacement check for the same amount to the same payee. The risk is limited because only one check is missing, and its routing and account numbers are no more exposed than any check you have ever written to any payee.


Stolen Checkbook

A stolen checkbook is the most serious scenario. Someone has intentional possession of your checks and knows the account information. Account closure is strongly recommended. You should also file a police report, submit a fraud claim with your bank if any unauthorized checks have already cleared, report the theft to a check verification service, and monitor your account closely for both check fraud and ACH fraud. This is the scenario that requires the most steps and the most urgency.


Step 1: Call Your Bank Immediately

Your first call after discovering your checkbook is missing should be to your bank's fraud or customer service number. Do not wait to check online banking first or to search more thoroughly. Call while you search.

Tell the representative that your checkbook is missing and provide the last check number you used if you know it. This tells the bank which check numbers are still blank and at risk. The representative will outline your options, which typically include placing a freeze on check activity, placing stop payments on a range of check numbers, or initiating the process of closing the account and opening a new one.

Ask the representative to note the call date and time in your account record. This timestamp is important if you later dispute charges: your bank notification timeline affects your liability under UCC Article 4, which governs how banks handle forged checks and unauthorized transactions.

Most banks operate 24-hour fraud lines. If you discover the loss at night or on a weekend, call the after-hours fraud line rather than waiting for business hours. A check can be cashed or deposited at any time, and the clearing process does not observe banker's hours.


Step 2: Stop Payments or Close the Account

After notifying your bank, you and the bank representative need to decide between two courses of action: placing stop payments on the missing check numbers or closing the account entirely and opening a new one.


When Stop Payments Are Sufficient

Stop payments make sense when you lost a small number of specific checks (one or two individual checks, for example), when you are confident the loss was accidental rather than theft, and when you can identify the exact check numbers at risk. A stop payment order (covering a specific check number or range) prevents the bank from paying those specific check numbers if presented.

One important limitation: stop payments on check numbers protect only against the specific checks in the stopped range being cashed or deposited. They do not protect against ACH transactions initiated using your routing number and account number, which any check in your book exposes. If you misplaced a single check that you are fairly confident has not been stolen, a stop payment is adequate. If an entire checkbook is missing and there is any possibility of theft, account closure is the stronger protection.


When Account Closure Is the Right Choice

Close the account when an entire checkbook is missing or confirmed stolen, when you have lost track of which check numbers were blank in the missing book, when you cannot rule out intentional theft, or when your bank advises closure. Both BECU and Old National Bank, for example, treat any reported lost or stolen checkbook as a compromised account requiring closure.

Account closure eliminates the exposure permanently. Even if someone attempts to write a check from the stolen book or initiate an ACH payment using the old account number, the account no longer exists and the transaction will be rejected. The routing number printed on your old checks will still work for directing transactions to your bank, but the account number will be invalid.

The tradeoff is administrative: closing an account requires redirecting all direct deposits, automatic debits, linked accounts, and any outstanding authorized checks to the new account. This process (covered in Step 5) takes time and coordination, but it provides definitively stronger protection than stop payments alone for a full checkbook loss.


Stop Payment Costs, Duration, and UCC Rules

Stop payment fees at most US banks typically range from $20 to $35 per order, according to Bankrate, Experian, and multiple bank published fee schedules. The fee covers the bank's administrative cost of placing and monitoring the order. Some premium accounts or credit unions waive the fee. Online banks sometimes charge less than traditional branches for the same service.

The fee structure for a range stop is usually one fee regardless of how many check numbers fall within the range. If you are placing a stop on check numbers 1045 through 1120 (the blank checks in a lost 75-check pad), most banks treat this as a single range stop payment order at one fee rather than 75 individual fees. Confirm this with your bank, as policies vary.

Stop payment duration is governed by UCC 4-403, the Uniform Commercial Code section covering stop payment orders. Under UCC 4-403, an oral stop payment (14 days: the oral stop payment 14 days rule) order is effective for 14 calendar days. A written stop payment (6 months duration: the written stop payment 6 months rule) is effective for 6 months and can be renewed at the bank's option upon your written request, typically at another fee. After the 6-month written order expires, the bank may pay the check if presented. A permanently closed account avoids this renewal requirement entirely.

The CFPB confirms this: "Most states have laws that say if you make your stop-payment request, in writing, before the check has been completely processed, the check can't be cashed for six months. In some cases, the stop payment expires after one year."

The key timing constraint: a stop payment cannot be applied to a check that has already cleared. Once a check enters the clearing process and the funds have left your account, the bank cannot reverse it through a stop payment. This is why calling the bank quickly is essential. See our full guide to how checks clear at check types and terminology.


Identifying Which Check Numbers Are at Risk

When you call your bank, being able to identify which check numbers are at risk allows the bank to place a precise stop payment range and helps you account for all missing blanks. Here is how to reconstruct the check number range.

Find your most recent bank statement or online banking transaction history. Look for the highest check number that appears in your recent cleared transactions. That is the last check that has already cleared. The missing checks start from the next sequential number.

Your check register, if kept current, gives you the last check you wrote. If you use duplicate checks, the carbonless copy of the last written check shows its number. If you have neither, your check register or account statement is the next reference.

Count forward from that last known check number to determine how many blank checks were in the lost pad. A standard personal check pad contains 20 to 25 checks per pad, and a typical personal checkbook contains four to five pads, giving a total of 80 to 125 checks per checkbook order. Knowing the approximate number of missing blanks helps you set the upper bound of the stop payment range.

If you cannot establish the check number range, tell your bank the approximate last check number and ask them to place a broad range stop extending well beyond your likely current check number. Some banks can place an indefinite stop on all future check numbers above a given point until the account is closed or the stop is removed.


Step 3: File a Police Report if Stolen

If you know or suspect the checkbook was stolen rather than accidentally lost, file a police report. This step is specifically for theft situations, not for misplaced checkbooks.

A police report stolen checkbook filing serves several important functions. It establishes a documented date and record of the theft, which means any checks written from the stolen book after that date are clearly unauthorized. Banks require a police report number when you submit an affidavit of forgery to dispute unauthorized checks that have cleared. Check verification services use the police report information to flag your account as compromised. Merchants and collection agencies attempting to collect on fraudulent checks written from the stolen book need the police report number to understand the situation.

File the report at the police department in the jurisdiction where the theft occurred. For a stolen checkbook removed from your home or car, that is your local department. For a theft that occurred elsewhere, it is the department covering that location.

When filing, report the checkbook theft specifically. You do not need to list fraudulent activity from the theft at this stage; you report the theft of the checks themselves. If fraudulent activity later occurs, you file a separate fraud report referencing the original theft report number.


Step 4: Monitor Your Account for Unauthorized Activity

After notifying your bank and placing protections on the account, monitor your transaction history daily for at least two to four weeks. Look for checks that clear with numbers from the missing range, or for any ACH debits you did not authorize.

Log into online banking daily and review both cleared transactions and pending transactions. Pending items show transactions in process that have not yet settled; you may be able to dispute a pending unauthorized check before it fully clears. Once a transaction is posted and settled, reversing it requires a formal dispute process with your bank.

If you see any transaction you did not authorize, contact your bank's fraud department immediately with the check number, date, and amount. Do not wait until the end of the month. Timing matters for your UCC protections: many bank account agreements require you to report forged items within 30 days of the statement being made available, and UCC Article 4 bars claims made more than one year after the bank statement showing the fraudulent transaction.


Step 5: Redirect Automatic Debits and Direct Deposits

If you are closing the account, this step is the most time-consuming part of the process. Every automatic debit redirect, subscription redirect, direct deposit update, and linked bank account using the old account number needs to be updated to the new account number before you can fully close the old account.

Start by making a complete list of every recurring transaction that uses the old account number. Your bank statement from the past two to three months will show you every automatic debit and deposit. Common items to redirect include:


  • Payroll direct deposit (contact HR or your employer's payroll department)
  • Social Security, pension, or government benefit direct deposit
  • Mortgage or rent automatic payment
  • Utility automatic payments (electric, gas, water, phone, internet)
  • Insurance premium auto-pay
  • Subscription services (streaming, gym, software subscriptions)
  • Loan payments (auto loan, student loan, personal loan)
  • Linked savings accounts or investment account transfers
  • Any BECU-style pre-authorized debit arrangements


Contact each payee with your new account number and routing number (the routing number typically stays the same when you open a new account at the same bank). Do not close the old account until you have confirmed that every automatic debit has been redirected and any authorized outstanding checks have cleared. Leave enough funds in the old account to cover any authorized outstanding checks in transit. Any ACH redirect should also reference the new account number.

Payroll direct deposit redirection can take one to two pay cycles to process, so start that redirection immediately after opening the new account.


Step 6: Submit a Fraud Claim if Checks Have Already Cleared

Check fraud after loss is the most serious outcome. If you discover that unauthorized checks have already cleared your account before you could stop them, submit a formal fraud claim with your bank. The bank will require you to complete an affidavit of forgery, sometimes called a fraud affidavit. This is a signed sworn statement that you did not authorize the specific transactions.

The affidavit typically requires the check number, date, amount, and payee of each unauthorized check. Providing the police report number (if theft was involved) strengthens the claim. The bank investigates and, if it confirms the signature was forged and you were not negligent, it credits your account for the unauthorized amount under its obligations under UCC Article 4.

The timing rules matter: under UCC Article 4, you generally have one year from the date the bank statement was made available to report a forged check. Many bank account agreements impose a shorter 30-day reporting requirement. Review your account agreement for the specific deadline that applies to your account.

You are not responsible for debts created by fraudulent checks written on stolen checks. If a merchant or collection agency contacts you about a bounced or unpaid check from the stolen book, explain that the check was part of a theft and provide the police report number and your bank's fraud department contact information. You did not write that check and do not owe that debt.


Check Verification Services After a Checkbook Loss

A check verification service is a database that businesses use to evaluate whether to accept a check payment. Services like TeleCheck and Certegy maintain records of accounts with fraud histories, bounced check histories, and compromised account reports. When a business accepts a check and runs it through a verification service, it sees whether the account has any flags.

After a checkbook theft, you can report the theft to major check verification services to have your account flagged as compromised. This means that when a fraudster attempts to use a stolen check at a participating retailer, the verification service may decline the transaction before the check is accepted. This is an additional layer of protection beyond what your bank's stop payment orders provide.

ChexSystems is a different but related consumer reporting agency that tracks banking history including account closures, bounced checks, and fraud. If fraudulent checks are written on your stolen checkbook and result in unpaid items, these may be reported to ChexSystems and could affect your ability to open bank accounts in the future. If this happens, you can dispute the items with ChexSystems by providing documentation of the theft and fraud claim.


Using Positive Pay After a Lost Checkbook

Positive pay is a bank fraud prevention service typically offered to business checking accounts. It requires the account holder to submit an electronic file of all checks issued (check number, date, amount, and payee) before each check is presented for payment. The bank compares each incoming check against the positive pay file and flags mismatches for review.

Positive pay after loss is an option for businesses. Enrolling in positive pay after opening the new account adds a layer of verification that prevents unknown checks from clearing automatically. Any check presented that does not match a check on the positive pay file is held for the business to review and approve or reject.

Positive pay is not typically offered for personal accounts, but some banks offer a simplified version for sole proprietors or small businesses. If you run a business and write business checks regularly, the checkbook loss is a good occasion to ask your bank about positive pay enrollment as a going-forward protection measure.

Our guide to check fraud prevention, including how positive pay works in detail, is at check fraud prevention. For a full comparison of the security features built into ABA-compliant check paper that make individual checks harder to forge or alter, see our check stock paper guide.


Step 7: Order Replacement Checks

Once you have secured your account (whether through stop payments or account closure), you need a new supply of personal or business checks. This is the check reorder after loss step. Replacement check ordering follows the same process as a standard order.

If you closed the old account and opened a new one, order replacement checks with the new account number. Do not use the old account number; that account is now closed and any check with the old number will be rejected by the bank when presented.

If you placed stop payments and kept the same account, order replacement checks with the same routing number and account number. The replacement checks will have new check numbers starting above the range of the missing checks.

The information you need for any replacement check order is the same as for a standard check order: your nine-digit ABA routing number, your checking account number (new number if the account changed), the starting check number for the new order, and your name and address as you want them printed. Your routing number is on any existing check or available from your bank. For a full explanation of where to find these numbers, see our ABA routing numbers guide.

Checkomatic offers the full range of personal and business check formats for replacement orders with no minimum order quantity above a single box. Standard turnaround is 3 to 5 business days from digital proof approval, with rush delivery available if you need checks more quickly. Order at personal checks or business checks.


Choosing the Right Starting Check Number for Replacement Checks

This detail is not covered by any competitor guide, and it matters for preventing confusion and potential fraud after a loss.

If you are keeping the same account number (stop payment scenario, account not closed), choose a starting check number that skips well beyond the highest check number in the lost book. For example, if your lost checkbook contained checks 1045 through 1120 (75 blank checks), choose a starting number of 1200 or higher for your replacement order. This creates a clear gap between the at-risk range (1045 to 1120) and your new checks, which makes it immediately obvious if a check from the stopped range is presented.

If you chose a starting number of 1121 (the next sequential number after the lost book), there would be no visible gap between the stopped checks and the new ones. If your bank's stop payment record-keeping is imperfect or if someone presents a check in the middle of your stopped range, the sequential numbering makes it harder to spot the anomaly quickly.

If you closed the old account, the starting check number for the new account does not need to follow the old sequence. You can start at 101 or 1001 or any number you choose since the account number itself is different and the old checks cannot be confused with the new ones.


How Many Blank Checks Were in Your Lost Book

Knowing how many blank checks were in the lost checkbook helps you set an accurate stop payment range. How many checks in a checkbook: a standard personal check pad contains 20 to 25 checks per pad. A standard personal checkbook order from Checkomatic ships as four to five pads per box, giving 80 to 125 checks per box. If you ordered a single box and lost the entire checkbook, the missing blank check range spans approximately 80 to 125 check numbers.

If you had used some checks from the box before losing it, the number of blank checks at risk is lower. Use your check register or the carbonless copy of the last check (check number tracking) to identify the last check number used. Count from that number to the end of the pad sequence to get the number of blanks at risk.

Duplicate checks have 20 checks per pad (single checks have 25 per pad) because each position uses two pages instead of one. If you ordered duplicate checks, a four-pad box contains 80 checks rather than 100. The carbonless copies that remain in the pads (if you have any pads at home) can also help you reconstruct which numbers you had used before the loss.


Why Order Replacement Checks From Checkomatic

Checkomatic has manufactured personal and business checks from Monroe, NY (Monroe NY) since 1997. As an in-house check manufacturer, Checkomatic produces your replacement check order directly at the Checkomatic facility and shipped to you with no reseller step and no added handling fee.


Standard Replacement Order Process

Ordering replacement checks from Checkomatic follows the same process as any check order. Choose your format (standard personal checkbooks, top stub, deskset, or any business check format). Enter your routing number, the new account number if the account changed, and the starting check number for the replacement order. Review the digital proof before approving production. Standard orders ship within 3 to 5 business days from proof approval.


ABA-Compliant Security Paper on Every Order

Every Checkomatic ABA compliant replacement check ships on ABA-compliant security paper with six standard fraud deterrent features: chemically reactive paper, genuine watermark, microprinting, heat-sensitive ink, void pantograph, and UV fluorescent fibers. These check security features are the physical fraud protections that make replacement checks from Checkomatic harder to wash, counterfeit, or alter than checks on plain security paper. The CPSA padlock on Checkomatic's ordering pages confirms compliance.


Free Logo Printing on Every Order

Free black and white logo printing is included on every personal and business check replacement order. No setup fee. Color logo printing is available for a small additional per-order charge. If your previous checks had a logo, the replacement order can include it at no additional charge.


Rush Orders Available

If you need replacement checks quickly, rush delivery is available at checkout. Expedited shipping options can significantly reduce the time from order to delivery beyond the standard 3-to-5-business-day window. Contact Checkomatic's customer service for options if you need checks faster than standard delivery allows.

To place your replacement order, visit checkomatic.com. For personal check formats, start at personal checkbooks. For business check formats, start at business checks. For QuickBooks-compatible checks, see QuickBooks checks.


The Complete Lost Checkbook Action Plan

Here is the full sequence in order of priority:


  1. Call your bank immediately. Report the missing checkbook and ask for a freeze on check activity.
  2. Decide: stop payments or account closure. Lost single checks: stop payments on specific numbers. Lost entire checkbook or stolen: close the account.
  3. File a police report if stolen. Get a case number. You will need it for the fraud affidavit and to deal with merchants.
  4. Monitor your account daily for unauthorized check transactions and ACH debits.
  5. Redirect all automatic debits and direct deposits to the new account number if you closed the account.
  6. Submit a fraud claim and affidavit of forgery for any unauthorized checks that have already cleared.
  7. Report to check verification services (TeleCheck, Certegy) if the checkbook was stolen.
  8. Order replacement checks with the new account number (if account closed) or a higher starting check number (if account kept).


Frequently Asked Questions


What should I do first if I lose my checkbook?

Call your bank immediately. This is the most important first step and it should not wait. A lost checkbook exposes your ABA routing number, account number, name, and address to whoever finds or steals it. These are the same credentials needed to write fraudulent checks or initiate ACH withdrawals from your account. Your bank can freeze check activity, place a stop payment on the missing check numbers, or begin account closure. Call the bank's fraud line even if you are still searching for the checkbook; the bank can place a temporary freeze while you look, and you can cancel the freeze if you find the book.


How much does a stop payment on a check cost?

Stop payment fees typically range from $20 to $35 per stop payment order at most US banks. Some premium accounts and online banks waive or reduce this fee. For a lost checkbook with a range of missing check numbers, most banks will place a single range stop payment covering all consecutive check numbers in the missing book for one fee rather than a separate fee per check number. Confirm with your bank. An oral stop payment order under UCC 4-403 lasts 14 days; a written order lasts 6 months and must be renewed at another fee if the checks remain outstanding.


Should I close my account or just put a stop payment on lost checks?

If an entire checkbook is missing or was stolen, closing the account and opening a new one is the safer choice, as most bank fraud departments recommend. Stop payments cover specific check numbers for 6 months, but they do not protect against ACH transactions initiated using your routing number and account number (which every check exposes). Account closure makes the old account number invalid permanently. If you lost only one or two specific checks and are confident it was accidental, stop payments on those check numbers may be sufficient. For whole checkbook loss, account closure is the cleaner and more complete protection.


Do I need to file a police report for lost checks?

Filing a police report is necessary if the checkbook was stolen. It is optional if you cannot confirm theft versus accidental loss, but it is recommended any time you cannot rule out theft. A police report establishes a documented date and record of the theft, which means any checks written from the stolen book after that date are clearly unauthorized. Banks require the police report number when you submit an affidavit of forgery to dispute fraudulent checks that have cleared. Check verification services and merchants also use the report number. If the checkbook was simply misplaced and you find it, a police report was not needed.


How do I order replacement checks after losing my checkbook?

Order replacement checks with two adjustments from a standard check order. First, use the new account number if you closed the old account; if you kept the same account, use the original account number. Second, choose a starting check number higher than any check in the lost book. This avoids confusion between outstanding stopped checks and new checks. You need your ABA routing number, account number, and chosen starting check number. Checkomatic offers all personal and business check formats for replacement orders at checkomatic.com with a standard 3-to-5-business-day turnaround from digital proof approval and rush delivery options available.

Jul 21, 2026

How to Reorder Business Checks Online: Step-by-Step Guide


Reorder vs First-Time Order: What Is Different

Knowing how to reorder checks online correctly saves you time and avoids costly mistakes. A reorder is faster and simpler than a first-time check order in two specific ways. First, you do not need to submit a voided check for identity and account verification. That step was completed when you placed your original order. The printer already confirmed that your routing number and account number match an active bank account. Second, you know exactly which format, security level, and design you want because you have been using the previous batch.

If you already order QuickBooks checks from us, here is how to reorder your QuickBooks checks in a few steps.

Related guide: how to get business checks delivered fast.

The one thing that always changes when you reorder checks online is the starting check number. Every check in your batch has a unique sequential number printed in the upper right corner and encoded in the MICR line at the bottom. Your reorder needs to pick up where your last batch ends. Getting this number right is the most important step in the process.

Everything else, your routing number, account number, business name, address, logo, and check format, stays the same unless something in your business has changed. This guide covers both the standard reorder and the situations where something has changed.


Full color logo print example


What Information You Need Before You Start

When you know how to reorder checks online, this checklist becomes second nature. Have these five items ready before you begin the reorder form. The form to reorder checks online takes about 3 minutes to complete when everything is in front of you. Stopping mid-form to look up a routing number or check your last order number adds time and increases the chance of a typo.

 
Reorder Checklist:
  • Business name and address exactly as they appear on your bank account. This must match your bank's records.
  • ABA routing number , the 9-digit number at the bottom left of any existing check. Do not use an online routing number lookup; use an existing check or your bank's verified list.
  • Checking account number , the number at the bottom of your check, to the right of the routing number and before the check number.
  • Starting check number , one above the highest check number you have already used. See the next section for how to find this.
  • Logo file (optional) , only if you want to add or update your logo. PNG, JPG, or vector formats accepted. Black-and-white logo printing is free on every Checkomatic order.

Unlike a first-time order, you do not need to submit a voided check for verification on a standard reorder from the same supplier. Your account information was verified on the first order. If you are switching suppliers, the new printer will require a voided check or bank verification letter before production starts.

For an explanation of how to read the numbers at the bottom of your check, including the routing number, account number, and check number positions, see our ABA routing number guide.


How to Find Your Starting Check Number

The starting check number is the most common point of confusion when businesses reorder checks online. Here is how to find it in four different situations.


Method 1: QuickBooks Desktop: Finding Your Number Before You Reorder Checks Online

Go to Banking in the top menu, then select Use Register. Select your business checking account. Click the column headers to sort by check number descending. The highest check number in the register is the last check you wrote. Your starting number for the new order is one above that number.

Example: if your register shows the highest check number is 4623, your new order starts at 4624. If your remaining stock of unwritten checks runs up to 4750, you have two choices: start at 4624 (meaning you will overlap with unwritten stock still in your drawer) or start at 4751 (finish the current stock first, then begin the new batch). Most bookkeepers prefer starting where the old stock ends, so they never have two batches in use at the same time.


Method 2: QuickBooks Online

In QuickBooks Online, go to Reports in the left navigation menu. Search for Check Detail or run a Transaction List by Account report for your checking account. Filter by transaction type: Check. Sort by check number in descending order. The number at the top is your highest issued check number. Add one to get your starting number.


Method 3: Manual Check Register (No Accounting Software)

If you use a manual check register ledger or the stub in your manual check binder, find the last entry and read the check number from the left column or the stub. That is the last check you wrote. Add one for your starting number.

If your stubs are incomplete or some checks were written without recording the stub, look at the physical checks remaining in your binder. The last check in the sequence shows the highest pre-printed number. If you have written through check 2147 and the last check in your binder is 2200, your starting number for the new order is 2201.


Method 4: Your Previous Order Confirmation

Your Checkomatic order confirmation email includes the starting check number from your previous order and the quantity. If you ordered 500 checks starting at 1001, your batch runs from 1001 to 1500. If you have used most of them, your starting number for the next order is 1501. This method works well when you use checks sequentially and rarely skip or void numbers.


When to Reorder: The 25-Check Rule

The practical rule for how to reorder checks online without running out: place your reorder when you have approximately 25 checks remaining. Standard production and shipping at Checkomatic takes 3 to 5 business days. Twenty-five checks at typical business volumes (3 to 5 per day) gives you 5 to 8 business days of supply, enough buffer to cover the production and delivery window with a few days to spare.

For businesses with irregular check volume, adjust the number. If you write 20 checks on the last day of each month for vendor payments, having 25 checks on hand going into that month-end run is cutting it close. Reorder when you have 30 to 40 checks remaining if your check writing is concentrated in short bursts.

This is the most important timing question when you plan to reorder checks online: the situation where running out causes the most damage is payroll. If you issue payroll checks and run out before a pay date, your staff does not get paid on time. Beyond the obvious employee relations problem, late payroll carries legal risk in most states. Build your reorder trigger around payroll, not around general supplies: always have at least one full payroll run worth of checks in hand before placing a reorder.

If you have reached the point where you have fewer than 10 checks and still have business payments to make before your reorder arrives, consider using an alternative payment method for those transactions (ACH transfer, wire, or digital payment) to bridge the gap, rather than writing checks from a number range that may conflict with your new order.


How to Reorder Checks Online at Checkomatic: Step-by-Step

These steps cover a standard reorder of the same check format from a previous order. The full process takes under 5 minutes when your information is ready.


Step 1: Go to the Check Catalog

Visit checkomatic/business-checks and select the same check type you ordered previously. If you ordered computer checks last time, go to Computer Checks. If you ordered manual checks, go to Manual Checks. If you ordered QuickBooks-compatible checks, go to QuickBooks Checks. Select the specific format (check on top, check in middle, check on bottom, 3-on-page) and the quantity you want.


Step 2: Enter Your Business and Banking Information

Fill in your business name, address, ABA routing number, and checking account number. Enter your starting check number from the method you used in the previous section. Verify every digit before moving to the next field. One wrong digit in the routing number sends your checks to the wrong bank. A one-digit error in the account number produces checks your bank will reject at deposit.


Step 3: Choose Your Design Options

Select your background color, security level (standard or high-security), and any customization options. Upload your logo file if you want a logo printed. Black-and-white logo printing is free on every order. Full-color logo printing is available as an upgrade. Add extra signature lines if your business requires dual signatures on checks.


Step 4: Review the Digital Proof

When you reorder checks online, a digital proof is generated showing exactly how your checks will look. Read every field on the proof carefully:

  • Business name spelling and punctuation
  • Street address, city, state, and ZIP code
  • Bank name (if printed on the check)
  • Routing number (all 9 digits)
  • Account number (all digits)
  • Starting check number
  • Logo placement and appearance
  • Signature line count

Catching an error on the proof takes 30 seconds. Catching it after 500 checks are printed takes a reprint and additional days. Do not rush this step.


Step 5: Select Shipping and Complete Checkout

Choose standard shipping (included in base pricing) or a rush option if you need checks quickly. Complete checkout with your payment information. Your order enters production immediately after proof approval and payment confirmation. You will receive a shipping confirmation with a tracking number when the order leaves the Monroe, NY facility.


What to Update Versus Keep the Same

When you reorder checks online, most orders are identical to the previous order except for the starting check number. Here is what to review deliberately on every reorder rather than assuming nothing has changed.


Always Update on Every Reorder

  • Starting check number. This changes on every reorder by definition. Never use the same starting number as your previous order.


Update Only If Changed

  • Business address. If you moved since your last order, update the address on the check and verify it matches your bank's records for the account.
  • Authorized signer name. If the person whose name appears on the signature line has changed (ownership transfer, officer change), update accordingly.
  • Logo. If your logo has been redesigned, upload the new version. If the previous logo was correct, reuse it.
  • ABA routing number. Only changes if your bank merged with another institution or restructured its account types. Covered in detail in the next section.
  • Check format. Only if you have switched accounting software or changed your AP workflow. A format change requires a corresponding update in your accounting software's check style setting.


Do Not Change Without Telling Your Bookkeeper

  • Check number sequence. If you decide to start a new number range (e.g., jumping from the 1000s to the 5000s), tell your bookkeeper. They need to update the expected check number range in your accounting software to avoid reconciliation warnings.
  • Check format. Changing from voucher to 3-on-page, for example, changes how stubs are handled. Your bookkeeper's workflow for reconciling payments may depend on specific stub fields that change between formats.
  • Security level. Not a bookkeeping issue, but notify anyone responsible for verifying incoming checks, so they know to look for different security features.


What to Do If Your Bank Changed Your Routing Number

One important exception to a simple reorder checks online process: bank mergers and acquisitions are the most common cause of routing number changes for small businesses. When your bank is acquired by or merges with another institution, the surviving entity typically maintains one routing number and phases out the other. You may receive a letter from your bank stating that your routing number will change on a specific date.

When this happens, your existing check stock becomes invalid after the effective date of the routing number change. Checks with the old routing number may still clear for a brief transition period (banks typically provide a grace window of 30 to 90 days) but do not rely on this. Order new checks with the updated routing number before the transition date and plan to stop using old check stock by the effective date.

This situation is a new order, not a reorder, because the banking information has changed. You will need to submit a voided check or bank verification letter from the new account to confirm the new routing number before production begins. Checkomatic verifies every routing number against the Federal Reserve E-Payments Routing Directory before printing. If there is any discrepancy between the number you enter and the number on file at the Fed, the order is flagged before production rather than discovered when checks start bouncing.


What to Do If Your Address Changed

An address change when you reorder checks online is simpler than updating a routing number. Update your mailing address in the check order form and confirm that the new address matches what your bank has on file for the account. Your bank uses the address on the account for fraud detection: a check with a different address than what is on record can occasionally trigger a manual review.

Address changes do not require re-verification documents on a reorder from the same supplier. Your banking information (routing and account number) was already verified. The address on the check face is printed information, not a security element that affects MICR processing.

If you moved and have not yet updated your address with your bank, do both at the same time: update the bank first, then place the check reorder with the new address that matches your updated bank records. This avoids a mismatch between your check address and your account address.


Rush Reorder: When You Need Checks Fast

If you need to reorder checks online urgently and cannot wait for standard production, rush orders are available at Checkomatic for situations where you cannot wait for standard 3 to 5 business day production. Common scenarios that require a rush order include running out unexpectedly before a scheduled payroll run, a bank merger that invalidated your existing stock without enough advance notice, or discovering an error on your current check stock that makes them unusable.

To reorder checks online on a rush basis at Checkomatic: select the rush production option during checkout or contact the team before placing your order to confirm availability for your specific check type. Rush production completes printing within 1 to 2 business days. Combined with overnight shipping, checks can reach most US locations within 2 to 3 business days from your order date.

For an emergency where you have zero checks and need to make payments immediately while your order is in production, consider these bridge options:

  • ACH transfers through your bank's online portal (same-day or next-business-day arrival depending on cutoff times)
  • Wire transfers for large vendor payments where speed is worth the wire fee
  • Manual checks from a different account if your business has multiple checking accounts
  • Requesting a short payment extension from a vendor (most vendors are understanding about a 2 to 3 day delay when given advance notice)


Same Supplier or Switch: What Changes and What Does Not

When you reorder checks online from the same supplier you used before, the process is simpler because your previous order information is on file, your routing number was already verified, and you know the checks cleared at your bank without issue. The reorder process is faster and the output is predictable.

Switching to a new supplier for a reorder requires the same process as a first-time order at that supplier: submitting a voided check for verification, allowing extra time for the verification step, and running a test batch before ordering a full year's supply. The Checkomatic switching guide recommends ordering a smaller test batch first (250 checks) to confirm print quality, MICR reading, and turnaround time before committing to a large order.

From a banking and accounting standpoint, switching suppliers changes nothing material. The same routing number and account number appear on the new checks. Your vendors will receive checks that look slightly different (different design, security background, or color) but the payment instrument is identical. Your bank reads the MICR line, not the check design.

The one scenario where switching suppliers creates a brief adjustment is lockbox payment processing. If a vendor uses an automated lockbox to scan incoming checks, a significantly different MICR placement or check dimension can occasionally require a one-time manual review. This is rare and usually resolves itself after the first check clears. If you pay vendors who specifically process via lockbox, it is worth checking whether they have any check formatting requirements before switching.


What Not to Change Without Telling Your Bookkeeper

Several changes that seem minor when you reorder checks online create real problems on the bookkeeping side if they happen without communication.


Changing the Check Number Range

If you decide to start a new number sequence on your next order (for example, jumping from 2500-series numbers to 5000-series) without telling your bookkeeper, your accounting software will likely flag the new numbers as out of sequence and may generate reconciliation warnings. Tell your bookkeeper the new starting number before the first check from the new batch is written.


Changing the Check Format

Switching from voucher checks to 3-on-page, or from 3-on-page to manual checks, changes how your bookkeeper reconciles vendor payments. Voucher checks travel with a remittance stub that gives vendors invoice-level detail. Switching to 3-on-page moves that record into QuickBooks only. Your bookkeeper needs to know this before they start asking vendors why the stub is missing.

Also, changing the check format requires updating the check style setting in your accounting software. In QuickBooks Desktop, go to File, Printer Setup, Form Name: Check, and update the Check Style to match your new format. If you forget this step and run a print job, the output will be misaligned because QuickBooks is printing to a template that no longer matches your physical check stock.


Adding a Second Authorized Signer

If you add an extra signature line to your checks for a new required signer, your bookkeeper needs to update the check approval workflow. Checks that now require two signatures but come back with only one will be rejected by your bank if your bank enforces dual-signature requirements.


Business Checks Available at Checkomatic

When you reorder checks online at Checkomatic, all check types are manufactured at our Monroe, NY facility. Every reorder ships with the same six CPSA-certified security features at base price: chemically sensitive paper, microprinting, void pantograph, UV fluorescent fibers, heat-sensitive ink, and pre-encoded MICR. Free black-and-white logo printing on every order.


Computer Checks

Ready to reorder checks online? Four computer check formats for QuickBooks, Xero, Sage, MYOB, Quicken, and over 500 other platforms: check on top, check in middle, check on bottom, and 3-on-page. Prices from $19.79 for 50 checks. Order at checkomatic/computer-checks.


Manual Business Checks

Three formats: Accounts Payable, Payroll, and Multi-Purpose. Available in 1-part and 2-part (carbon copy). 7-ring binder compatible. From $42.79 for 300 checks. Order at checkomatic/manual-checks.


QuickBooks-Compatible Checks

Voucher, standard, and wallet formats. Compatible with all QuickBooks Desktop and Online versions. Includes the QuickBooks Starter Pack (checks, deposit slips, envelopes, endorsement stamp in one order). Order at checkomatic/quickbooks-checks.

Blue


Personal Checks

For personal checking accounts. Multiple designs, security features included, free logo printing option. Order at checkomatic/personal-checks.

American Flag

For the full range including deposit slips, envelopes, and endorsement stamps, see checkomatic/business-checks.


What Customers Say About Checkomatic

Here is what customers say about using Checkomatic to reorder checks online, published on checkomatic.com and reproduced verbatim. Source: checkomatic.com/quickbooks-starter-pack, 4.5 stars from 166 verified customer reviews.

"Been with them for 15 years. Always reliable, always good quality, good service. What more can you ask for?"

ATV Inc. | ★★★★★ 5/5 | April 5, 2024 | Source: checkomatic.com/quickbooks-starter-pack

"We use CheckoMatic for all of our check needs! They have great prices and we receive our products in a timely manner!"

CG's Tax Service | ★★★★★ 5/5 | September 18, 2024 | Source: checkomatic.com/quickbooks-starter-pack

"First time ordering and I am super impressed with the quality of the checks. No issues with delivery. I will be ordering again!"

TClinton | ★★★★★ 5/5 | April 9, 2025 | Source: checkomatic.com/quickbooks-starter-pack

"I got 500 checks for less than half of what the bank wanted for 200!"

VVA Voucher Checks (Vietnam Veterans of America) | ★★★★★ 5/5 | July 6, 2024 | Source: checkomatic.com/quickbooks-starter-pack

"ASJ Wilson Construction has been a client of Checkomatic for some years now and they've never disappointed this company. Thank you Checkomatic for all that you do."

ASJ Wilson Construction | ★★★★★ 5/5 | June 6, 2024 | Source: checkomatic.com/quickbooks-starter-pack

"Affordable and efficient. My go-to business check printer."

Doe | ★★★★★ 5/5 | January 24, 2025 | Source: checkomatic.com/quickbooks-starter-pack

All reviews reproduced verbatim. Read the full set at checkomatic/business-checks.


Why Choose Checkomatic for Your Check Reorders

When You Reorder Checks Online: 3 to 5 Business Days vs 7 to 14

Banks issue checks through third-party printers on batched schedules. Standard bank-issued check delivery takes 7 to 14 business days. Checkomatic ships most reorders within 3 to 5 business days from Monroe, NY because production runs continuously, not on a batch schedule. Rush options ship within 1 to 2 business days when you need checks urgently.


Price: 50 to 70 Percent Below Bank Retail

Bank-issued business check pricing typically runs $30 to $50 for 100 checks. Checkomatic computer checks start at $19.79 for 50 checks, and the per-check price drops significantly at higher quantities. The Vietnam Veterans of America chapter confirmed this in a verified review: 500 checks for less than half of what their bank charged for 200.


Routing Number Pre-Verification on Every Order

Checkomatic verifies every routing number against the Federal Reserve E-Payments Routing Directory before printing begins. If your routing number has changed after a bank merger and you enter the old number, the order is flagged before production. This catches the most damaging reorder mistake (wrong routing number) before it produces a box of unusable checks.


Six Security Features at Base Price

Every check includes chemically sensitive paper, microprinting, void pantograph, UV fluorescent fibers, heat-sensitive ink, and pre-encoded MICR at the standard price. No security tier upgrades required to get meaningful fraud protection. For a full explanation of what each feature does, see our check types and security terminology guide.


Free Logo on Every Order

Black-and-white logo printing is included at no extra cost on every reorder. Full-color logo printing available as an upgrade. No minimum quantity for free logo setup.


In-House Manufacturing in Monroe, NY Since 1997

All checks are printed at Checkomatic's own facility. Your banking information never passes through third-party print vendors. Every reorder is handled by the same manufacturing team that handled your original order.


Quick Summary: How to Reorder Business Checks Online

Keywords covered in this guide: how to reorder checks online, reorder business checks, reorder personal checks, reorder checks online, business check reorder, need to order checks online, order checks online fast delivery, order checks fast shipping, order checks overnight, order checks next day delivery, starting check number reorder, where to find starting check number, QuickBooks check number reorder, check reorder checklist, when to reorder checks, how many checks to order, rush check order, order checks 3 to 5 business days, reorder business checks online, check reorder information needed, routing number account number checks, reorder checks after bank merger, Checkomatic reorder, ABA compliant checks reorder, free logo checks reorder, Monroe NY check reorder.

When you need to know how to reorder checks online, this is the complete summary: gather your business name, mailing address, ABA routing number, checking account number, and starting check number (one above the highest check number you have already written). In QuickBooks Desktop, find the highest check number in Banking, Use Register, sorted descending. In QuickBooks Online, run a Check Detail report sorted by number. Without software, read the last stub in your manual check binder. Reorder when you have 25 checks remaining for a 5 to 8 business day buffer. At Checkomatic, the reorder form takes under 5 minutes to complete.

Review the digital proof carefully before approving, especially the starting check number, routing number, and business address. Standard reorders ship in 3 to 5 business days from Monroe, NY. Rush production options are available for urgent needs.

If your routing number changed after a bank merger, treat this as a new order and submit a voided check with the new account information. Tell your bookkeeper before changing the check number sequence or check format on a reorder. This guide covers the keyword "how to reorder checks online," "reorder business checks," "order checks fast delivery," "order checks next day delivery," "order checks overnight," "order checks fast shipping," and "need to order checks online" , all from the Checkomatic search performance data showing high impression counts and low click rates that this post is written to improve.


Accepted by the world’s leading banks

Bank of America logo
Capital One logo
Citibank logo
Wells Fargo logo
TD Bank logo
Chase bank logo
;